


Learn Why The Bull Case For Darden Restaurants Stock Could Change Following Full Year Outlook Kept
- Darden Restaurants recently drew attention after analysts indicated the company is expected to maintain its full year outlook despite softer performance at Olive Garden in the fiscal first quarter.
- The key consideration for investors is how Darden Restaurants balances resilient group-level guidance with signs of pressure at its flagship casual dining brand.
- This article will explore how Darden Restaurants' investment narrative holds up when full year guidance is expected to stay intact despite Olive Garden softness.
Stress test your thesis on Darden Restaurants by comparing it with a hand picked group of resilient casual dining and consumer-facing operators in our list of solid balance sheet and fundamentals (23 results)
Darden Restaurants Investment Narrative Recap
To own Darden Restaurants, you need to believe the group can offset softer Olive Garden traffic with strength across LongHorn, fine dining and newer concepts, while keeping margins in a reasonable range despite higher complexity from delivery and promotions. The recent signal that full year guidance is expected to hold suggests the short term focus stays on execution rather than a reset of expectations.
The key near term catalyst is how quickly Olive Garden can stabilise guest counts without eroding already strong profitability at that banner. The biggest risk is that casual dining traffic pressure deepens at the same time delivery remains only partially incremental, which could squeeze net margins if promotional and operating costs rise.
The Uber Direct rollout at Olive Garden looks most relevant to this update. Nearly all locations now offer the service, which puts more of Darden Restaurants’ core Italian concept in front of convenience focused customers at a time when in restaurant demand is under scrutiny. The question for you is whether this channel becomes a meaningful traffic and check driver or just a margin drag.
Incrementality matters. If a large share of delivery orders simply replace on premise occasions, the added operational complexity and fees can weigh on profitability just as other costs remain sensitive to supply chain and wage trends. If management can keep execution tight, this delivery footprint can still support the broader guidance story that investors are watching around fiscal 2026.
Darden Restaurants' narrative projects US$15.4b revenue and US$1.5b earnings by 2029. This assumes 5.3% yearly revenue growth and an earnings increase of about US$300m from US$1.2b today.
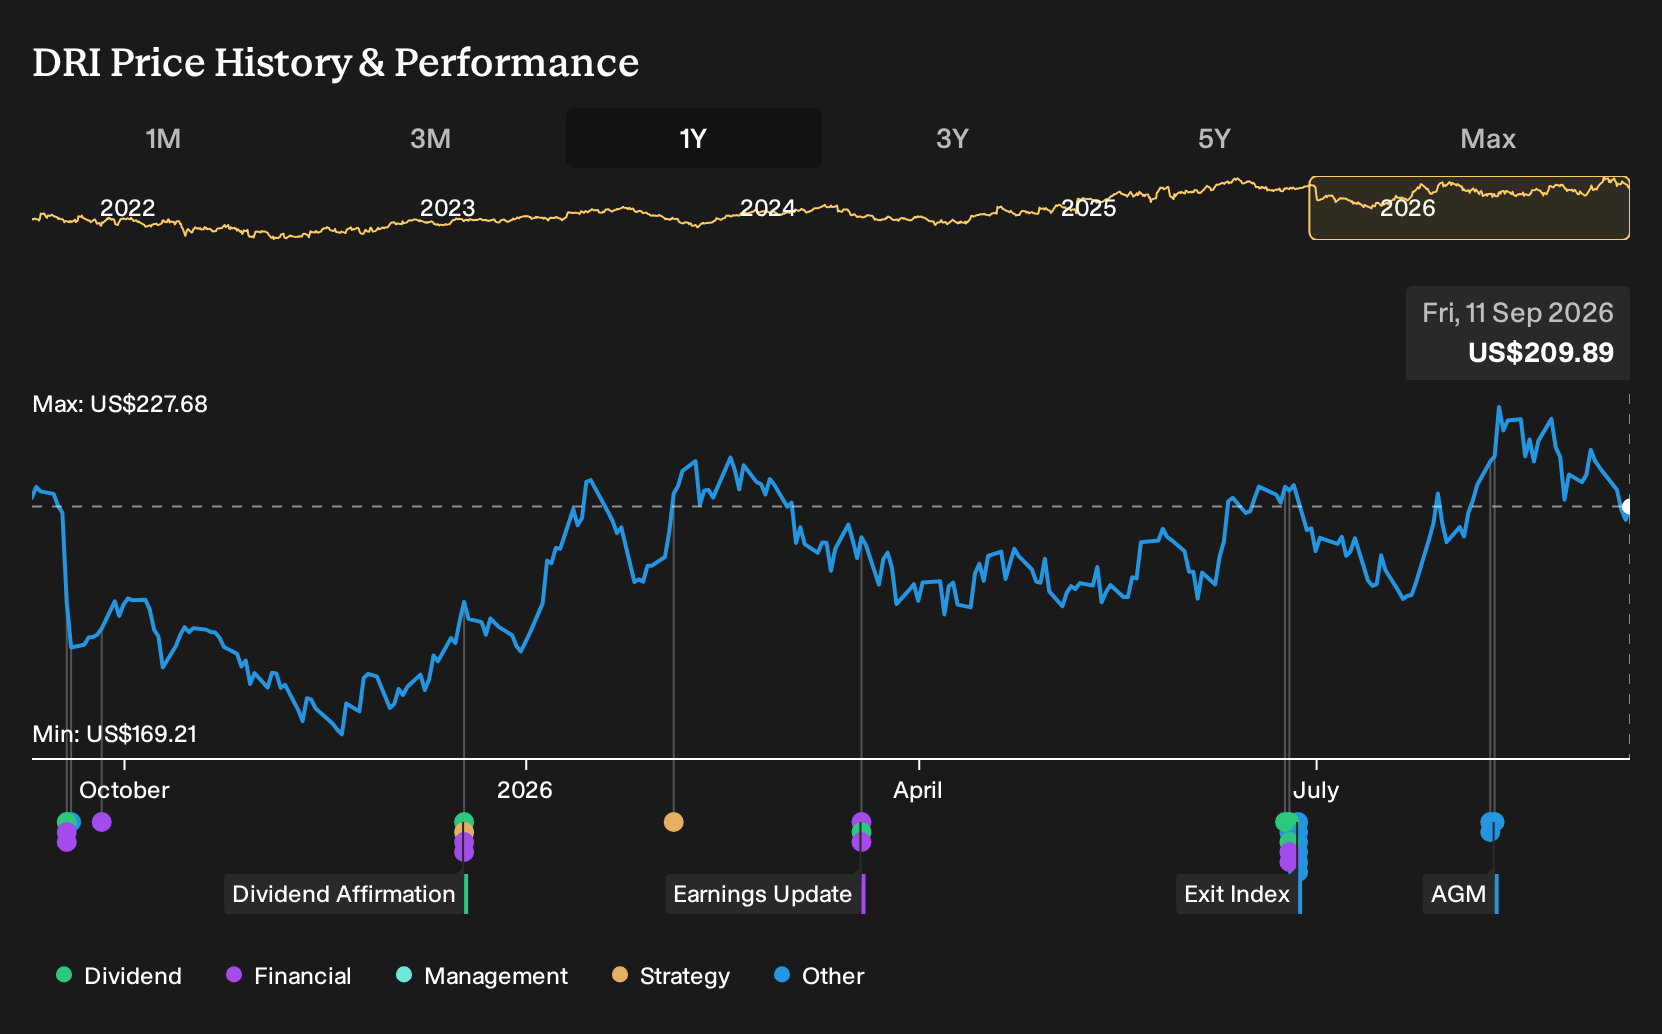
Uncover how Darden Restaurants' fair value indicates a 9% potential upside to its current price, which could narrow quickly if sentiment turns more optimistic.
Exploring Other Perspectives
For a very different angle, focus on digital risk. The most pessimistic analysts worry that Darden Restaurants is too reliant on traditional formats and slower tech adoption, and were modeling about US$14.9b in revenue and US$1.4b in earnings by 2029. Those views were set before this guidance news, so treat them as moving targets and compare several narratives before deciding what you believe.
Explore 3 other Darden Restaurants fair value estimates, including one that suggests it could be worth just $225.87.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Darden Restaurants research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Darden Restaurants. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Darden Restaurants' overall financial health at a glance.
Looking For More Investment Ideas Beyond Darden Restaurants?
If this update on Darden Restaurants has sharpened your thinking, the next step is to pressure test your portfolio against other opportunities with different risk and income profiles.
- For investors who want income with resilience, scan a curated set of companies offering strong yields and robust payout profiles through our 6 dividend fortresses.
- If capital preservation matters most, focus on businesses with steadier balance sheets and lower overall risk using the 11 resilient stocks with low risk scores.
- Prefer to get in before the crowd, while fundamentals still look solid? Review a hand picked pool of under-the-radar opportunities in the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com