


Central Garden & Pet (CENT) Stock Looks Fairly Valued As Its 26% Run Continues
Central Garden & Pet has gained 25.8% year to date, yet current valuation checks suggest the stock now looks closer to fairly priced than like an obvious bargain.
- The 25.8% year to date gain highlights that recent buyers have already seen a solid move, which can reduce the margin of safety for new entrants.
- Management’s push to sharpen margins and expand internationally through acquisitions may support earnings power, while any stumble in integrating new businesses could weigh on what investors are willing to pay.
- The broader valuation score, at 3 out of 6 checks, points to a mixed picture rather than clear cheapness or clear expensiveness.
The issue now is whether Central Garden & Pet’s recent share price strength already reflects its fundamentals, or if there is still room for further upside without stretching valuation.
Balance recent gains in Central Garden & Pet with other ideas by scanning our screener containing 15 high quality undiscovered gems that are still flying under most investors' radar.
Is Central Garden & Pet Fairly Priced on Earnings?
The P/E ratio works well for Central Garden & Pet because the business is currently profitable and investors can tie the share price back to its earnings base. On this measure, the stock trades on about 15.1x earnings, which is below the Household Products industry average of roughly 16.6x and the peer group at about 21.2x.
The fair P/E multiple implied by the broader model is near 16.4x, only slightly above where Central Garden & Pet is now, so the gap is relatively narrow. Despite the recent guidance raise drawing attention to the story, the market is valuing those earnings at a level that is closely aligned with what the model suggests based on the company’s profile and risk mix.
On balance, Central Garden & Pet appears roughly fairly valued on its current P/E multiple.
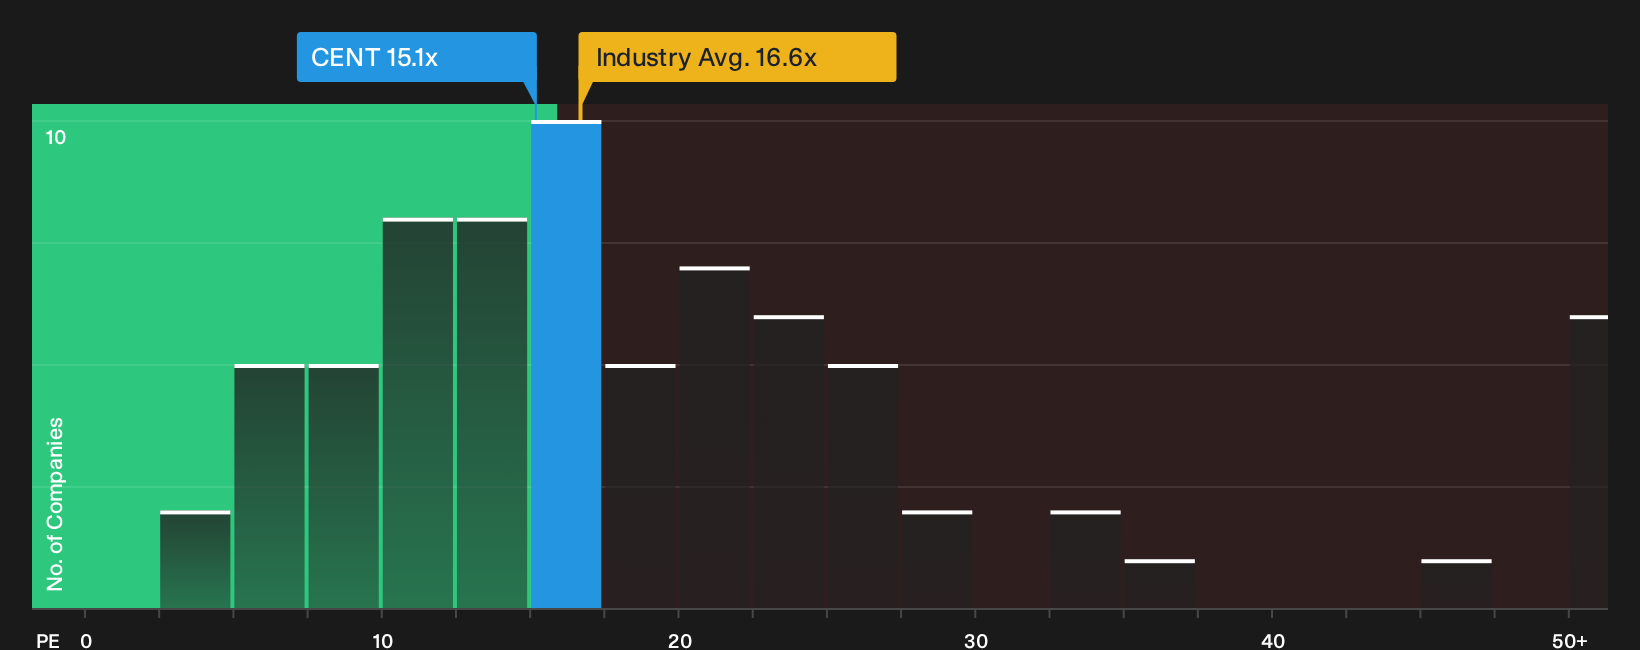
See what the numbers say about this price — find out in our valuation breakdown.
The Central Garden & Pet Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for Central Garden & Pet. They describe which combination of growth, profitability and earnings resilience would need to occur for the current quotation to appear conservative or stretched. Each narrative links a fair value estimate to a specific set of potential catalysts and pressure points so you can track over time which version of Central Garden & Pet's story is actually unfolding on Simply Wall St's Community page.
One of the top community narratives on Central Garden & Pet: 24% undervalued
"Exposure reduction to lower-margin or volatile product lines, along with a strategic mix shift toward consumables and premium offerings, is increasing gross margins and positioning the company for more resilient, higher-quality earnings in the coming years..."
Read one of the top narratives on Central Garden & Pet
Do you think there's more to the story for Central Garden & Pet? Head over to our Community to see what others are saying!
The Bottom Line
Central Garden & Pet now trades on a P/E that looks broadly in line with what its peers and the valuation checks suggest. For new money, the central question is less about a clear discount and more about whether earnings quality and margins keep improving enough to support this going rate. The bull story leans on the shift toward higher margin, more resilient categories. The bear case focuses on integration risk from acquisitions and the chance that execution wobbles could limit how much investors are willing to pay for Central Garden & Pet from here.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com