


Entergy (ETR) Stock Looks Pricey On Dividends And Earnings After 136% Run
Entergy stock has delivered a very strong run over the past few years, yet the current share price screens as expensive when lined up against both an intrinsic value estimate and market multiples. For investors, the question is whether a rich valuation is now baked in after that performance.
- The share price has returned about 136.0% over the past 3 years, which leaves today’s level framed by a history of strong gains rather than recent weakness.
- Adoption of tools like OATI’s webLineR to manage transmission ratings can support operational efficiency. However, any setback in grid reliability or capital project execution may weigh on how much investors are willing to pay for Entergy’s future cash flows.
- On a broad set of six valuation checks, Entergy is classified as overvalued in all of them. The resulting low value score of 0 suggests the stock does not screen as a clear bargain right now.
The issue now is whether Entergy’s current price leaves enough room for investors who are buying in after this multi year climb.
Broaden your watchlist by comparing Entergy’s rich valuation with 32 high quality undervalued stocks, which screen as better priced on fundamentals.
Has Entergy Run Too Far on Dividends?
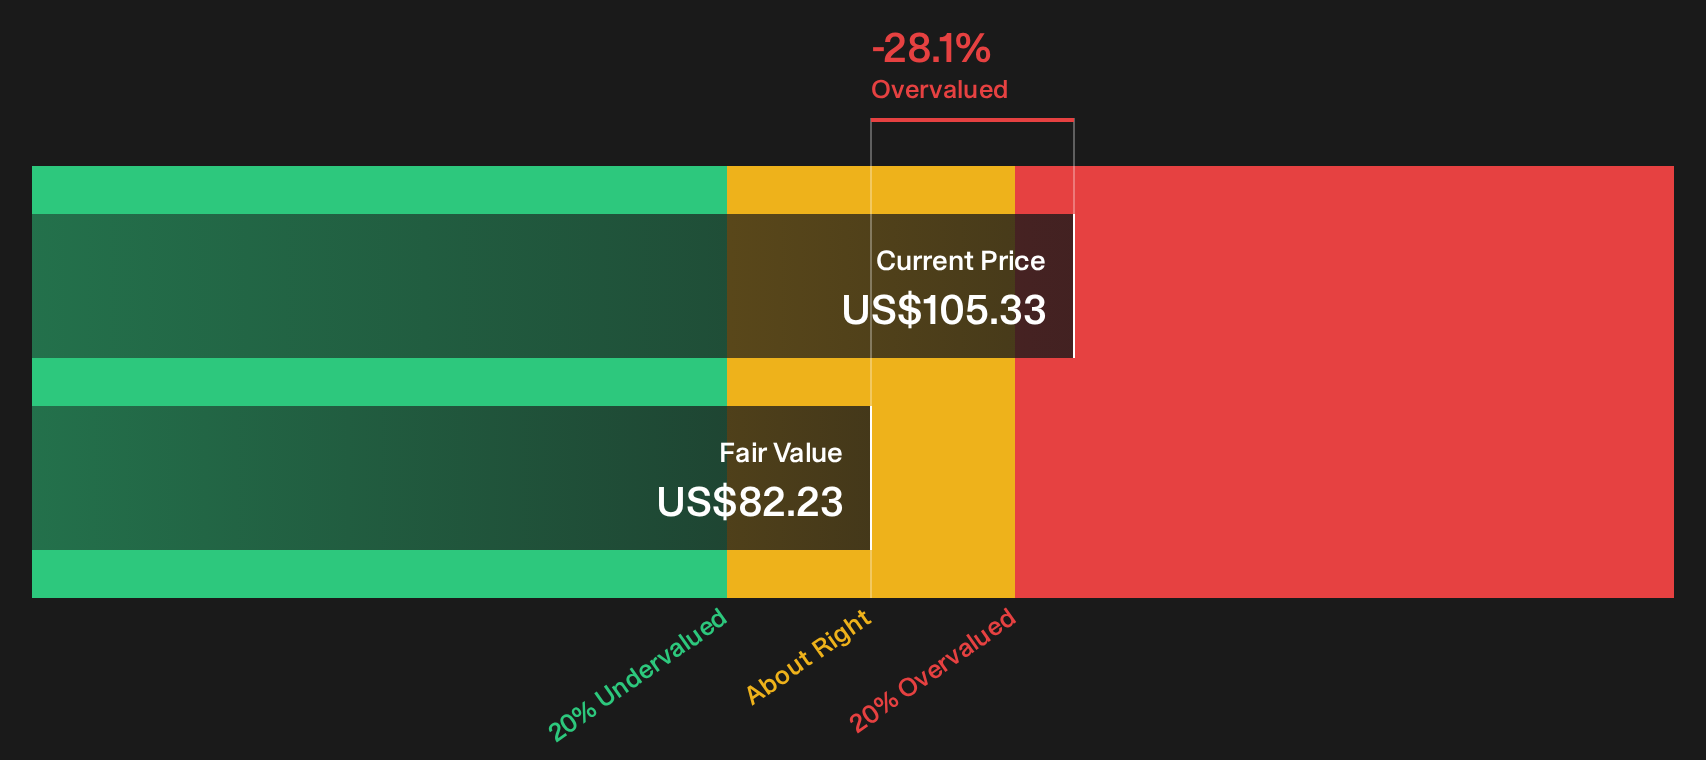
The Dividend Discount Model looks at what Entergy can reasonably pay out to shareholders over time and then works back to an implied share price today. For Entergy, the model uses a recent dividend of about $2.91 per share, a return on equity of 11.16%, and a payout ratio a little above 61%, which suggests the current dividend is covered by earnings rather than being stretched.
Growth in those payouts is capped at 3.7% in the model even though the broader expected growth input is slightly higher, which keeps the assumptions on Entergy’s future dividend stream restrained. That produces an estimated intrinsic value of about $82 per share. The current P/E of 28.0 sits above both the stock’s own fair P/E estimate of 25.2 and the Electric Utilities sector average of 20.3, pointing to a premium valuation. Because the DDM output implies the shares trade roughly 28.1% above intrinsic value, the pricing appears consistent with the earlier valuation checks. The recent adoption of OATI’s webLineR, which targets better transmission capacity and reliability, may help explain why the market is comfortable paying a higher multiple despite the DDM signal.
On this dividend based model, Entergy screens as overvalued with the market price running ahead of its implied payout potential.
Our Dividend Discount Model (DDM) analysis suggests Entergy may be overvalued by 28.1%. Discover 32 high quality undervalued stocks or create your own screener to find better value opportunities.
Has Entergy Run Too Far on Earnings?
P/E works well for Entergy because earnings and dividends are key to how investors usually value a regulated utility.
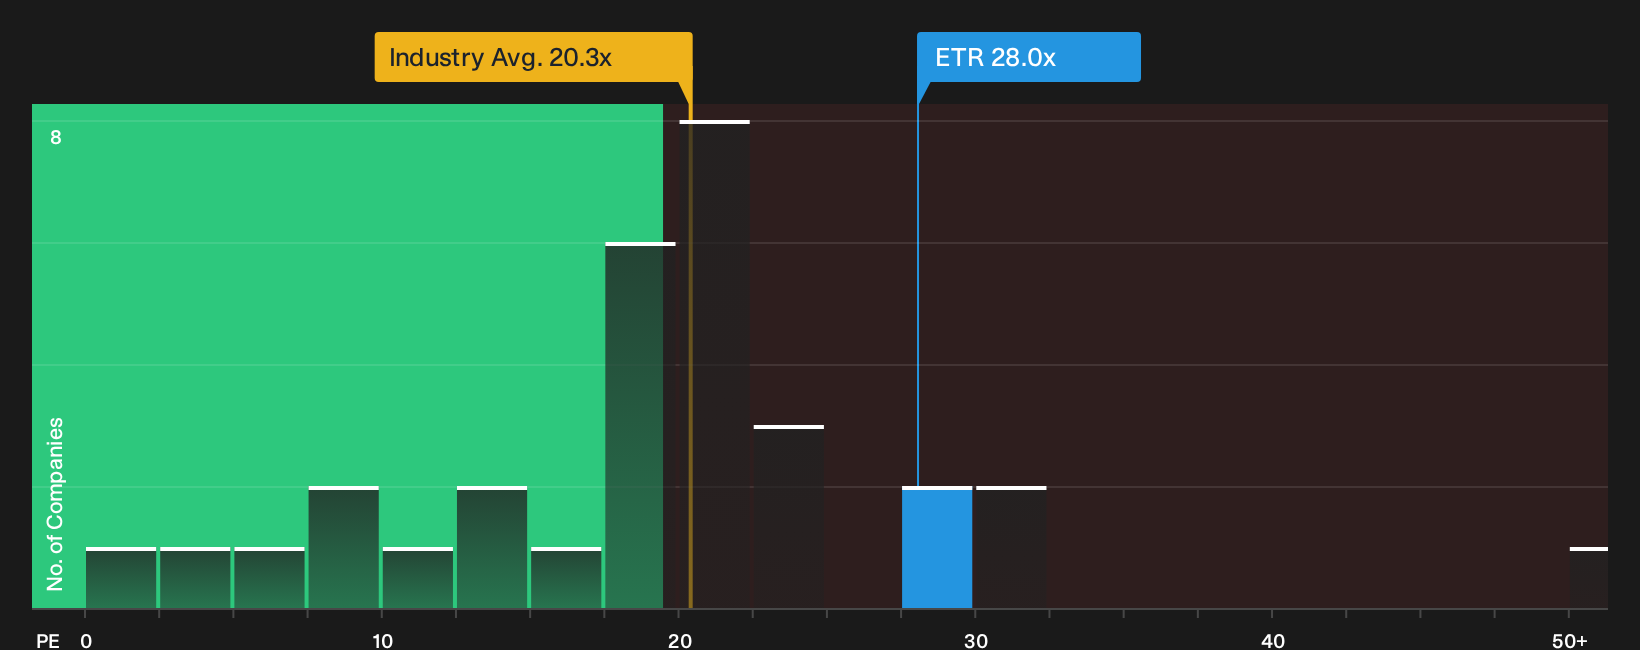
On this measure, Entergy trades on a P/E of about 28.0x. That sits above the Electric Utilities industry average of roughly 20.3x and also above a peer group mark around 17.1x. The stock also screens richer than its own fair P/E estimate of about 25.2x, which reflects what investors might typically pay given the company’s size, sector and risk profile.
The roughly 2.8 turn gap between Entergy’s current P/E and that fair multiple points to a premium that already prices in strong expectations. For anyone considering Entergy after a strong share price run, this higher earnings multiple means there is less of a valuation cushion if sentiment cools.
On the P/E yardstick, Entergy appears overvalued, with the market asking a higher price for each dollar of earnings than its fundamentals and peers would usually command.
See what the numbers say about this price — find out in our valuation breakdown.
The Entergy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Entergy pick up where the valuation puzzle leaves you. They spell out what kind of future for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price on the Community page. Each scenario ties its number to a clear view of where profitability and risk could move next, which you can revisit as fresh information comes through.
Share a narrative on Entergy that puts numbers around whether OATI’s webLineR rollout really delivers on reliability, cost savings and clean energy deployment. Add your voice to the Simply Wall St community and track how your thesis holds up as fresh data on Entergy’s execution lands.
Do you think there's more to the story for Entergy? Head over to our Community to see what others are saying!
The Bottom Line
Entergy now screens as overvalued on both the Dividend Discount Model (DDM) intrinsic value estimate and on earnings based market multiples. That combined message points to a situation where a lot of future execution and reliability benefits, including from projects like OATI’s webLineR rollout, are already reflected in the share price. For prospective investors, the key question is whether the business can deliver the cash flows and grid performance needed to keep that premium multiple intact, rather than see the valuation move back toward utility peers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com