


Can Moderna (MRNA) Trade At A Premium After Flu Approval?
Moderna stock has delivered a very large 1 year gain, yet current valuation checks suggest the shares trade at a premium to what its cash flows and market multiples imply.
- The share price has returned a very large 1 year gain of about 5x, which puts extra pressure on future cash flows to justify today’s level.
- Approval of Moderna’s mRNA flu vaccine mFLUSIVA and progress on the bird flu program can support growth expectations. However, execution risk in late stage trials and future competition from GSK may affect how durable those expectations prove to be.
- The broader valuation workup, including the Discounted Cash Flow (DCF) intrinsic value estimate and market multiples, points to an expensive profile, with a low value score of 0 out of 6 suggesting Moderna is not a clear bargain on these checks.
The issue now is whether Moderna’s recent gains leave enough valuation support, or whether the current price already bakes in most of the good news on its mRNA vaccine pipeline.
Spot potential Moderna lookalikes by scanning our screener containing 15 high quality undiscovered gems with strong fundamentals before they reach the front page.Does Moderna Look Pricey on Cash Flow?
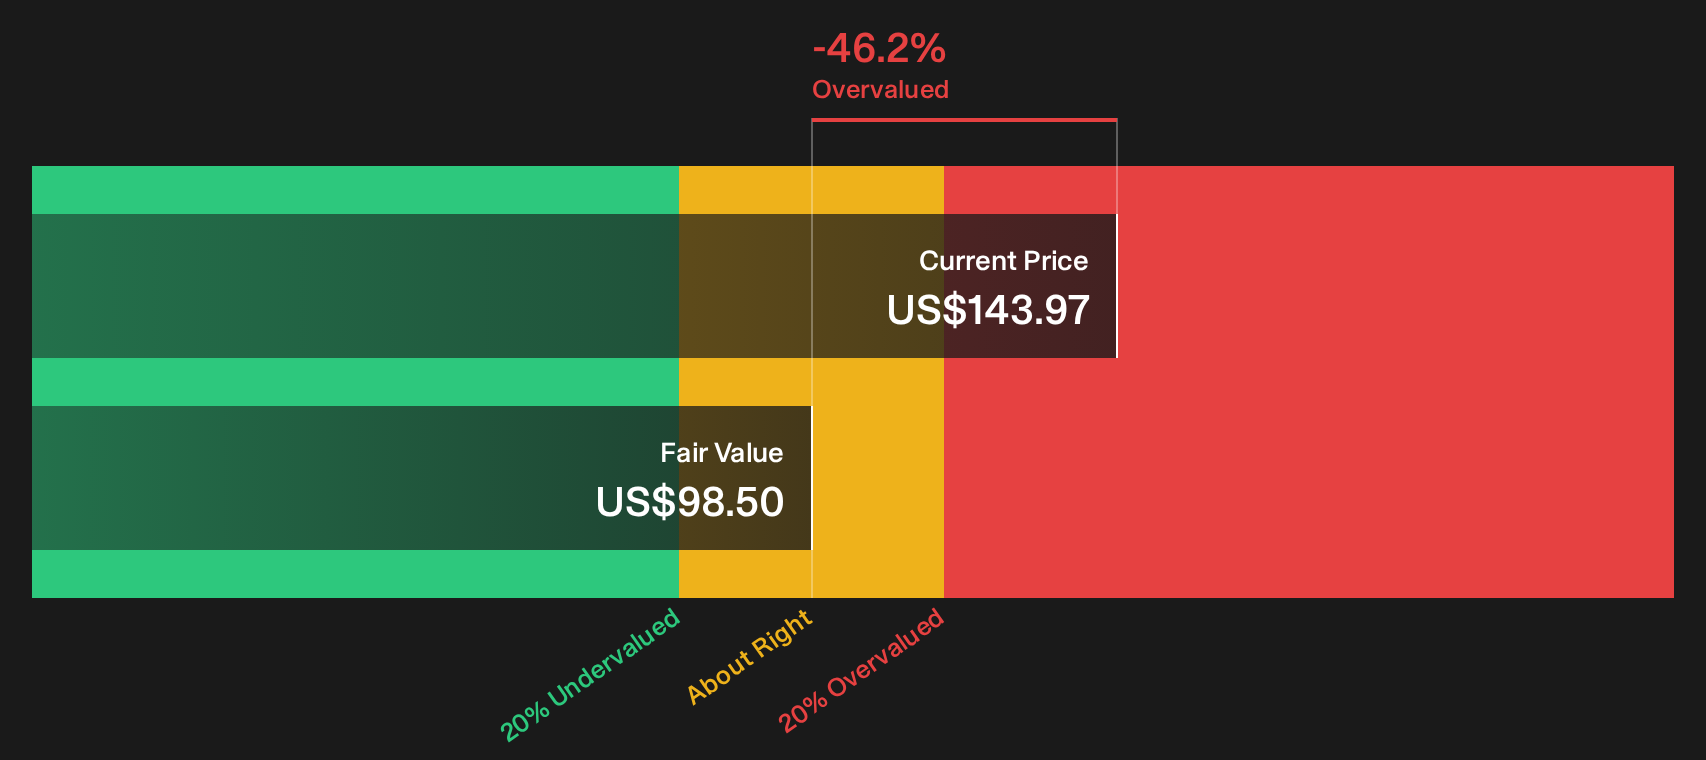
The Discounted Cash Flow (DCF) model estimates what Moderna might be worth based on projected cash that could flow to shareholders. Moderna currently reports latest twelve month free cash flow of about $1.44b in the red. The model assumes a recovery to positive and growing cash generation over the coming decade. On those assumptions, the DCF points to an intrinsic value of about $98 per share.
That $98 estimate sits well below where Moderna trades today, implying the stock is about 46.2% overvalued on this cash flow view. FDA approval of mFLUSIVA adds a concrete product milestone. However, the market price already embeds meaningful expectations for that flu franchise and the wider mRNA pipeline.
On these DCF assumptions, Moderna stock screens as overvalued relative to the cash flows currently built into the model.
Our Discounted Cash Flow (DCF) analysis suggests Moderna may be overvalued by 46.2%. Discover 32 high quality undervalued stocks or create your own screener to find better value opportunities.
Does Moderna Look Pricey on Sales?
P/S works reasonably well for Moderna because investors are paying more for future vaccine franchises than for current profits.
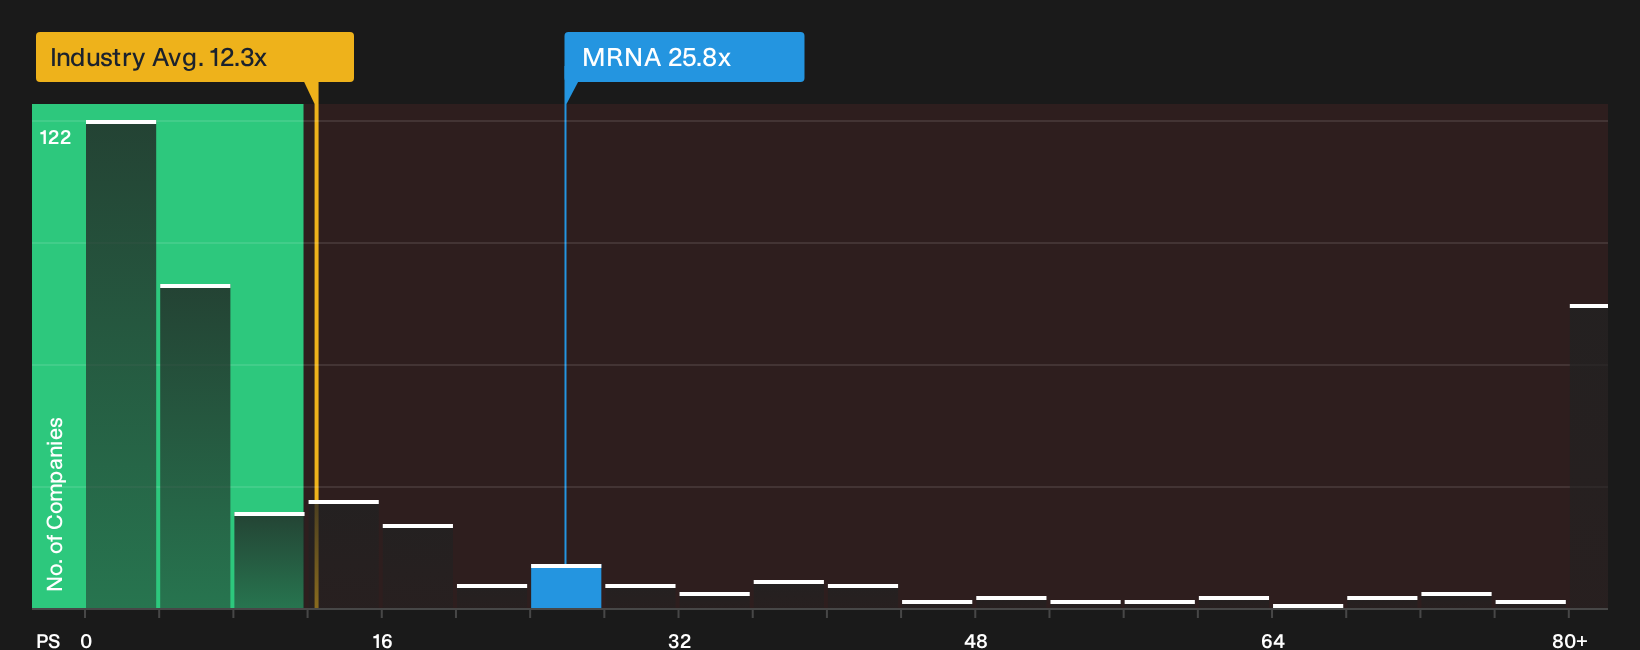
The stock trades on a P/S ratio of about 25.8x, which is more than double the broader biotech industry average of 12.3x and well above the peer group at roughly 8.4x. On Simply Wall St’s fair multiple framework, which adjusts for Moderna’s scale, margin profile and risk factors, the implied P/S closer to 4.2x indicates that the current valuation reflects a substantial premium for future mRNA revenue.
The gap between the present P/S and that fair marker is very wide, and the model is effectively flagging that losses and execution risk are weighing on the implied “normal” multiple. The figure is better read as an indication that Moderna appears very expensive on sales-based checks rather than as a precise target number.
On the P/S lens, Moderna stock appears richly valued, with the market paying a high price for each dollar of revenue today.
See what the numbers say about this price — find out in our valuation breakdown.
The Moderna Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Moderna pick up where the valuation questions leave you. They spell out which paths for Moderna's growth, profitability and earnings would need to play out for the shares to be worth meaningfully more or less than today. Instead of giving a single output from a ratio or model, they lay out the future that figure relies on so you can see what needs to happen and track whether it actually does on the Community page.
Community narratives around Moderna are miles apart, with one group leaning into oncology upside and another fixated on execution risk and pipeline spend.
Bull case: 15% undervalued
"Relentless progress in individualized cancer vaccines, expanding into both adjuvant and metastatic settings, positions Moderna as a future leader in high-value, personalized medicine markets..."
Read the full Bull Case to see why Moderna could be undervalued
Bear case: 225% overvalued
"Heavy reliance on cost reduction strategies, including significant R&D cuts, portfolio prioritization, and a 10% workforce reduction, risks constraining future innovation and pipeline productivity if new launches or late-stage program results disappoint..."
Read the full Bear Case to see why Moderna could be overvalued
Do you think there's more to the story for Moderna? Head over to our Community to see what others are saying!
The Bottom Line
Moderna appears overvalued on both the Discounted Cash Flow (DCF) intrinsic value estimate and on sales-based multiples, which points to a rich price tag rather than a margin of safety. The disagreement between bulls and bears now largely comes down to how much cash the mRNA pipeline can generate, and how quickly, relative to the premium investors already pay for each dollar of revenue. The key question is whether future vaccine launches and oncology partnerships can translate into durable, high quality cash flows that eventually meet the expectations embedded in today’s valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com