


Is Arcosa (ACA) Fully Priced As It Reaffirms Its Dividend?
Arcosa (ACA) has affirmed a regular quarterly cash dividend of $0.05 per share, payable on October 30, 2026, to shareholders of record on October 15, 2026, underscoring its current cash return policy.
Recent trading has been muted, with the share price roughly flat over the past month. However, Arcosa’s 90-day share price return of 12.89% and one-year total shareholder return of 52.56% point to building momentum that this latest dividend affirmation fits into.
Compare Arcosa’s dividend move to a curated 6 dividend fortresses list that combines income potential with staying power.
Arcosa shares have surged over the past year while the cash payout stays modest and the price now sits close to analyst targets. Is it better to step in at this level or hold out for a cheaper entry?
Most Popular Narrative: 1% Undervalued
Arcosa’s most followed narrative pegs fair value at $146, almost exactly in line with the recent $145 close. This puts this dividend decision under a finely balanced spotlight.
The analysts have a consensus price target of $146.0 for Arcosa based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $2.6 billion, earnings will come to $248.1 million, and it would be trading on a PE ratio of 38.0x, assuming you use a discount rate of 9.5%.
Want to see what justifies that near one for one match between price and fair value? The narrative leans heavily on margin strength, acquisition benefits, and a richer earnings multiple that assumes investors stay comfortable paying up for Arcosa’s earnings profile.
Result: Fair Value of $146 (ABOUT RIGHT)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Arcosa’s reliance on government funded infrastructure work and its use of acquisitions to support the business both leave this narrative exposed if funding or integration progress falters.
Find out about the key risks to this Arcosa narrative.
Another View on Arcosa’s Valuation
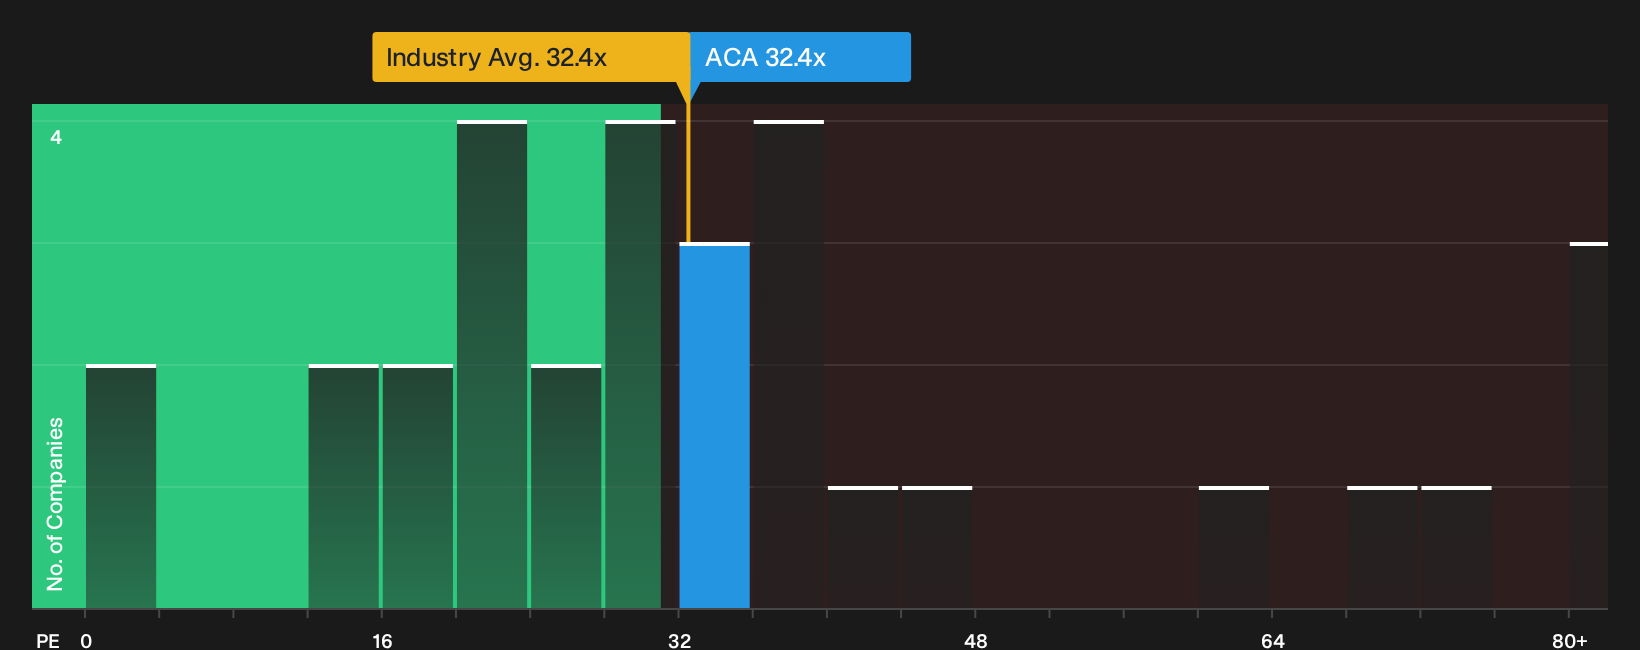
The earlier narrative pins Arcosa close to fair value at around $146 per share. A simple P/E check tells a tougher story. The stock trades on 32.4x earnings while peers average 23.1x and the fair ratio sits near 15x, which points to meaningful valuation risk if sentiment cools.
For investors who anchor on earnings multiples rather than detailed forecasts, that kind of gap can matter more than a 1% perceived undervaluation on a model. The question is which reference point you trust most when you think about future downside versus upside.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Arcosa’s valuation narrative and risks can pull you in both directions, so move fast, review the underlying data, and weigh the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Arcosa?
If Arcosa has sharpened your focus on valuation and income, you can use this momentum to widen your watchlist with a few targeted idea hunts built around clear fundamentals.
- Target resilience first and scan a 11 resilient stocks with low risk scores to see businesses that pair lower risk scores with balance sheet strength and steadier financial profiles.
- Hunt for pricing gaps using a 32 high quality undervalued stocks that highlights companies with solid cash flows and quality metrics that differ from where the market currently prices them.
- Spot fresher stories by running a 15 high quality undiscovered gems focused on lesser-known stocks that already show robust fundamentals before broader attention arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com