


Learn Why The Bull Case For Kohl's Stock Could Change Following Babies R Us Expansion
- Kohl's is rolling out additional Babies"R"Us shop in shop locations, while recent data shows a 0.9% decline in comparable sales, a 6.5% drop in operating income, and a 1.4% fall in customer visits, alongside new merchandising leadership and fresh brand partnerships.
- The combination of expanded Babies"R"Us presence and Sephora at Kohl's additions shows management leaning on third party brands to lift traffic in a tougher retail climate.
- We will now look at how Kohl's investment narrative could be affected by the wider Babies"R"Us rollout across more stores.
Kohl's Investment Narrative Recap
To own Kohl's, you need to believe the retail model can stay relevant as shoppers move online and off price chains pull away demand. The near term story hinges on whether new shop in shop concepts and refreshed brands can slow the pressure on traffic and comps without giving up too much margin through promotions.
The biggest swing factor over the next few quarters remains customer visits. Expanded Babies"R"Us and Sephora at Kohl's coverage could help, but the recent 0.9% comp decline and 1.4% drop in visits keep execution risk high. The latest buyback update looks immaterial for that operating debate.
The most relevant announcement alongside the Babies"R"Us rollout is the appointment of Ryan M. Waymire as Chief Merchandising Officer. His remit spans product design, buying, planning and the overall assortment. That role directly touches the key short term catalyst, whether Kohl's can put the right product in front of pressured middle income shoppers often enough to lift trips and baskets.
Waymire’s background at Walmart, Amazon, Target, Wayfair and other retailers gives him experience across fashion, brands and digital first models. For investors, the question is how quickly merchandising decisions feed through to comps and gross margin, and whether new shop in shop partnerships plus proprietary labels can offset ongoing traffic risk and promotional intensity.
What The Babies"R"Us Rollout Implies For Kohl's Forecasts
Analysts currently expect Kohl's revenue to stay broadly flat over the next few years, with profit margins easing from 1.7% today to 1.5% by 2029 despite the wider Babies"R"Us and Sephora shop in shop rollout. Consensus forecasts point to earnings of $227.9 million by 2029, compared with $270.0 million today. This implies an earnings decline of about $42 million even with new brand partnerships and merchandising changes in place. Those assumptions sit behind a model where the stock would trade on a P/E of 13.5x 2029 earnings, versus 8.1x today. They also leave the current analyst price target only slightly below the recent share price, so the onus is on the Babies"R"Us expansion and merchandising reset to justify any shift in that view.
Kohl's narrative projects $15.5b revenue and $227.9 million earnings by 2029. This implies essentially flat yearly revenue trends and an earnings decrease of about $42 million from $270.0 million today.
Uncover why Kohl's fair value indicates an 8% potential upside to its current price that could narrow quickly.
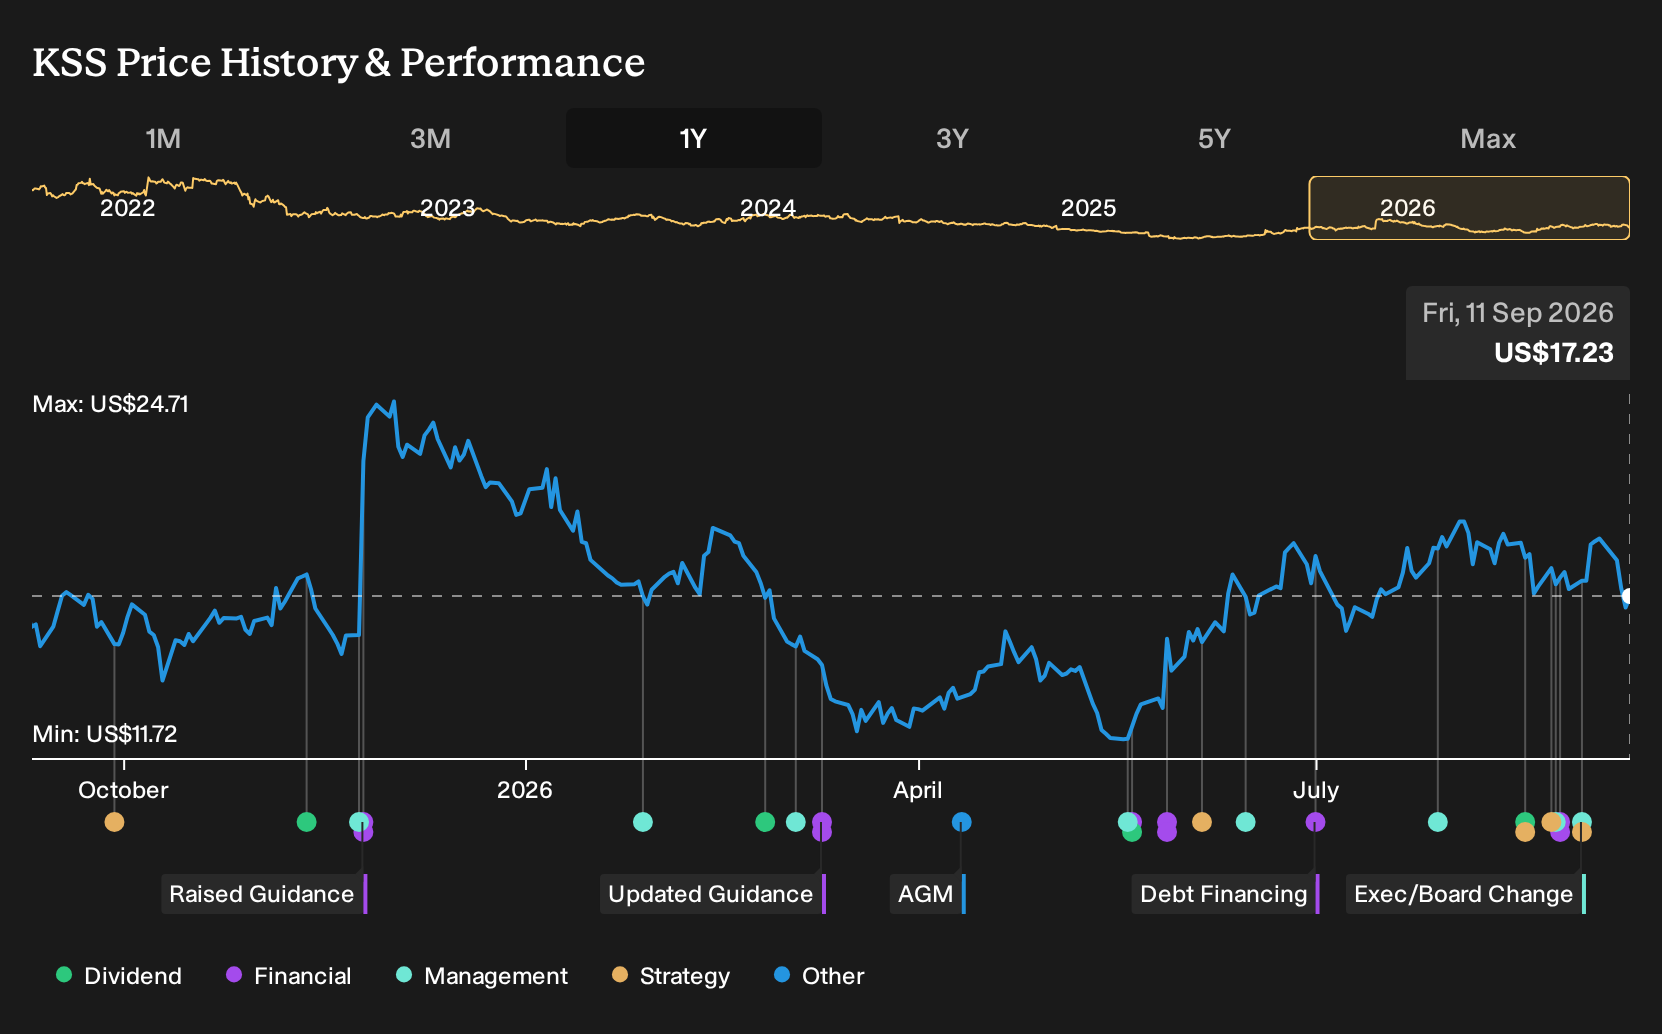
Exploring Other Perspectives
One alternate view puts less weight on Babies"R"Us and Sephora at Kohl's as traffic fixes and instead focuses on erosion in Kohl's core shopper behavior. The most bearish analysts were already penciling in revenue of about $14.8b and earnings near $204.4 million by 2029. That is a meaningfully more cautious starting point, and this latest news could nudge those expectations in either direction once fully reflected.
Explore 3 other Kohl's fair value estimates, including one that suggests it could be worth just $18.69.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Kohl's research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kohl's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kohl's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kohl's?
If the Babies"R"Us rollout has you reassessing Kohl's, it can help to line that thesis up against a wider watchlist of opportunities. The Simply Wall St Screener lets you quickly sort through other businesses with different risk and return profiles so you are not relying on a single retail story.
- If capital protection comes first for you, start with a group of steadier businesses by reviewing 11 resilient stocks with low risk scores.
- If you want resilience on the balance sheet as well as in the income statement, filter for companies with strong financial footing through the list of solid balance sheet and fundamentals (23 results).
- If you are hunting for ideas that the market may be overlooking, cast a wider net across high quality outliers using the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com