


Vishay Stock Draws Focus After New Product Launches Across Auto And Industrial Markets
- Vishay Intertechnology recently rolled out multiple new components, including high power TVS devices, inductive position sensors, RF thin film resistors, and high current common mode chokes for automotive, industrial, telecom, and energy uses.
- The rapid cluster of launches into demanding automotive and industrial electronics points to substantial product development activity during a period of muted revenue growth and ongoing profitability pressure.
- We will now look at how Vishay Intertechnology's concentrated series of automotive and industrial focused product launches could influence its investment narrative.
Vishay Intertechnology Investment Narrative Recap
For Vishay Intertechnology, you need to believe that years of heavy spending on fabs and capacity can translate into healthier margins rather than just bigger fixed costs. In the near term, a key swing factor is whether new, higher value products in automotive and industrial end markets scale fast enough to support that margin recovery. The biggest risk is that cash flow stays weak while capital intensity and manufacturing inefficiencies linger.
The fresh wave of launches in TVS protection, position sensing, RF resistors, and common mode chokes signals that product pipelines are active. However, the impact on the immediate outlook appears incremental rather than transformative. As of September 2026, the core debate still centers on execution at existing facilities, profitability in MOSFETs, and maintaining balance sheet flexibility while earnings are rebuilding.
The XclampR flat clamping TVS series looks most relevant here because it targets the power and protection niches Vishay Intertechnology has highlighted as important in automotive and industrial systems. High pulse power handling, low clamping ratios, and AEC-Q101 qualification help the firm compete for sockets in ADAS, BMS, on board chargers, and DC/DC converters, where design wins can translate into multi year revenue streams.
For investors focused on catalysts, the key question is whether this type of differentiated protection device can scale across smart grid, energy storage, and data center power designs quickly enough to support the margin improvement story analysts are modeling. Execution risk remains if high spec launches do not convert into volume orders fast enough to offset cost pressures, but a series of such products broadens the toolkit the business can take into higher value projects across its core markets.
Vishay Intertechnology's narrative projects US$4.8b revenue and US$556.4m earnings by 2029. This assumes 14.3% yearly revenue growth and a very large earnings increase of about US$554.1m from US$2.3m today.
Uncover why Vishay Intertechnology's fair value indicates a 15% potential upside to its current price that could narrow quickly.
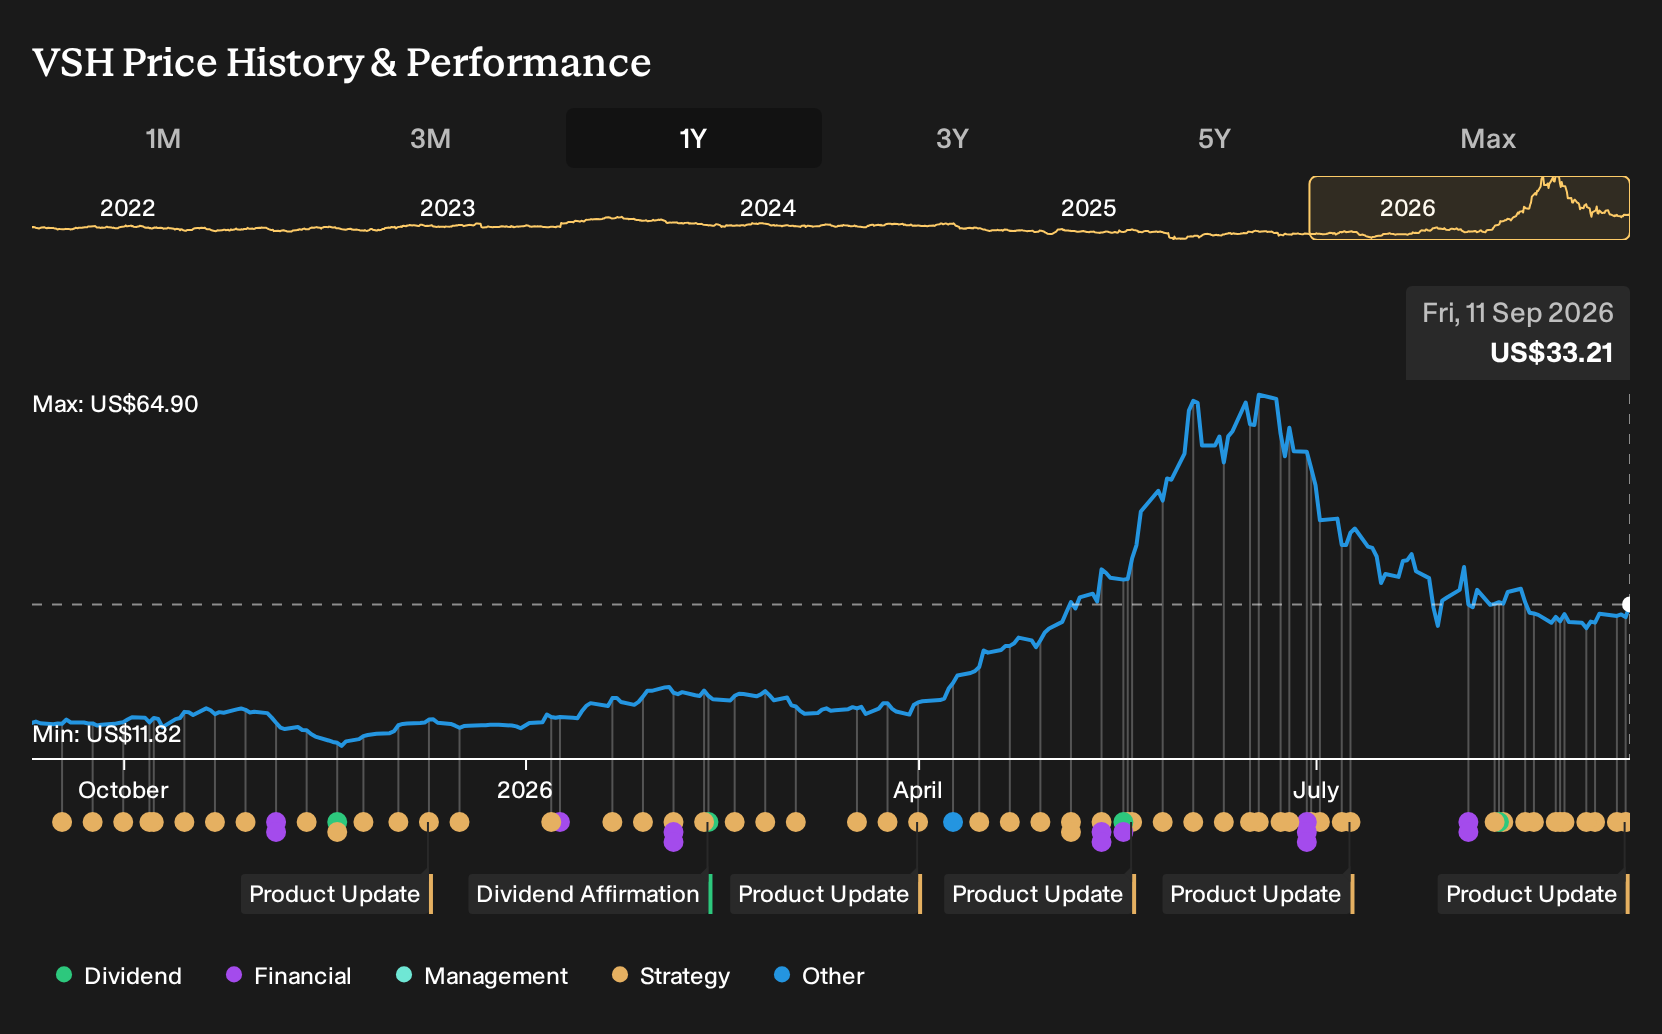
Exploring Other Perspectives
One alternate view zeroes in on underutilization risk. You have bearish analysts arguing that Vishay Intertechnology’s heavy 12 inch fab and regional ramp could leave capacity underused, even though they were already penciling in roughly US$5.2b revenue and US$500.4m earnings for 2029 before this latest product burst. That more cautious storyline might shift as these launches filter into new forecasts.
Explore 2 other Vishay Intertechnology fair value estimates, including one that suggests it could be worth just $38.25.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Vishay Intertechnology research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Vishay Intertechnology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vishay Intertechnology's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vishay Intertechnology?
If this Vishay Intertechnology story has sharpened your thinking, it can help to set it alongside other opportunities with very different risk and return profiles. The Simply Wall St Screener lets you quickly filter for the type of businesses that fit your own checklist rather than someone else's.
- If capital preservation is high on your list, start with resilient companies that historically carry lower risk profiles by reviewing the 11 resilient stocks with low risk scores.
- For readers who care most about balance sheet strength and solid fundamentals, build a shortlist using the list of solid balance sheet and fundamentals (23 results) as your hunting ground.
- If you want to broaden your radar and spot lesser known opportunities with strong underlying metrics, cast a wider net through the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com