


Is Cleveland Cliffs (CLF) A Bargain After Optimism Over Stronger Earnings Growth?
Cleveland-Cliffs (CLF) caught fresh attention after its shares gained 1.94% in the latest session, outpacing major indices as investors focused on projections for stronger upcoming earnings and higher revenue.
For context, Cleveland-Cliffs' 1-day share price gain comes after a mixed stretch. The 7-day share price return is down 3.52% and the 90-day share price return is down 11.52%, while the 1-year total shareholder return of 3.25% signals only modest momentum and leaves longer term holders still facing a 5-year total shareholder return decline of 44.83%.
Compare Cleveland-Cliffs' recent move with a curated group of materials players that screen for value potential using our 32 high quality undervalued stocks.
Cleveland-Cliffs now sits between a brief pop and a much tougher multi year track record. Does that make this latest move an early entry point, or a rally that is better tested against the valuation first?
Most Popular Narrative: 1% Overvalued
Cleveland-Cliffs last closed at $12.06 against a widely followed fair value estimate of $12.00, a tiny premium that leaves the valuation debate wide open.
New investments in higher-margin stainless and specialty steels, buoyed by infrastructure investment, electrification, and clean-energy buildout, will expand Cleveland-Cliffs' addressable markets and support lasting product mix improvement, increasing revenue growth and supporting higher average selling prices.
Want to see how this stainless and specialty push is expected to reshape Cleveland-Cliffs earnings profile? The narrative leans on faster top line expansion, firmer margins, and a future profit multiple that undercuts the wider metals peer group. Curious which specific growth and profitability paths are stitched together to reach that fair value number.
Result: Fair Value of $12.00 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Cleveland-Cliffs story leans heavily on continued U.S. steel tariffs and high automotive exposure. As a result, any policy shift or weaker auto demand could quickly test that narrative.
Find out about the key risks to this Cleveland-Cliffs narrative.
Another View on Cleveland-Cliffs Valuation
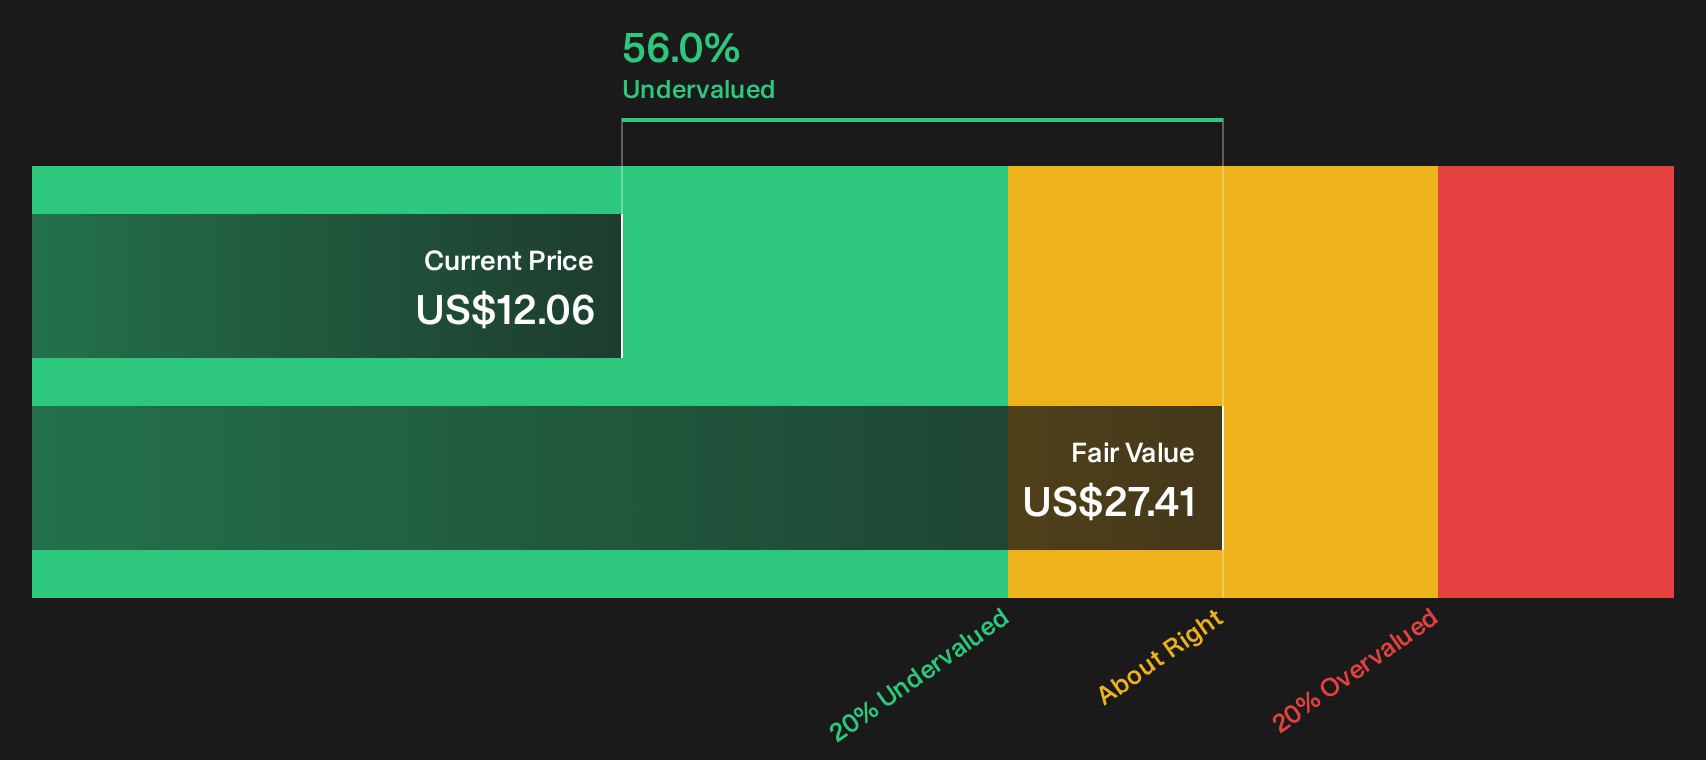
While the consensus narrative pegs Cleveland-Cliffs at roughly fair value around $12.00, the SWS DCF model presents a very different perspective. On that cash flow view, CLF at $12.06 trades well below an estimated value of $27.41, which highlights a wide gap investors need to interpret for themselves.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Cleveland-Cliffs can make the story feel unsettled, so consider reviewing both sides of the thesis promptly. To weigh the upside against the potential downsides in one place, start with the 3 key rewards and 2 important warning signs.
Looking for more Cleveland-Cliffs style investment ideas?
If Cleveland-Cliffs has sharpened your focus on valuation and risk, do not stop with a single ticker when a wider opportunity set sits a few clicks away.
- Target resilience first by scanning companies with strong balance sheets and solid fundamentals through our list of solid balance sheet and fundamentals (23 results).
- Hunt for potential mispriced opportunities by reviewing our 15 high quality undiscovered gems before others catch on.
- Prioritise downside protection by checking companies that score well on stability using the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com