


Did Broader TAVR Coverage Just Shift Edwards Lifesciences Stock Investment Narrative?
- Edwards Lifesciences recently welcomed a finalized Medicare decision from CMS that expands coverage of transcatheter aortic valve replacement to asymptomatic severe aortic stenosis patients, removes prior evidence development requirements for symptomatic cases, and opens the door to evaluating TAVR use in aortic regurgitation.
- The broader CMS coverage framework directly targets patient access and hospital adoption for Edwards Lifesciences' TAVR portfolio. This affects procedure volumes, capacity planning, and how the multidisciplinary heart team model is embedded in everyday structural heart care.
- We will now look at how Edwards Lifesciences' investment narrative is shaped by expanded Medicare coverage for asymptomatic TAVR patients.
Scan how hospitals might recalibrate around Edwards Lifesciences' TAVR momentum, and then compare it with hand-picked peers in structural heart and medtech using the list of solid balance sheet and fundamentals (23 results).
Edwards Lifesciences Investment Narrative Recap
To own Edwards Lifesciences, you need to believe in long term demand for structural heart therapies and the firm’s ability to turn that demand into healthier earnings. The recent CMS move directly supports that belief by broadening access to TAVR, but the near term swing factor still looks like execution on procedure capacity and hospital uptake rather than policy headlines.
The biggest operational risk remains pressure on profitability. Margins are already thinner than a year ago, one off items have distorted recent earnings, and tariffs plus JenaValve dilution are expected to weigh on EPS. Expanded coverage helps volumes, but it does not remove cost inflation, competitive pressure in regions like Japan, or elevated R&D needs.
The most relevant backdrop to this CMS decision is the earlier expectation that expanding TAVR to asymptomatic patients would take time and could arrive later than management and investors hoped. That lag risk has now eased on the coverage side, which ties directly into the multiyear narrative around the Edwards Lifesciences TAVR franchise.
For you as a shareholder, the focus shifts to whether Edwards can translate this broader Medicare access into efficient procedure growth while offsetting tariff headwinds and acquisition dilution. Execution on JenaValve integration, EVOQUE and Sapien M3 rollouts, and expense control will influence how much of the company’s earnings growth actually shows up in reported numbers.
Edwards Lifesciences' current analyst narrative points to revenues of US$8.5b and earnings of US$2.2b by 2029, based on an assumed 9.3% yearly top line expansion and an earnings increase of about US$1.2b from US$979.9m today.
Uncover why Edwards Lifesciences' fair value indicates a 20% potential upside to its current price, which could narrow quickly if sentiment keeps improving.
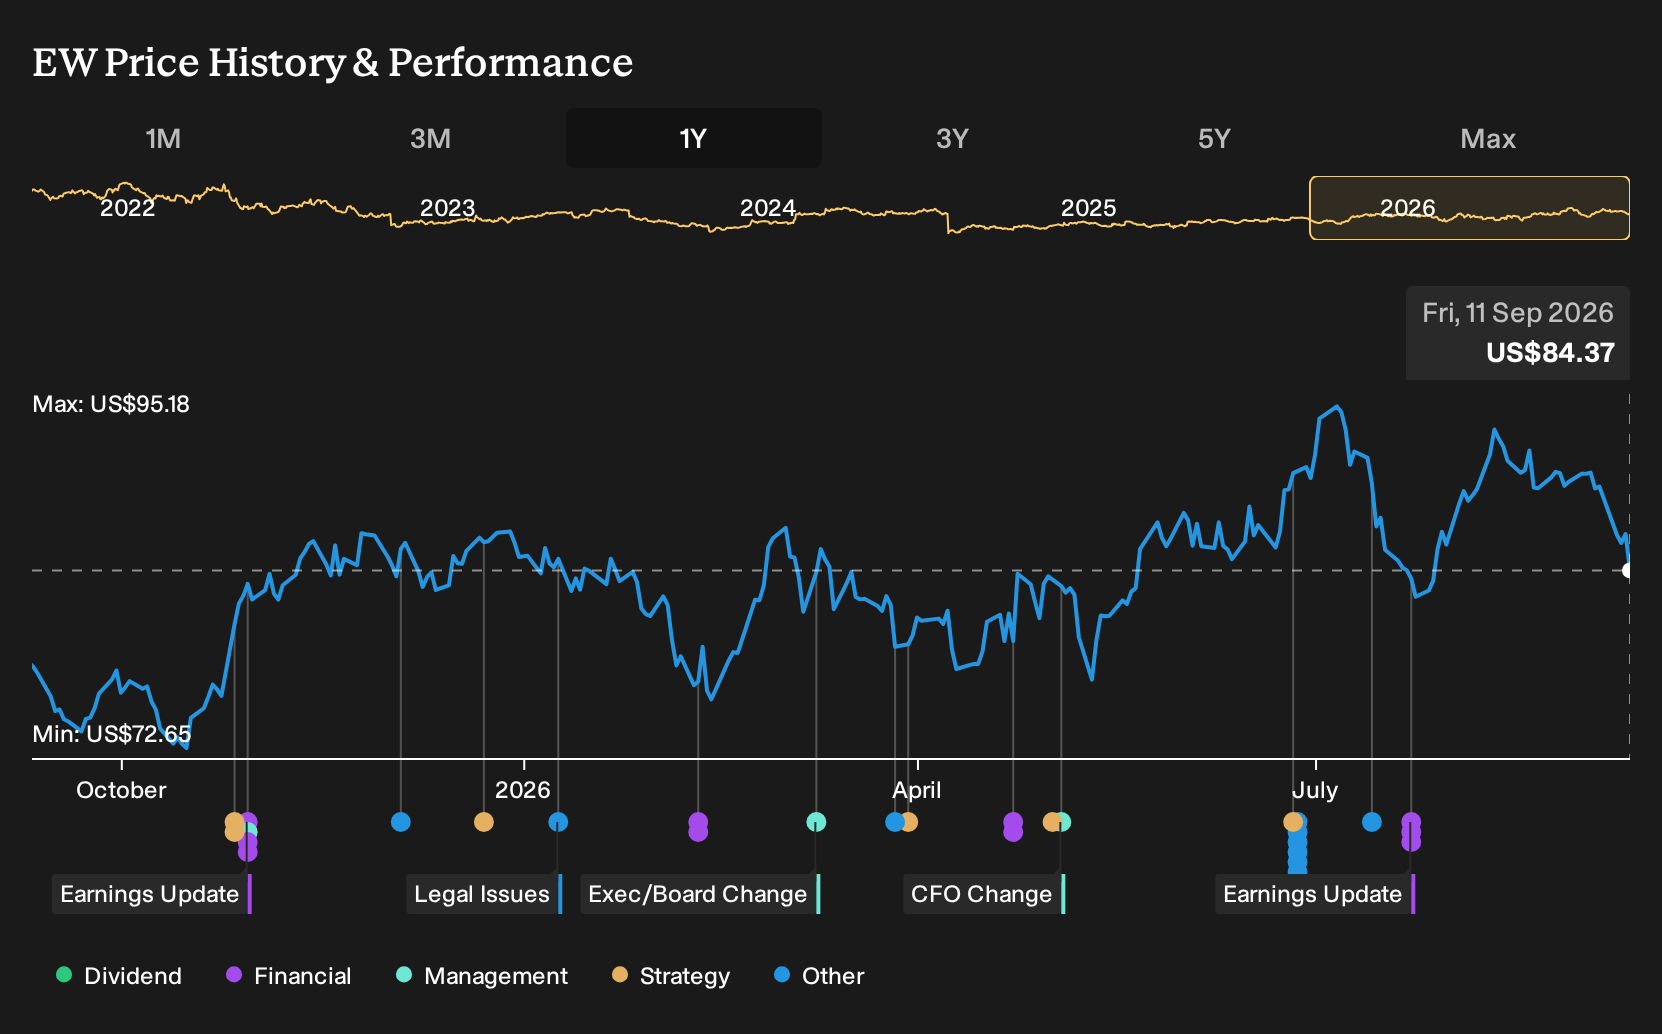
Exploring Other Perspectives
The three fair value estimates for Edwards Lifesciences from the Simply Wall St Community are clustered in a tight band between about US$91.75 and US$100.96, so private investors are not flagging either extreme bargain or froth. Those views predate the CMS TAVR decision, so you should weigh them against fresh policy catalysts, tariff risks, and acquisition dilution. Explore these contrasting viewpoints to see where your own conviction fits.
Explore 2 other Edwards Lifesciences fair value estimates, including one that suggests it could be worth just $91.75.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Edwards Lifesciences research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Edwards Lifesciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Edwards Lifesciences' overall financial health at a glance.
Looking for more investment ideas beyond Edwards Lifesciences?
Once you have a view on Edwards Lifesciences, it can help to widen the lens and compare it with other businesses that fit different risk and return profiles using the Simply Wall St Screener.
- If you want potential growth with a small starting price tag, scan the market for higher quality small names using the 21 elite penny stocks with strong financials.
- If value is your priority, filter for companies that pair strong fundamentals with more modest valuations using the 32 high quality undervalued stocks.
- If capital preservation matters most, look for businesses with stronger balance sheets and steadier profiles through the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com