


How FDA Filing Acceptance Will Impact Alvotech (ALVO) Investors
- Alvotech reported that the FDA accepted its Biologics License Application for AVT80, a proposed interchangeable biosimilar to Entyvio for subcutaneous use, supported by analytical, pharmacokinetic and immunogenicity data and backed by a commercialization partnership with Teva.
- The dual-track development of AVT80 and AVT16 for U.S. and EU review signals Alvotech’s push to build a broad Entyvio biosimilar franchise across both intravenous and subcutaneous formats.
- We will look at how Alvotech's investment narrative is shaped by FDA review of AVT80 as a proposed interchangeable Entyvio biosimilar.
Scan beyond Alvotech and this Entyvio biosimilar story by comparing it with a hand picked 15 high quality undiscovered gems in complex therapeutics and other under the radar opportunities.
Alvotech Investment Narrative Recap
To own Alvotech, you need to believe that a focused biosimilar platform with a deep inflammatory and immunology portfolio can turn pipeline decisions into steadier operating cash flows despite lumpy milestones and pricing pressure. The AVT80 filing fits that view by adding another potential U.S. asset, although it does not change the fact that regulatory timing and partner execution still drive near term revenue swings.
The most important near term catalyst remains regulatory outcomes across the broader portfolio, especially assets already under review. The biggest risk is that approvals slip or launches underperform against a high fixed cost base and meaningful debt. This FDA acceptance improves line of sight on future optionality, but it does not remove funding or pricing risks.
The AVT80 BLA acceptance itself is the key recent development. It builds on February 2026 pharmacokinetic data that met primary endpoints, and regulators have indicated that these data can support clinical similarity for both AVT16 and AVT80. That linkage means investors are effectively watching one core program with two U.S. filing tracks and parallel EU review through the EMA.
This context matters for catalysts because Alvotech is already investing heavily in R&D, acquisitions and vertical integration while still reporting a loss of US$179.59 million and carrying about US$1.14b of debt. Each Entyvio biosimilar decision can influence milestone flows, P/S based valuation arguments and liquidity headroom. However, regulatory scrutiny and partner concentration with Teva keep execution risk front and center.
Alvotech Forecasts Behind The AVT80 Story
Alvotech's current loss of US$80.7 million sits against analyst expectations for earnings of US$242.3 million by 2029, which implies an earnings swing of about US$323 million. Analysts are also modelling 22.2% yearly revenue growth to reach US$1.0 billion in sales by 2029. That profit target provides the forecast earnings base for those same estimates.
Uncover why Alvotech's fair value indicates a 9% potential upside to its current price that could narrow quickly.
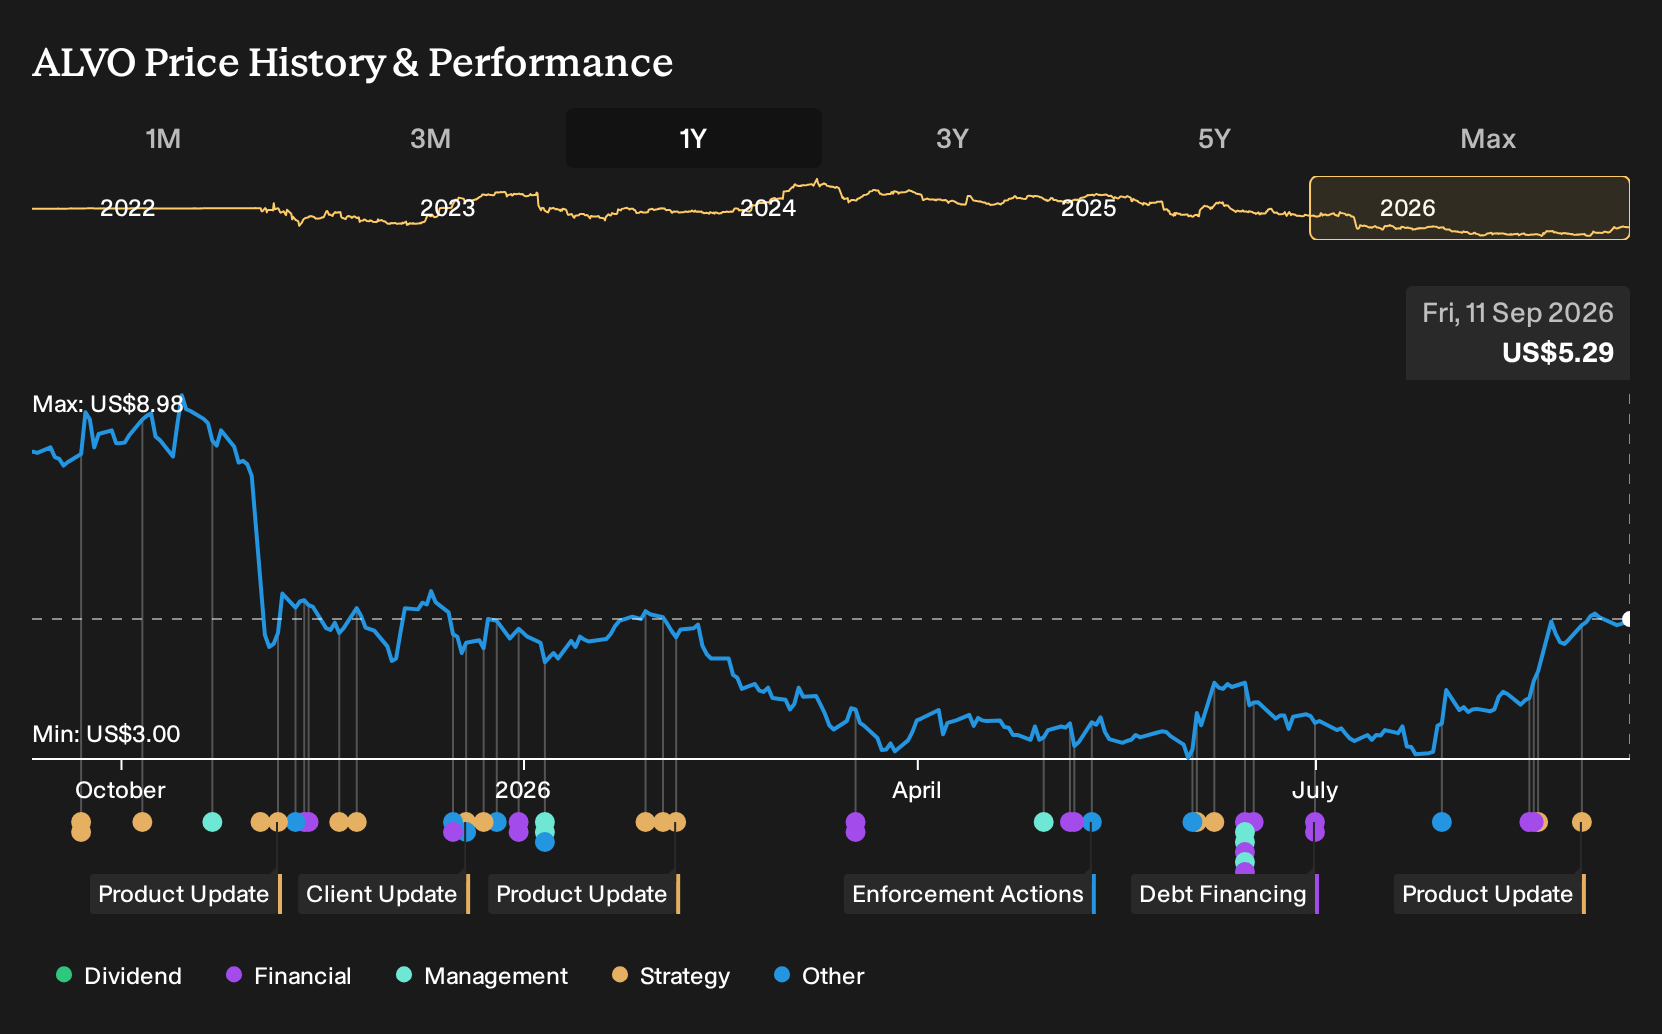
Exploring Other Perspectives
One alternate view focuses on approval risk rather than potential upside from AVT80. The most cautious Alvotech analysts were only penciling in about US$982.5 million of revenue and US$82.7 million of earnings by 2029 before this news. That is a far more hesitant story. Use it as a reminder that opinions can differ sharply and may shift as new information becomes available.
Explore 4 other Alvotech fair value estimates, including one that suggests as much as 24% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Alvotech research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Alvotech. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alvotech's overall financial health at a glance.
Looking For More Alvotech Investment Ideas?
If the Alvotech story has sharpened your thinking about risk, balance sheets and future cash flows, it can help to test that framework on a broader watchlist. The Simply Wall St Screener lets you apply the same questions across hundreds of companies so you can build a shortlist that actually fits your approach.
- For investors who care most about resilient balance sheets, start with a list of solid balance sheet and fundamentals (23 results) that keeps financial strength front and center.
- If capital preservation is your priority, stress test your risk tolerance against a 11 resilient stocks with low risk scores that filters for steadier business profiles.
- When you want to widen the search beyond Alvotech and find underfollowed ideas, a 15 high quality undiscovered gems can surface lesser known companies with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com