


Faraday Copper (TSX:FDY) Could Be 34% Undervalued Following Copper Creek Drill Results
Faraday Copper (TSX:FDY) has put fresh drilling results from its Copper Creek Project in Arizona on the table, with Phase IV work outlining new near-surface copper zones across several target areas.
That drilling update lands at a time when Faraday Copper’s share price has been volatile in the short term, with a 30 day share price return that is down 7.04% and a 90 day share price return that is down 15.85%. Even so, the year to date share price return is 79.44% and the 1 year total shareholder return is 305.51%, pointing to strong longer term momentum from a very low base.
Scan for other copper-focused opportunities with fresh drilling momentum by checking the hand-picked 30 top copper producer stocks alongside Faraday Copper’s latest results.
Faraday Copper now trades at a steep discount to both analyst targets and some intrinsic value estimates after a sharp pullback. Is that pricing in real risk, or is caution overshooting the drilling and project story?
Preferred Price-to-Book Multiple of 10.6x: Is It Justified?
Faraday Copper trades on a steep P/B multiple of 10.6x, while the share price sits at CA$5.15 after a sharp run and recent pullback.
P/B compares the market value of a miner to the book value of its assets. This matters a lot for exploration businesses where hard assets and project rights do most of the talking. For Faraday Copper, that 10.6x level is flagged as expensive relative to both its peer group average of 4.3x and the broader Canadian Metals and Mining sector at 2.7x.
That gap suggests investors are assigning a heavy premium to Faraday Copper’s Copper Creek and Contact Copper projects, despite the firm being unprofitable, reporting a loss of CA$38.49m, and making less than US$1m in revenue. With earnings forecast to decline on average by 38.1% per year over the next 3 years and no revenue expected next year, the valuation relies heavily on future project progress rather than current cash generation.
Compared with an industry where many producers carry lower P/B ratios, paying more than double the sector average for FDY implies a strong belief in future development outcomes that are not yet reflected in its financials. That premium may compress if sentiment toward early stage copper projects cools or expand further if drilling success and de-risking continue.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-book of 10.6x (OVERVALUED)
Still, Faraday Copper carries clear risk if drilling results disappoint or if funding conditions tighten, which could quickly challenge today’s rich P/B premium.
Find out about the key risks to this Faraday Copper narrative.
Another View: Faraday Copper And The DCF Signal
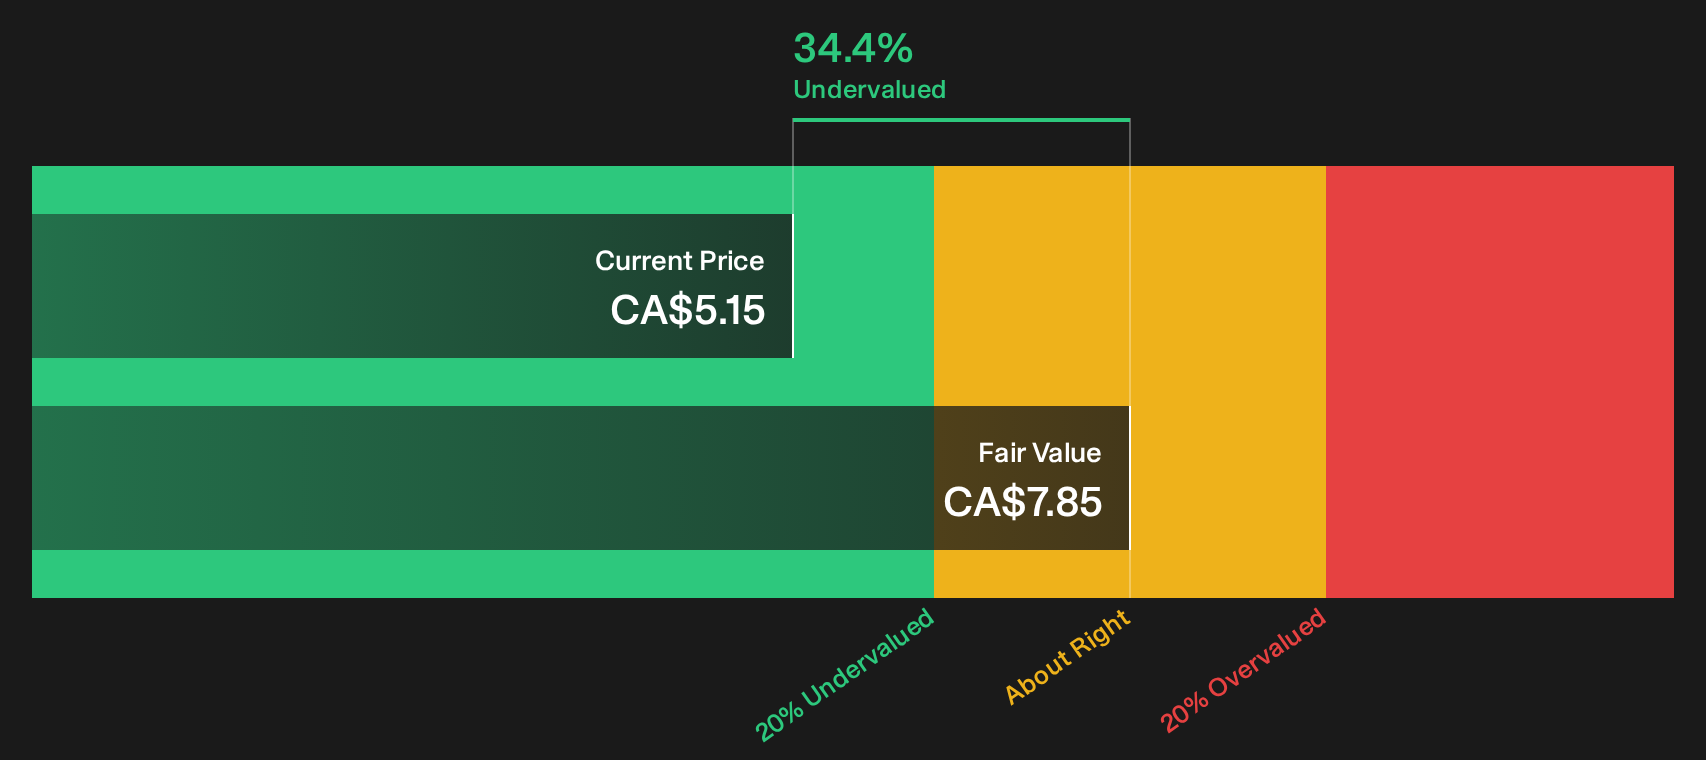
The market is paying a rich P/B multiple for Faraday Copper, yet our DCF model tells a different story. At CA$5.15, FDY trades about 34.4% below an estimated future cash flow value of CA$7.85, which points to a wide gap between current sentiment and modelled project economics.
That type of discount can reflect real concern around funding, permitting, and execution risk, or it can mark a market that is heavily focused on recent share price swings rather than long term copper optionality. The key question is whether you trust the market price or the cash flow math more at this stage.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Faraday Copper for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Faraday Copper story make this a good moment to check the data directly and move quickly to set your own stance. To weigh both the concerns and the potential upside in one place, review the 2 key rewards and 4 important warning signs.
Looking for more Faraday Copper style investment ideas?
If Faraday Copper has your attention, this is the moment to widen your radar and line up a few more ideas before the next move catches you off guard.
- Target efficient pricing opportunities by scanning the market for companies that look mispriced on quality and fundamentals through the 5 high quality undervalued stocks.
- Anchor your portfolio with reliable cash generators by reviewing the 2 dividend fortresses that focus on durable payouts and higher yields.
- Reduce portfolio stress by concentrating on resilient businesses through the 1 resilient stocks with low risk scores that screen for stronger balance sheets and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com