


AI Regulation Could Reshape Palo Alto Networks Stock And US Cloud Leaders
AI regulation is moving from talk to action, and that shift is starting to matter for the biggest U.S. cloud and data center platforms as much as for pure AI developers. New guardrails could raise costs and reshape who keeps gaining from the AI boom, which is exactly where opportunity and risk often get mispriced. This article breaks down three large cap U.S. AI and cloud infrastructure stocks most exposed to the latest policy push.
The three stocks covered next are a small slice of what this theme turns up, since the full screen surfaced 12 more large cap AI and cloud infrastructure players with equally compelling business stories that are not included below. To see the whole field and quickly identify which platforms best fit your thesis, head straight to the Large-Cap U.S. AI and Cloud Infrastructure Leaders screener.
Palo Alto Networks (PANW)
Palo Alto Networks is the clearest pure cybersecurity play in this AI and cloud infrastructure group, supplying the controls hyperscale platforms and large enterprises need as regulators push for tighter monitoring, threat detection and policy enforcement across complex digital stacks.
Palo Alto Networks focuses on securing cloud and AI environments, generating about US$11.5b from security software and services, and carries a market value around US$270.5b.
Accelerated enterprise adoption of AI and cloud technologies is expanding the attack surface, supporting demand for comprehensive cybersecurity solutions.
The real test for Palo Alto Networks will come from how one unresolved cost pressure shapes future profitability relative to that demand backdrop.
That cost pressure is exactly what the full narrative for Palo Alto Networks unpacks, showing where regulation, pricing power and AI security demand could be quietly decoupling for Palo Alto Networks.

Snowflake (SNOW)
Snowflake is one of the clearest fits for this AI and cloud infrastructure screen, providing the data backbone enterprises use to run and govern AI workloads while regulators push for tighter control over how sensitive information is stored and analysed.
Snowflake runs a cloud-based AI Data Cloud that helps organisations consolidate data and build AI applications, generating about US$5.4b from internet software and services, and carries a market value near US$116b.
Snowflake just made a significant move by partnering with Anthropic to bring Claude AI models directly into their platform. This isn't just another tech partnership. It is a strategic play that lets businesses analyse both structured and unstructured data using AI while keeping everything secure within their existing systems.
What really matters next is how one hard to see cost and pricing balance shapes the payoff from all that AI driven demand.
That pricing tension is exactly what the full narrative for Snowflake unpacks for Snowflake, highlighting where accelerating AI demand could be masking both risk and upside potential.

Seagate Technology Holdings (STX)
Seagate Technology Holdings is the pure storage pick in this AI and cloud infrastructure screen, supplying the high capacity drives that keep hyperscale data centers and AI workloads running while regulators push for tougher rules on retention, audit trails and long term data governance.
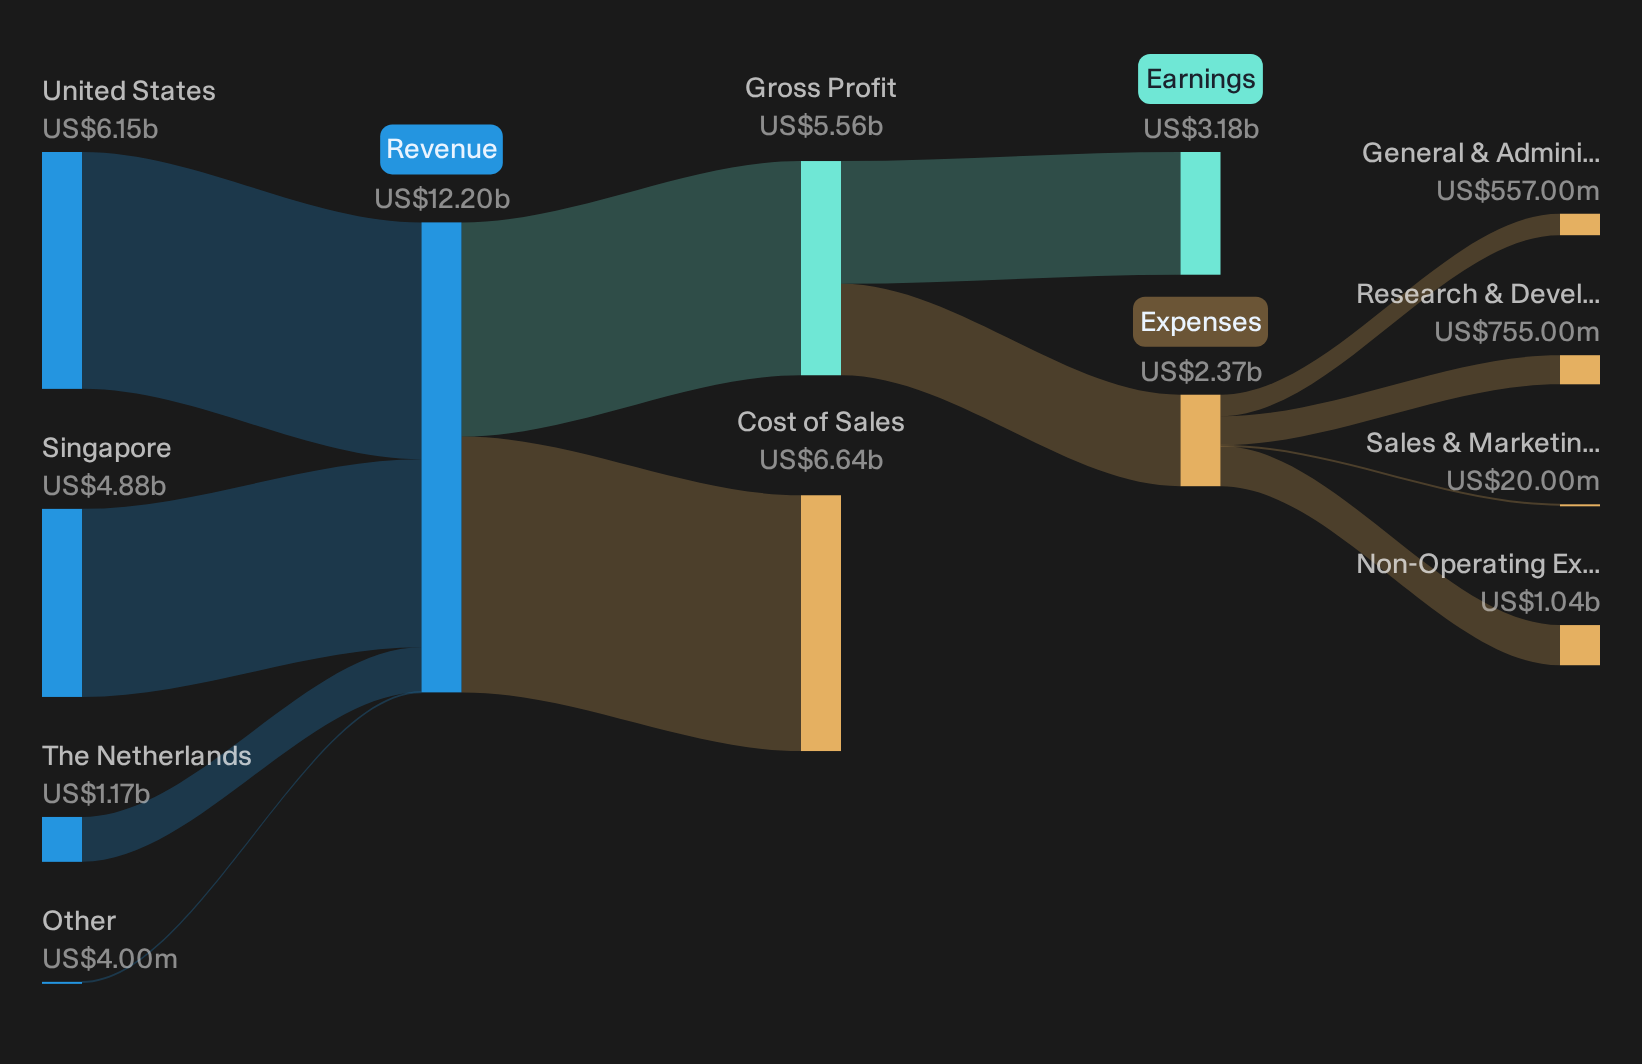
Seagate generates about US$12.2b from manufacturing and distributing storage solutions across hard drives, SSDs and data systems, supporting a roughly US$188.8b market value.
For investors trying to track who really benefits from AI regulation turning into storage demand, Seagate offers a way to focus on the physical layer, where every new model, log file and AI video ultimately has to live.
The growing demand for mass capacity storage driven by the cloud CapEx investment cycle and data center build-outs for AI transformation is expected to affect Seagate's revenue streams.
What happens to that potential will depend on how one quiet constraint shapes pricing power, margin durability and the results associated with AI data growth.
That quiet constraint is exactly what the full narrative for Seagate Technology Holdings lays bare, showing where accelerating AI data demand could be masking Seagate's next leg of opportunity and risk.
Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. By the time a breakout story hits headlines, early momentum can already be flying. Scan these under the radar lists while it matters and get in early.
- Target dependable income by zeroing in on companies in the 6 dividend fortresses curated for investors who want yield that holds up when sentiment drops.
- Hunt for mispriced quality with the 32 high quality undervalued stocks before others catch what strong cash flows and cleaner balance sheets can mean for a potential breakout.
- Track the next wave of automation by scanning the 38 robotics and automation stocks where select businesses are building the hardware and software backbone for real world productivity gains.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com