


e.l.f. Beauty (ELF) Expands Naturium At Sephora, Is The Upside Already Priced In?
What Naturium’s Sephora rollout means for e.l.f. Beauty
Naturium’s expansion with Sephora across Canada and Mexico puts e.l.f. Beauty (ELF) in front of more skincare shoppers in two sizable North American markets. For investors, the move raises fresh questions about international scale and brand reach.
The Naturium news lands while e.l.f. Beauty’s share price has shown strong momentum, with a 90 day share price return of 51.45% and a year-to-date share price gain of 24.55%, even though the 1-year total shareholder return declined 28.33%.
Compare e.l.f. Beauty’s momentum with a curated group of resilient businesses using the 11 resilient stocks with low risk scores to see which stocks pair steady risk profiles with potential upside.
e.l.f. Beauty’s recent share swing and Naturium’s Sephora push both sit in front of you. Are you watching a business expanding its reach, or a moodier reset in sentiment that changes what the current valuation really reflects?
Most Popular Narrative: 23% Overvalued
Compared with the last close of $96.91, the most followed narrative for e.l.f. Beauty implies a lower fair value, which puts extra focus on the assumptions behind that gap.
The analysts have a consensus price target of $78.81 for e.l.f. Beauty based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $100.0, and the most bearish reporting a price target of just $50.0.
Want to see what has to go right for e.l.f. Beauty at this price? The narrative leans on strong earnings compounding, richer margins and a premium multiple to today. Curious which mix of growth, profitability and discounting gets you from here to that fair value number.
Result: Fair Value of $78.81 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, tariff exposure on China sourcing and any slowdown in core e.l.f. Cosmetics volumes could challenge the bullish narrative and reset how investors frame e.l.f. Beauty.
Find out about the key risks to this e.l.f. Beauty narrative.
Another View: SWS DCF fair value for e.l.f. Beauty
While analyst targets imply e.l.f. Beauty is 23% above a fair value of $78.81, the SWS DCF model points in a different direction. At a last close of $96.91, the stock trades about 7.5% below an estimated future cash flow value of $104.77. Which story do you trust more: earnings multiples or long term cash generation?
Look into how the SWS DCF model arrives at its fair value.
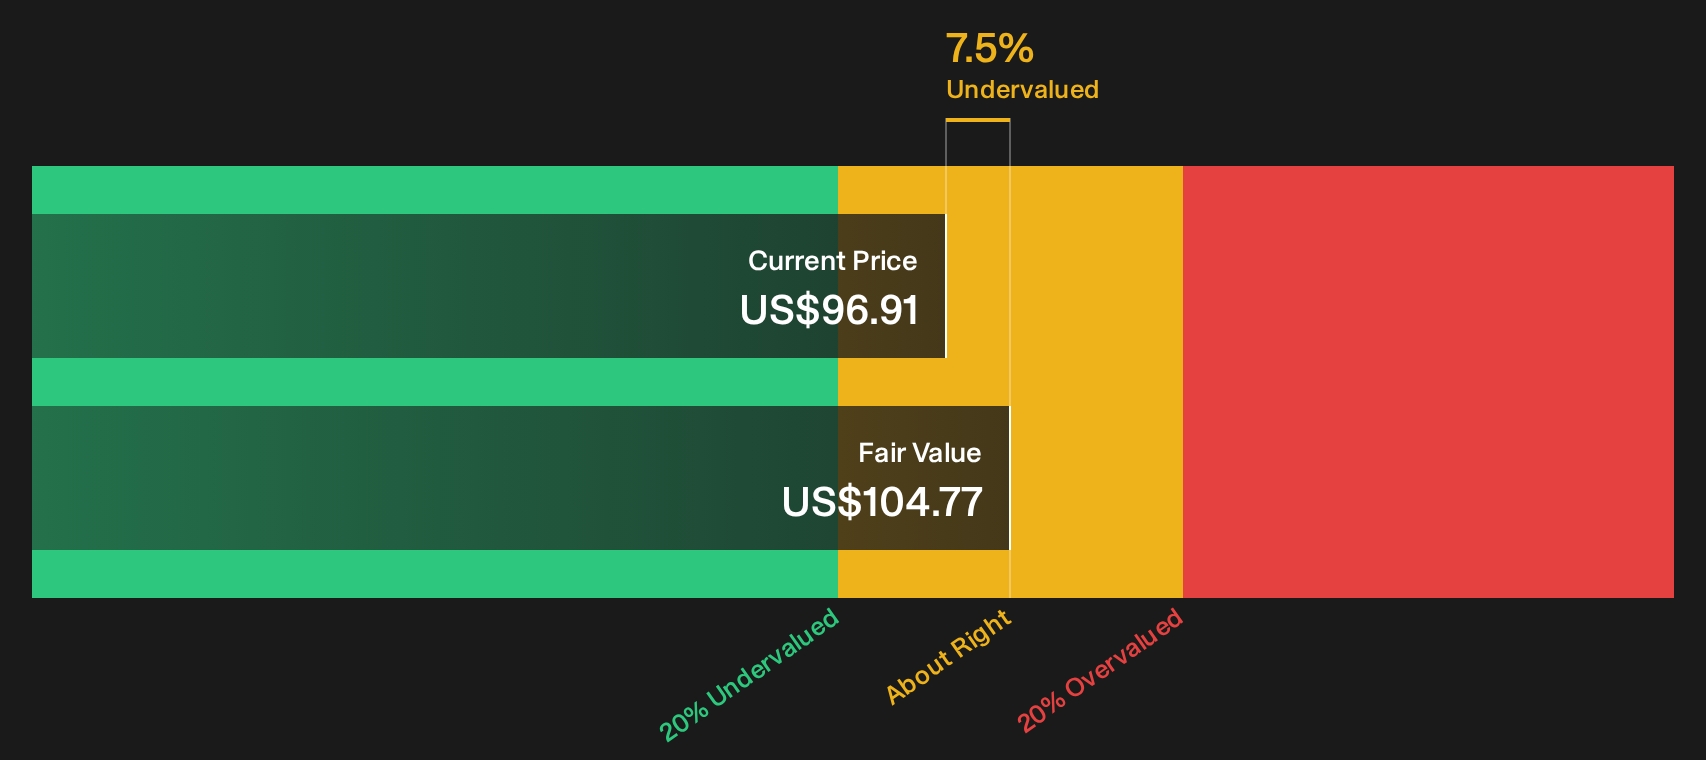
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out e.l.f. Beauty for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on e.l.f. Beauty so far, right, with upbeat share moves but split valuation signals. Act while the data is fresh and weigh both sides for yourself by reviewing the 2 key rewards and 3 important warning signs.
Looking for more e.l.f. Beauty sized opportunities?
If e.l.f. Beauty has your attention, do not stop with a single ticker. Broaden your watchlist now and keep fresher ideas on your radar.
- Target resilient compounding potential by scanning a 32 high quality undervalued stocks that pairs quality fundamentals with prices that sit below many investors’ radar.
- Prioritize stability and staying power through a list of solid balance sheet and fundamentals (23 results) that focuses on companies with stronger financial footing and cleaner leverage profiles.
- Hunt for underfollowed potential by checking a 15 high quality undiscovered gems that highlights stocks with solid fundamentals but limited market attention so far.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com