


Resonac Holdings (TSE:4004) Could Be 49% Undervalued Following Its Recent Pullback
Resonac Holdings (TSE:4004) drew investor attention after its recent share performance, with the stock down 11% over the past month and 16% over the past 3 months, despite positive annual revenue and net income growth.
Despite the recent drop, Resonac Holdings still shows powerful longer-term momentum, with the share price delivering a 111.75% year-to-date return and a 1-year total shareholder return of 223.33%. This suggests the latest pullback reflects cooling sentiment after a very strong run.
Scan how Resonac Holdings compares with other strong performers by jumping into a curated list of 17 high quality undervalued stocks that combine momentum with solid fundamentals.
Resonac Holdings has slipped from its highs, yet the share price still sits well below several fair value estimates. Is this pullback enough to close that gap, or is it just the start of the valuation debate?
Most Popular Narrative: 48.9% Undervalued
Resonac Holdings last closed at ¥14,295, while the most widely followed valuation narrative anchors on a fair value of ¥28,000, framing the recent slide as a move within a much larger pricing gap.
The assumed bullish price target for Resonac Holdings is ¥28000.0, which represents up to two standard deviations above the consensus price target of ¥20891.67. This valuation is based on what can be assumed as the expectations of Resonac Holdings's future earnings growth, profit margins and other risk factors from analysts on the bullish end of the spectrum.
Want to see how analysts bridge that gap between price and fair value? The narrative leans on faster earnings expansion, fatter margins, and a premium earnings multiple that you rarely see in a traditional chemicals group. The full story is in how those moving parts lock together over time, not in a single target number.
Result: Fair Value of ¥28,000 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the bullish Resonac Holdings story leans heavily on Semiconductor and Electronic Materials, which are expected to offset a weaker Chemicals segment, as well as on restructuring moves that may disrupt cash flow if execution slips.
Find out about the key risks to this Resonac Holdings narrative.
Another View on Resonac Holdings: High Multiple, Different Message
While the bullish narrative frames Resonac Holdings as 48.9% undervalued on a fair value of ¥28,000, the current P/E of 46.9x tells a different story. That ratio is more than double the JP Chemicals industry average of 12.2x and well above the fair ratio of 28.9x. This points to a valuation rich with execution risk if expectations slip.
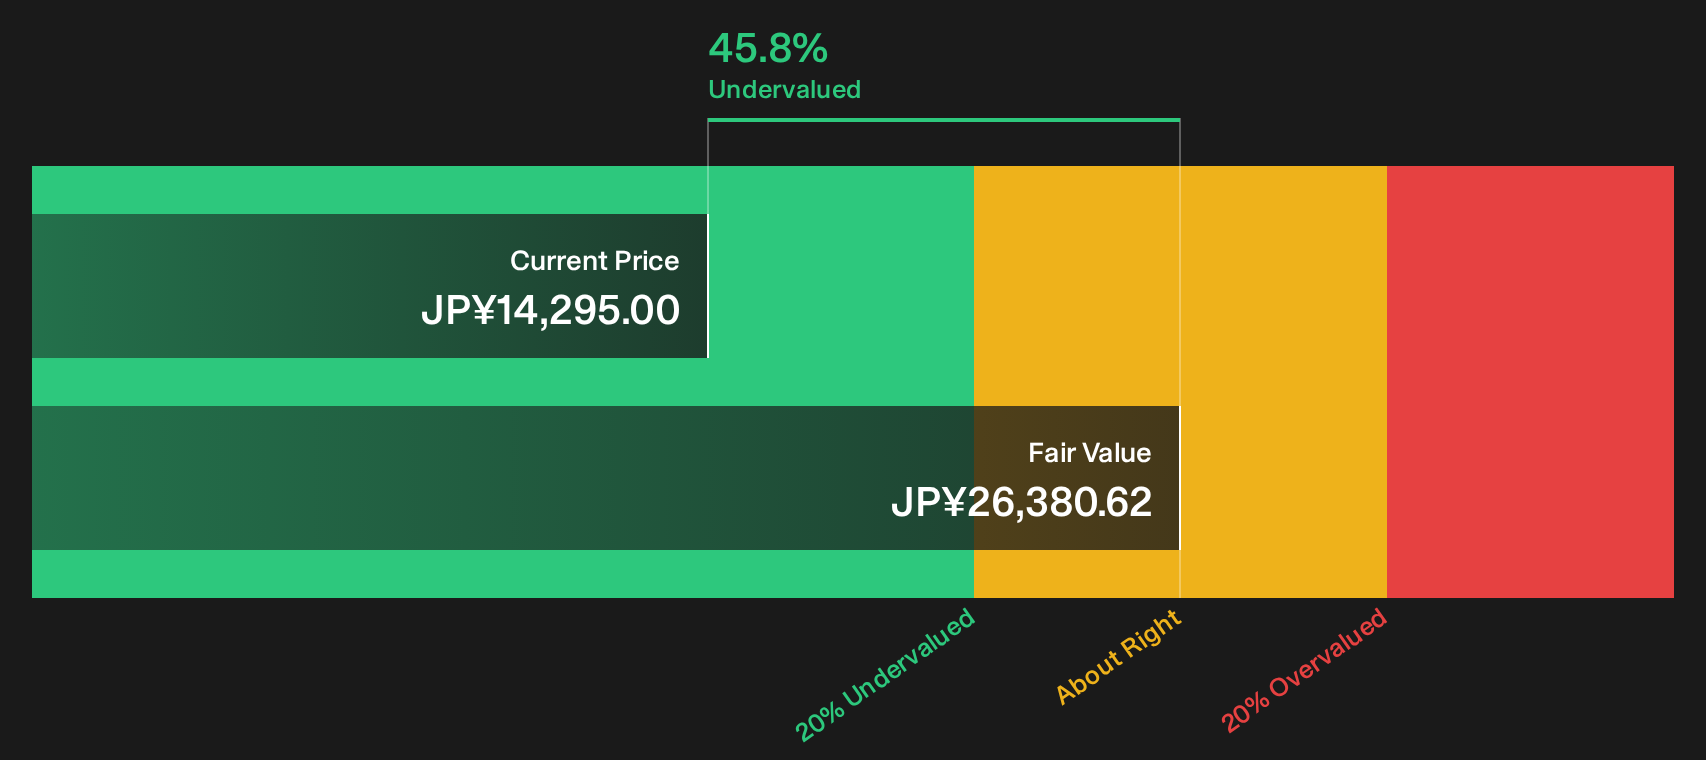
Our DCF work paints a separate picture again, with Resonac Holdings trading below an estimated future cash flow value of ¥26,380.62, according to the SWS DCF model, which still treats the shares as undervalued. Look into how the SWS DCF model arrives at its fair value.
Next Steps
With sentiment clearly split on Resonac Holdings, it helps to move quickly from headline takes to the underlying numbers and drivers yourself. To weigh the balance of concerns against the upside case in one place, start with the 3 key rewards and 2 important warning signs.
Looking for more Resonac Holdings style investment ideas?
If Resonac Holdings has sharpened your focus, do not stop here. The best opportunities often sit just beyond the first stock on your radar.
- Target income resilience by scanning companies that behave like income anchors through the 19 dividend fortresses.
- Spot resilient balance sheets early by filtering for businesses with robust finances using the list of solid balance sheet and fundamentals (19 results).
- Hunt for future standouts before the crowd notices by running a focused search through 73 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com