


Should Building Products Rally Require Action From AAON Stock Investors?
- AAON recently moved in line with a sector-wide rally in building products companies, reflecting investor interest in construction and infrastructure related HVAC exposure.
- The sector move highlights how AAON’s fundamentals in energy efficient and data center focused HVAC solutions tie directly into broader construction demand expectations.
- We will now look at how this sector driven optimism around construction demand could influence AAON’s longer term investment narrative.
Scan beyond AAON and size up other construction linked HVAC and building product opportunities with the curated 39 power grid technology and infrastructure stocks that is shaping the next leg of infrastructure spending.
AAON Investment Narrative Recap
To own AAON, you need to believe the business can turn current operational growing pains into higher efficiency and better margins over time. In the short term, the key swing factor is execution on ERP rollouts and new capacity in places like Memphis and BasX. The recent sector rally does not change that core operational job.
The biggest near term risk is still disruption from those system implementations and ramp up projects, which are already linked to pressure on gross margins and cash flow. Sector optimism around construction and infrastructure does not remove that execution risk. It simply provides AAON with more room to prove the operating story.
Recent commentary around AAON has focused heavily on ERP progress, production efficiency and the BasX expansion. All of these tie directly into the latest move in construction linked stocks. Investors participating in the sector rotation are effectively betting that companies such as AAON can translate higher demand into cleaner throughput and better cost control.
Those same updates also highlight the pressure points. Cash needs for new facilities, higher SG&A from training and start up inefficiencies and exposure to data center cycles leave little room for missteps. The construction rally is beneficial only if AAON keeps backlog quality high and converts it into profitable, on time shipments.
AAON Consensus Assumptions In Context
Analysts currently pin AAON to a fairly ambitious growth path that leans directly into the same construction and infrastructure themes pulling the sector higher. Their base case builds around rapid top line expansion, thicker margins and a bigger earnings pool by the end of the decade. For anyone tracking the stock, the numbers behind that story matter just as much as the sector narrative.
The consensus framework starts with revenue. Forecasts point to AAON growing sales by 20.2% a year over the next three years, supported by higher margin expectations as the business scales newer facilities and works through ERP friction. Profitability today is tied to an 8.2% margin profile, with analysts sketching out a path toward 14.8% in roughly three years if execution holds.
Earnings sit at US$159.3 million today. The same group of estimates projects profit climbing to US$496.3 million by around 2029. That is a jump of about US$337 million in absolute terms. This implies the market is being asked to accept a much larger earnings base for AAON in just a few years while ERP projects, Memphis and BasX all settle into steadier production routines.
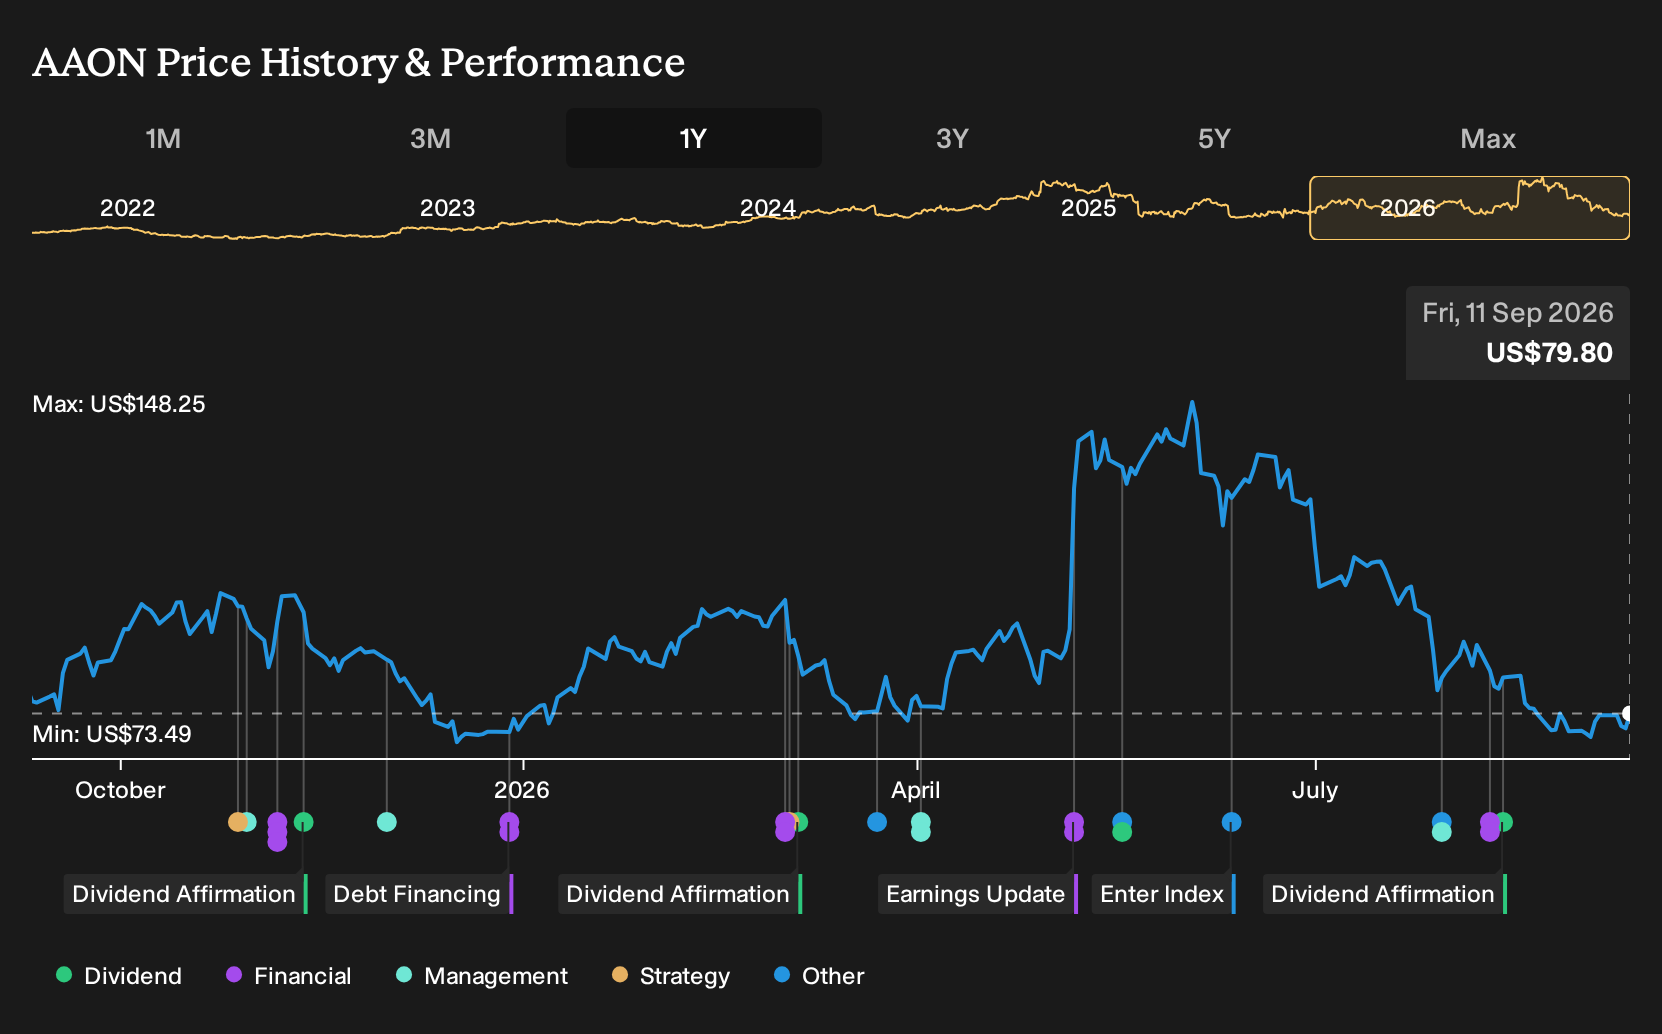
On the valuation side, the consensus view assumes AAON could be generating about US$3.4b of revenue and US$496.3 million of earnings by 2029. The scenario also uses a P/E of 31.5x on those future earnings and a discount rate of roughly 8.6%. All of that underpins a collective price target of US$143.00 compared with a current share price of US$85.78 and an implied 40% gap that investors have to judge against their own expectations for construction related HVAC demand and execution risk.
AAON's analyst narrative points to about US$3.4b in revenue and US$496.3 million in earnings by 2029, tied to an assumed 20.2% yearly revenue growth rate and an earnings increase of roughly US$337 million from US$159.3 million today.
Discover why AAON's fair value indicates a 79% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view leans hard into AAON's data center cooling exposure as the real swing factor. The most optimistic analysts were already penciling in revenue of about US$2.9b and earnings of US$346.8 million by 2029 before this sector rally. You can treat today’s construction driven move as a fresh reason to compare those bullish assumptions with your own expectations.
Explore 3 other AAON fair value estimates, including one that suggests potential upside of as much as 180% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AAON research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AAON. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AAON's overall financial health at a glance.
Looking for more AAON style investment ideas?
If the AAON story has sharpened your thinking about construction linked HVAC and infrastructure exposure, it can help to widen the lens and compare it with other companies that fit different risk and return profiles. The Simply Wall St Screener lets you do that quickly by filtering for balance sheet strength, income reliability, or under followed potential.
- If capital preservation is near the top of your list, start with companies that combine resilient financials with measured risk using the 11 resilient stocks with low risk scores.
- For investors who prefer income on top of price moves, weigh up stocks that pair robust payouts with higher yields through the 6 dividend fortresses.
- If you want ideas that are less crowded by mainstream attention, scan for under researched opportunities using the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com