


Moody's (MCO) Stock Looks Above Fair Value Despite Strong 43% Returns
Moody's has delivered a strong 42.6% gain over the past three years, yet the current valuation checks point to a stock that trades at a premium to its own intrinsic value estimate and to market-based multiples. That mix leaves investors weighing solid long term returns against signals that Moody's may already be pricing in a lot of good news.
- The 42.6% three year return highlights how well Moody's has rewarded patient shareholders, which now raises the bar for future upside at the current valuation.
- Ongoing demand for credit ratings and risk analytics can support Moody's cash generation, while any hit to issuance volumes or client budgets may pressure those cash flows and make the current premium harder to justify.
- With a low value score of 1 out of 6 checks, Moody's does not screen as a clear bargain on the broader valuation gauges.
The issue now is whether Moody's current share price leaves enough room between market expectations and the intrinsic value estimate suggested by the Excess Returns model.
Spot opportunities beyond Moody's by scanning a curated list of companies that pair strong balance sheets with valuation support using our solid balance sheet and fundamentals stocks screener (23 results).Does Moody's Look Pricey on Excess Returns?
The Excess Returns model looks at how much profit Moody's can generate over its equity cost and then capitalizes those surplus returns into an intrinsic value per share. It treats the business as a machine that earns more than it needs to satisfy its shareholders' required return.
For Moody's, the inputs signal a very profitable franchise. Book value sits at $17.47 per share, while stable EPS is estimated at $19.48 per share, based on future return on equity forecasts from 8 analysts. With a cost of equity of $1.84 per share, the model implies an excess return of $17.64 per share, paired with an average return on equity of 85.01% and a stable book value projection of $22.91 per share from 5 analyst estimates.
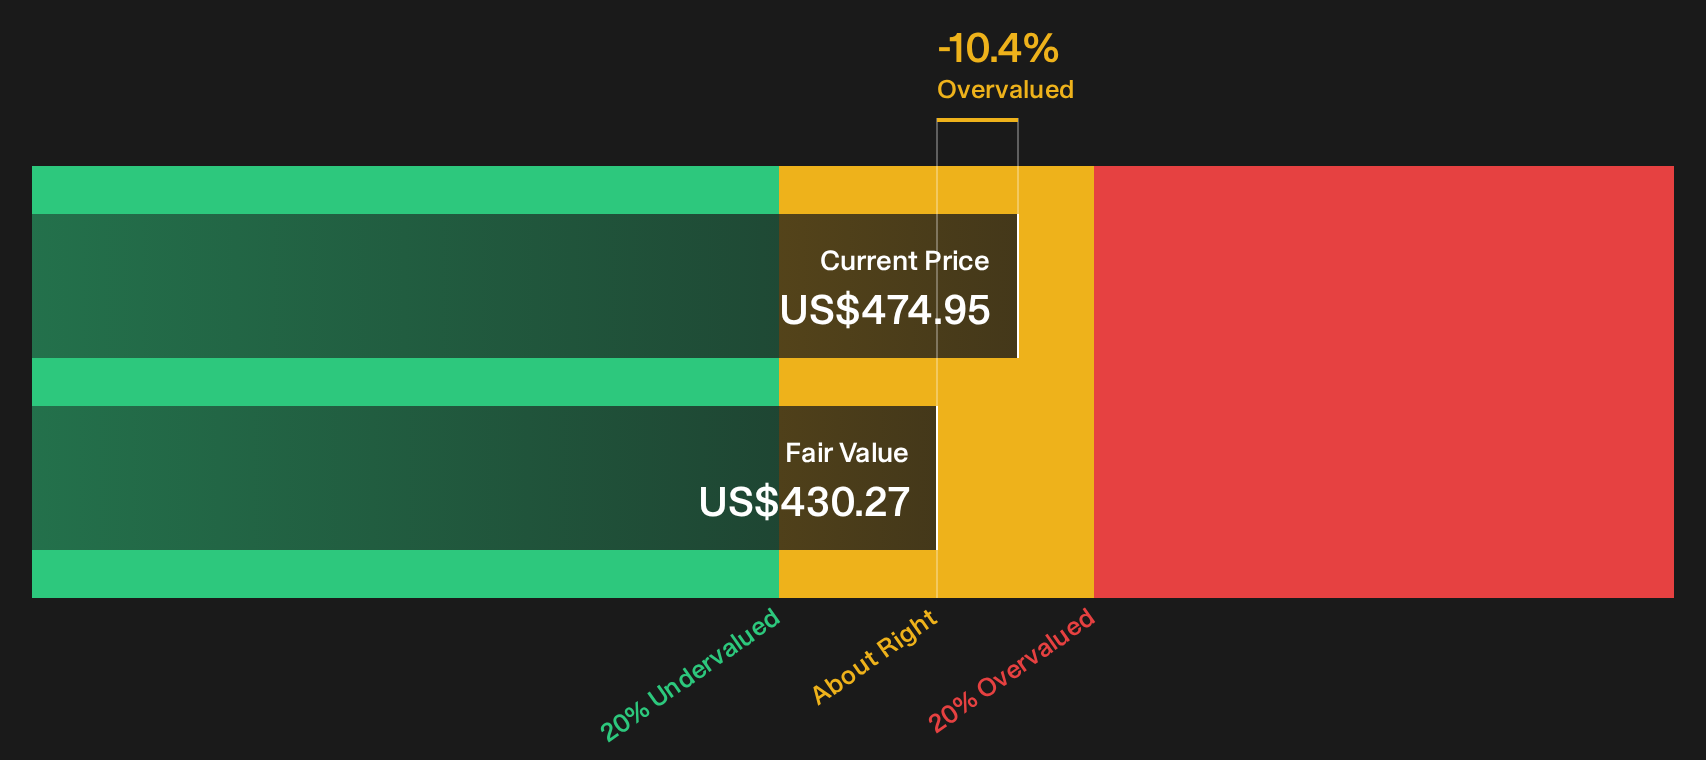
Feeding these numbers into the Excess Returns framework gives an intrinsic value of $430 per share. Compared with the current share price, this implies Moody's is trading at roughly a 10.4% premium to that estimate, so the stock screens as overvalued on this method.
On these Excess Returns assumptions, Moody's stock looks overvalued relative to its calculated intrinsic value.
Our Excess Returns analysis suggests Moody's may be overvalued by 10.4%. Discover 32 high quality undervalued stocks or create your own screener to find better value opportunities.
Is Moody's Getting Expensive on Earnings?
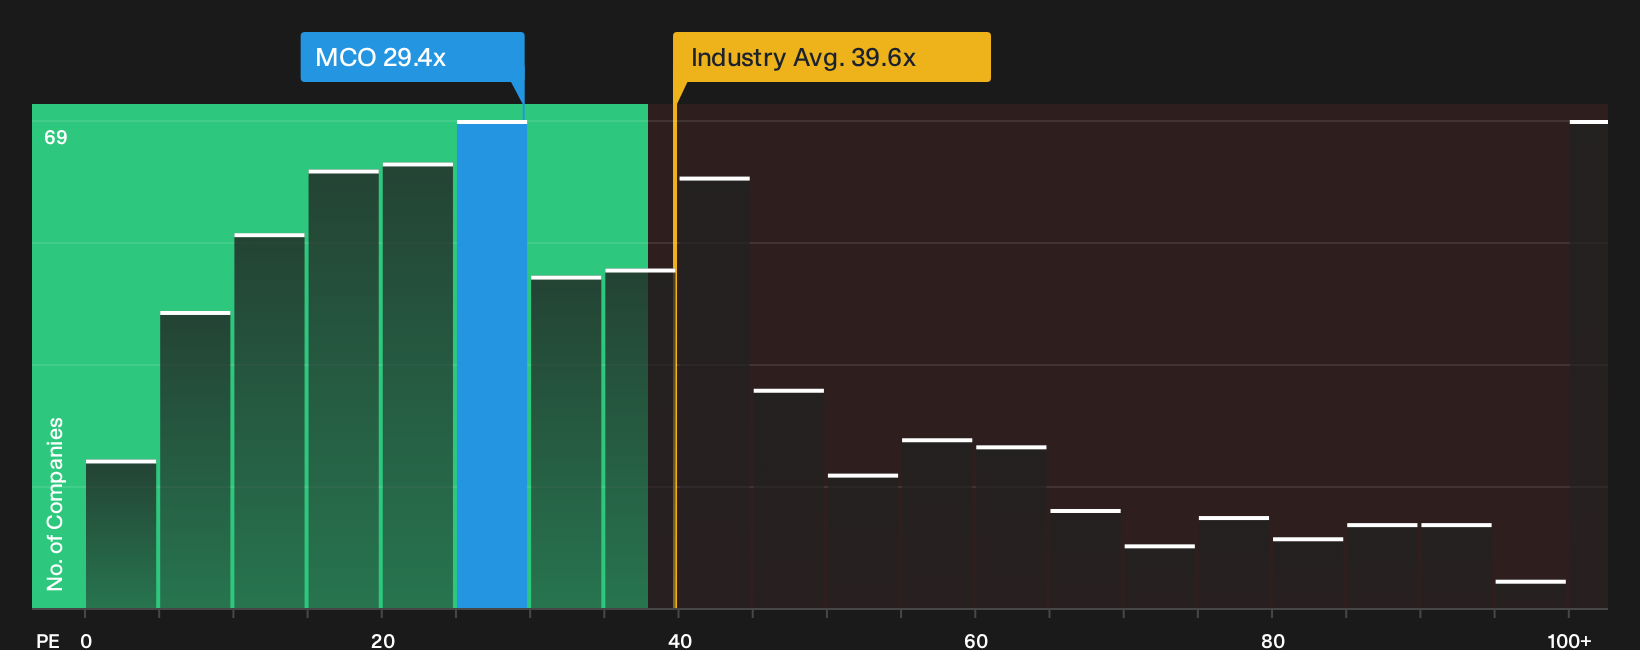
The P/E ratio suits Moody's because earnings sit at the center of how investors usually judge mature, highly cash generative financial businesses. On this metric, the stock trades on about 29.4x earnings, compared with a Capital Markets industry average of 39.6x and a peer group average of 23.9x. That mix shows Moody's carries a premium to closer peers on earnings, even though the broader sector includes some much richer valuations.
The fair P/E multiple implied by the model is 17.2x, which is materially lower than where Moody's actually trades. That gap suggests investors are paying a higher price for each dollar of profit than the company specific risk and return profile would indicate on this framework. For anyone using earnings based yardsticks, the shares screen as expensive relative to the tailored fair multiple.
On the P/E test, Moody's stock appears overvalued compared with the earnings multiple the model identifies as reasonable.
See what the numbers say about this price — find out in our valuation breakdown.
The Moody's Narrative: What Would Justify Today's Price?
Moody's Narratives on Simply Wall St are designed to connect this valuation puzzle to concrete expectations by spelling out which paths for revenue growth, profit margins and earnings would need to play out for the current share price to look meaningfully higher or lower. Rather than stopping at a single output from a ratio or model, the narratives lay out the future that figure relies on so you can watch how reality lines up over time on the Community page.
Community views on Moody's split sharply between those who see a wide moat on sale and those who think quality already comes at a full price.
Bull case: 14% undervalued
"Moody's has established itself as one of the global standards in credit ratings, a status reflected in its wide economic moat and consequently stellar operating margins in the 45 to 50% range…"
Read the full Bull Case to see why Moody's could be undervalued
Bear case: roughly fairly valued
"At current valuations, Moody’s is not a bargain-bin stock, but high-quality compounding businesses rarely are…"
Read the full Bear Case to see why Moody's could be overvalued
Do you think there's more to the story for Moody's? Head over to our Community to see what others are saying!
The Bottom Line
Moody's screens as overvalued on both the Excess Returns intrinsic value estimate and the earnings multiple work, so the valuation message is consistent rather than mixed. Broader checks also lean weak, which reinforces the idea that investors are already paying up for the quality and resilience of the franchise. The crux for anyone considering Moody's now is simple: either future profitability and pricing power stay strong enough to support that premium, or the current enthusiasm cools and the valuation settles closer to the intrinsic value and fair P/E markers outlined above.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com