


Grindr (GRND) Settles UK Privacy Case As Investors Ask If The Stock Is Fully Valued
Grindr (GRND) has just closed a long running UK group action over historic privacy allegations tied to its pre 2020 ownership. The company has agreed to staged payments and reaffirmed its current focus on data protection.
For shareholders, the legal closure lands after a mixed run for Grindr’s stock, with the share price down about 4.6% over the past month but up roughly 21% over 90 days, and a three year total shareholder return of about 141% that contrasts with a slightly negative 1 year total shareholder return of about 4.9%.
Scan how Grindr’s legal cleanup compares with other platforms under pressure on governance and data trust by reviewing our hand picked 11 resilient stocks with low risk scores.
Grindr has put a messy chapter behind it and the share price has already moved sharply over 90 days. Is most of the rerating done, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 26.5% Undervalued
Grindr’s most followed valuation story pegs fair value at $20.80 per share versus a last close of $15.28. This frames the latest legal resolution against a market that still prices in a sizeable gap.
Ongoing shift toward value-added premium tiers, coupled with planned pricing experiments and the introduction of more differentiated features (e.g., mapping, intentions-based products, A-List), positions Grindr to lift ARPU and improve net margins over time.
Want to see what kind of revenue trajectory, margin lift and future earnings multiple are baked into that fair value for Grindr? The narrative leans heavily on subscription monetization, ad expansion and a higher profitability profile that has to hold together all the way through the forecast window.
Result: Fair Value of $20.80 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Grindr story can break if rising operating costs squeeze profitability or if regulatory and brand safety issues limit advertising and premium feature monetization.
Find out about the key risks to this Grindr narrative.
Another View: Grindr Looks Expensive On Earnings
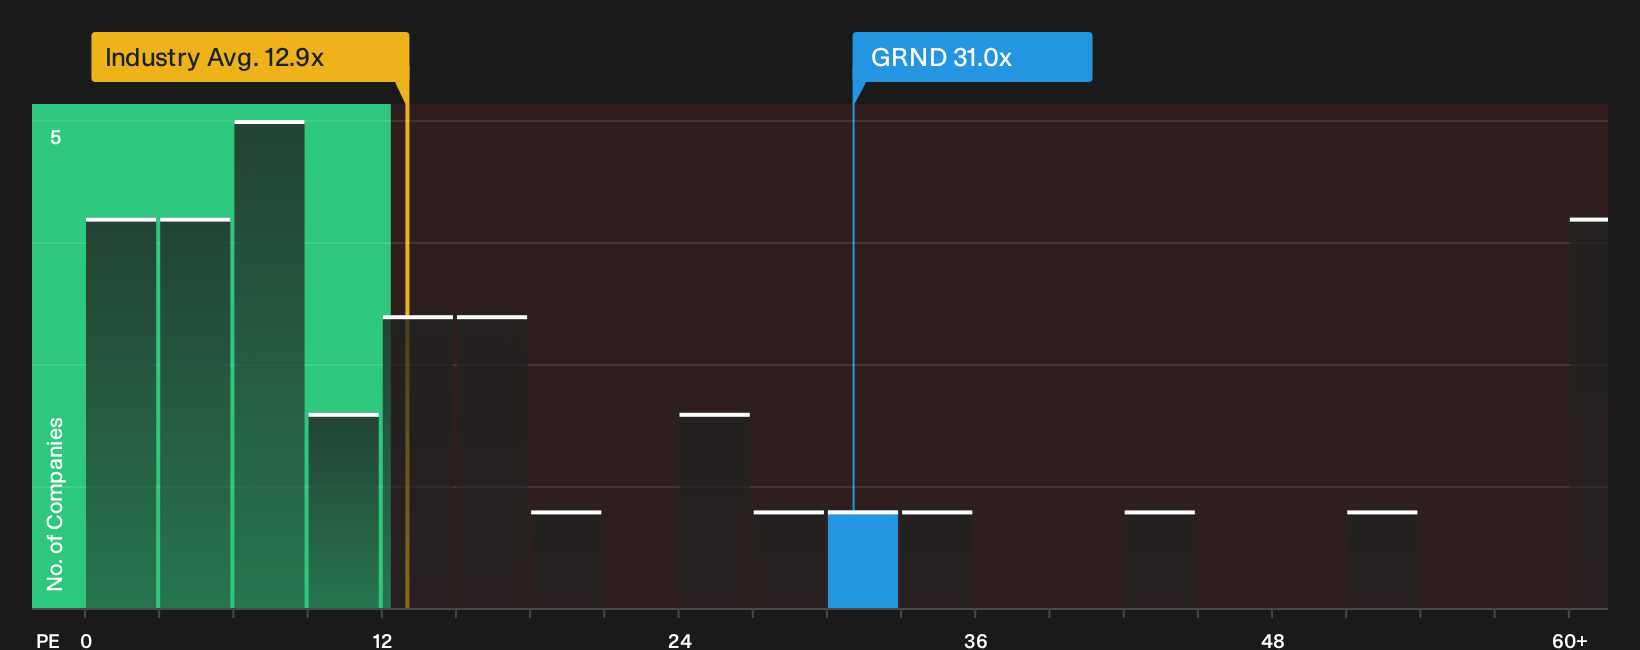
On a simple P/E yardstick, Grindr tells a very different story. The stock trades around 31x earnings, compared with a fair ratio of 22.1x, peers at 13.1x and the wider US Interactive Media and Services group at 12.9x. That is a rich premium. Is that much optimism comfortable for you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Grindr’s value and risk profile can feel disorienting. Move quickly, look through the underlying data, and pressure test every assumption for yourself. Then round out your view with the 4 key rewards and 3 important warning signs
Looking for more Grindr style investment ideas?
If Grindr has your attention, do not stop here. Use the Simply Wall Street Screener to quickly surface fresh ideas that fit your own risk and return preferences.
- Chase potential mispricings by zeroing in on companies that combine quality fundamentals with attractive valuations through the 15 high quality undiscovered gems.
- Strengthen your core holdings by focusing on businesses with healthier finances using the list of solid balance sheet and fundamentals (23 results).
- Target income focused opportunities with higher yields and resilient profiles by scanning the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com