


IES Holdings (IESC) Rallies On Momentum While Fair Value Stays Open To Debate
IES Holdings (IESC) has been drawing attention after a recent move in its share price, with the stock closing at US$345.71 and posting strong year to date and 1 year total returns.
The latest 8.2% 1 day share price gain for IES Holdings comes after a softer 30 day share price return, which is down 8.6%. Yet the stock still carries strong momentum with a 69.9% year to date share price return and an 83.1% 1 year total shareholder return, indicating investors have rapidly repriced both growth prospects and risk in the story.
Scan how IES Holdings fits into a wider infrastructure and electrical services trend by comparing it with a hand picked group of 39 power grid technology and infrastructure stocks
After that sharp move and with IES Holdings trading below analyst targets yet above some intrinsic value estimates, the real tension sits in the gap between price and caution. Does the recent surge overshoot what the business justifies?
Price-to-Earnings of 30.3x: Is it justified?
IES Holdings currently trades on a P/E of 30.3x, a level that lines up with its peer group yet sits below the broader US Construction industry.
The P/E ratio compares the company’s share price to its earnings per share. For a business like IES Holdings, which generated $4.0b in revenue and $454.2m in net income, this metric indicates how much investors are paying for each dollar of current profit.
The 30.3x multiple matches the peer average and is below both the industry P/E of 32.4x and an estimated fair P/E of 35.6x. The market is valuing IES Holdings at a level that already reflects strong recent profit growth and a 37.1% return on equity, while still leaving room for the P/E to move closer to that fair ratio if confidence in the earnings profile holds.
Explore the SWS fair ratio for IES Holdings
Result: Price-to-Earnings of 30.3x (UNDERVALUED)
Still, IES Holdings carries clear pressure points, including execution risk across its multiple segments and the possibility that recent share price gains could reverse if sentiment cools.
Find out about the key risks to this IES Holdings narrative.
Another view on IES Holdings valuation
The P/E story tilts in IES Holdings' favor, yet the SWS DCF model paints a cooler picture. On that cash flow view, an estimated value of $264.67 sits below the current $345.71 share price, which points to the stock trading at a premium rather than a bargain.
That gap between earnings based value signals and the DCF result raises a more difficult question: Are you more comfortable paying up for current profitability, or would you rather wait for a price that better aligns with modeled cash flows?
Look into how the SWS DCF model arrives at its fair value.
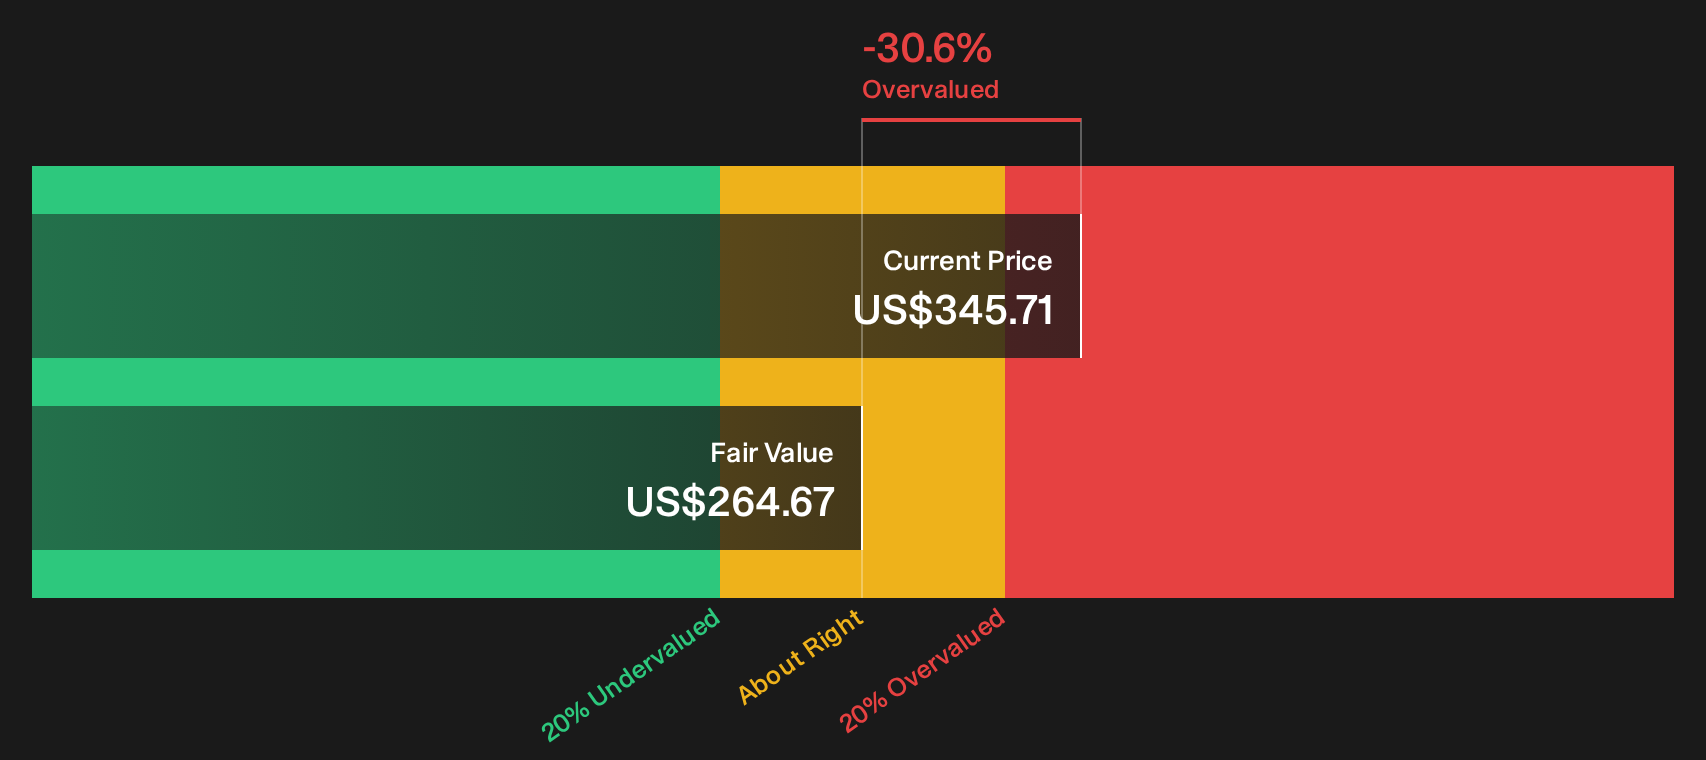
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out IES Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on IES Holdings so far. The pricing signals and cash flow estimate point in different directions, so move quickly on your own homework and weigh the 4 key rewards and 2 important warning signs.
Looking for more IES Holdings sized opportunities?
If you like what you see in IES Holdings but do not want to rely on a single stock, widen your lens with a focused set of screened ideas.
- Target steadier compounding by reviewing companies that score well on resilience in a 11 resilient stocks with low risk scores.
- Hunt for quality at a discount by scanning a 32 high quality undervalued stocks that combine strong business fundamentals with lower implied expectations.
- Spot potential future standouts early by working through a 15 high quality undiscovered gems that already show solid fundamentals before wider attention arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com