


Novanta (NOVT) Could Be 25% Undervalued If Its Growth Narrative Holds
Novanta (NOVT) has drawn fresh attention after recent trading left the shares at US$146.56. The move comes against mixed short and longer term return figures for the medical and automation technology specialist.
Recent trading has been choppy for Novanta, with the 1 day share price return of 1.84% coming after a 30 day share price decline of 12.02% and a 90 day share price return that is down 6.43%. At the same time, the year to date share price return sits at 31.87% and the 1 year total shareholder return is 27.97%, which hints that short term momentum has faded while the longer run trend has still been positive for investors who stayed in the stock.
Compare Novanta's recent swings with hand-picked peers by scanning 38 robotics and automation stocks that are also exposed to precision manufacturing, medical robotics, and automation trends.
The share price pullback and still strong 1 year return leave Novanta at a crossroads. Do the current fundamentals justify taking on more risk at US$146.56, or has the easy part of the upside already passed?
Most Popular Narrative: 24.6% Undervalued
Against the last close at $146.56, the most followed narrative pegs Novanta's fair value at $194.50. It leans heavily on earnings and margin progression over time.
Structural demographic shifts and increased healthcare spending are driving the ongoing expansion in medical devices and diagnostics. Novanta's strong presence and recent wins in minimally invasive surgery and next-generation surgical devices underpin sustained double-digit growth in its Advanced Surgery business, likely supporting both total revenue growth and higher net margins via more recurring consumables sales.
Read the complete narrative. Read the complete narrative.
Want to see what sits underneath that fair value for Novanta? The narrative leans on faster top line expansion, fatter margins, and a richer earnings base. Curious which revenue mix shifts and profitability targets do the heavy lifting in that model.
Result: Fair Value of $194.50 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the upbeat fair value story around Novanta can quickly weaken if acquisition driven growth underdelivers or if trade related manufacturing shifts drag on margins longer than expected.
Find out about the key risks to this Novanta narrative.
Another View: Novanta Looks Expensive On Earnings
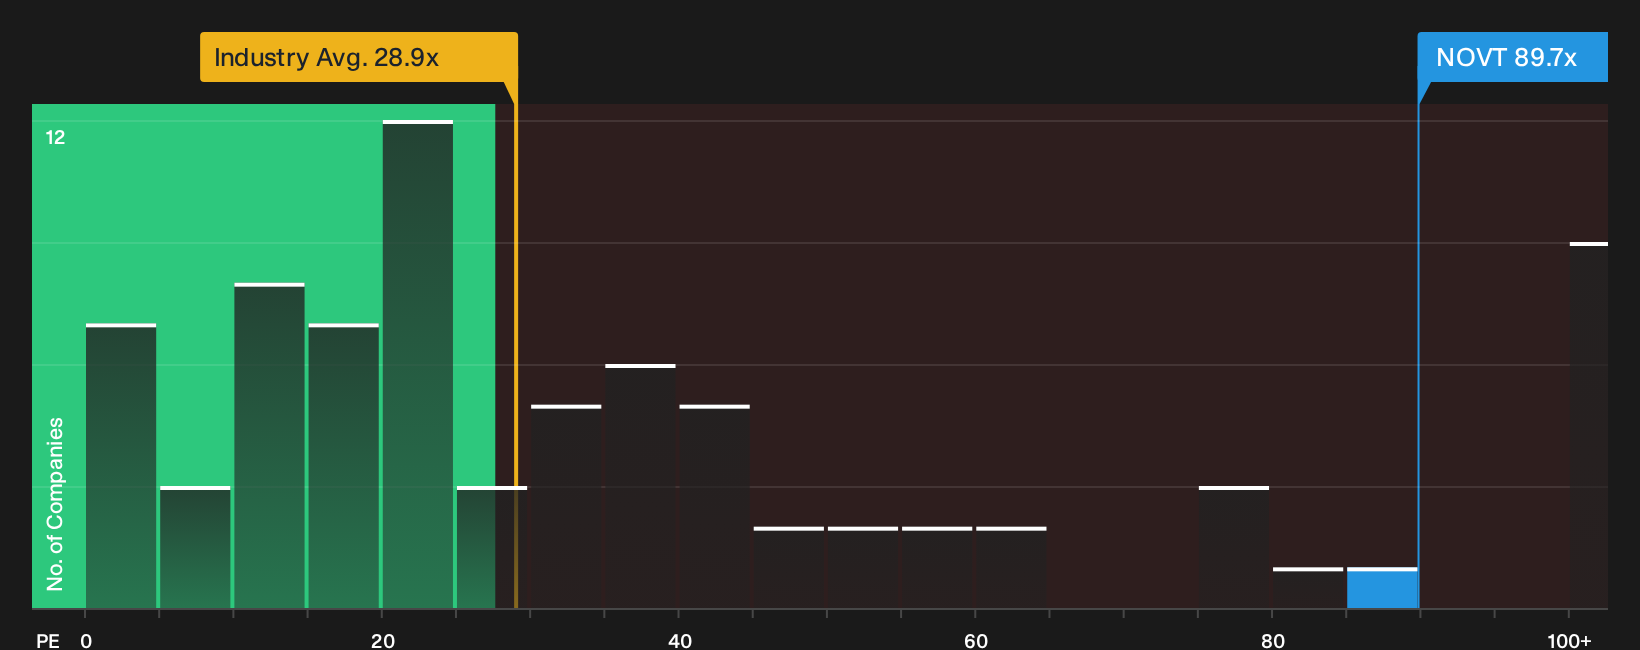
While the fair value narrative presents Novanta as 24.6% undervalued at $194.50, the plain P/E math points in a different direction. The shares trade around 89.7x earnings versus a 39.3x fair ratio, a 28.9x industry average, and a 53.7x peer average; this suggests meaningful valuation risk if sentiment cools.
That kind of premium can persist for a while when a story is popular. At some point, however, investors usually ask whether the business can grow into a multiple this rich or whether expectations reset instead.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Novanta often create urgency for knee jerk decisions. Pause for a moment, review the full data set, and weigh both the upside and the red flags by checking the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Novanta?
Do not stop your research with Novanta. Broaden your watchlist now so you can consider fresh opportunities before they become crowded trades.
- Explore potential in smaller companies by scanning the 21 elite penny stocks with strong financials that already show stronger financial underpinnings than typical micro caps.
- Consider both price and quality by reviewing the 32 high quality undervalued stocks that combine healthier balance sheets with cash flows that support their current valuations.
- Reduce portfolio concentration by focusing on the 11 resilient stocks with low risk scores that carry more resilient risk scores and may help smooth overall returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com