


Brady (BRC), What Is Behind The Latest Attention On The Stock?
Brady (BRC) just wrapped a busy early September, pairing its fourth quarter and full year results with a dividend increase and a completed share repurchase tranche that together reshape the shareholder return picture.
Brady’s recent earnings release, dividend lift and completed buyback arrived after a choppy few weeks for the share price. The stock recorded a 1-day share price return of 1.20% following a 7-day decline of 3.62% and a 30-day drop of 7.65%. This contrasts with a 10.54% year to date share price gain and a 1-year total shareholder return of 10.89%, supported by 3-year and 5-year total shareholder returns of 62.55% and 90.71% respectively. Together, these figures indicate that longer term momentum has been solid even as short term sentiment has cooled.
Compare Brady’s mix of earnings momentum, buybacks and dividends with other companies that pair shareholder returns with solid fundamentals using our hand picked 32 high quality undervalued stocks.
After solid multi year returns and a recent pullback, Brady now sits at an interesting crossroads. Does the current valuation still leave enough upside to justify the risks buyers take from here?
Most Popular Narrative: 18.7% Undervalued
Brady's most followed valuation story pegs fair value at $107 per share compared with the recent close at $86.94, putting a spotlight on what underpins that gap.
The company's deepening product ecosystem and recent acquisitions (Gravotech, Funai Microfluidics, Mecco) expand capabilities in direct part marking, barcode/RFID solutions, and software integration, directly addressing rising global requirements for traceability, regulatory compliance, and asset tracking; this supports entry into higher growth, higher margin markets and drives recurring revenue streams.
Want to see why this fair value sits well above Brady's current share price? The narrative leans heavily on faster top line expansion, stronger cash generation and a future profit multiple that assumes the market will reward that profile. Curious which exact revenue, earnings and margin paths need to play out to make that $107 hold up.
Result: Fair Value of $107 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the story can break if trade tariffs bite harder than expected, or if organic demand in Europe and Australia continues to drift lower.
Find out about the key risks to this Brady narrative.
Another View On Brady’s Valuation
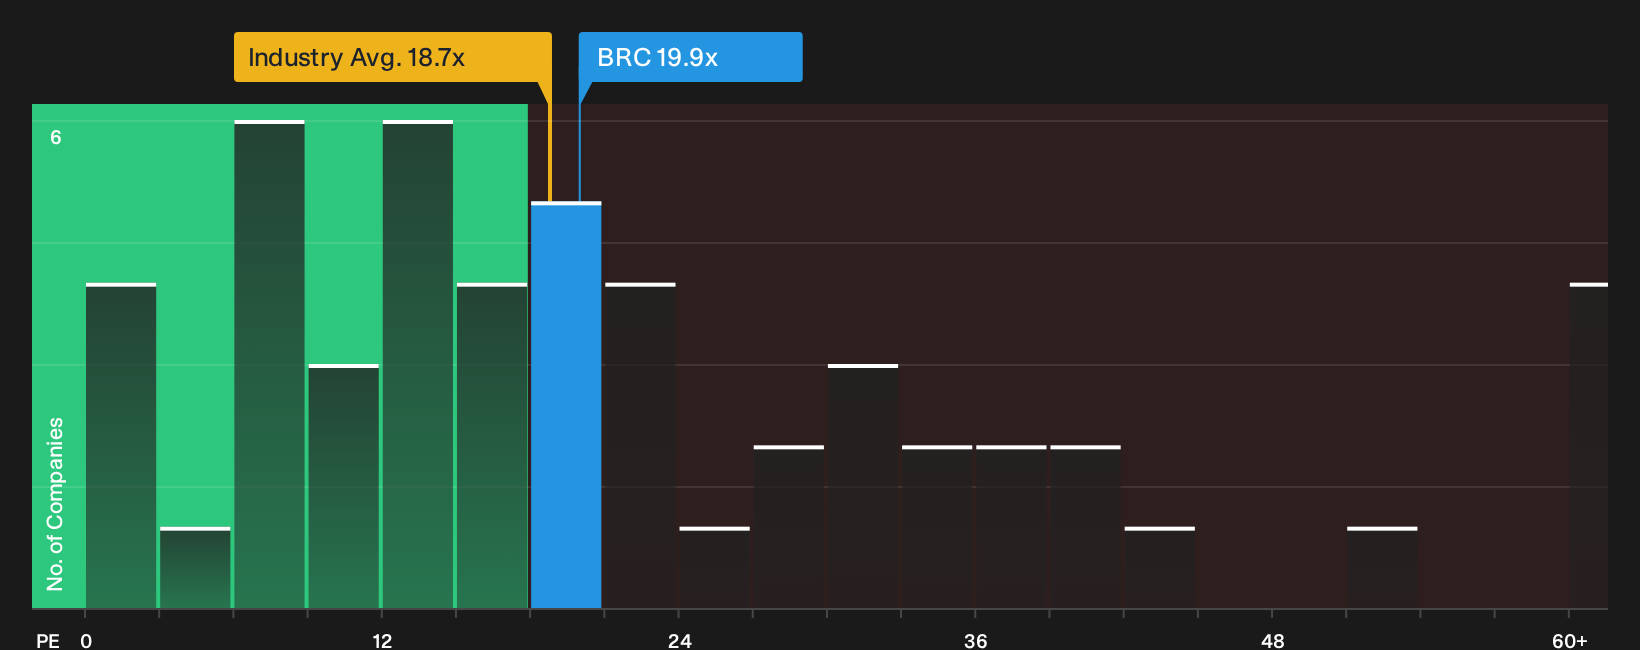
Look past the $107 fair value narrative and the story changes. Brady trades on a P/E of 19.9x, which is higher than both the US Commercial Services industry at 17.9x and its peer average of 15.4x, even though the fair ratio points to 24.8x as a level the market could move toward. That gap leaves you weighing whether you are paying up today for quality or taking on valuation risk if sentiment cools.
Before leaning too heavily on any single metric, it can help to see how all the P/E comparisons and the fair ratio fit together in one place. That is where the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Reading all this and sensing cautious optimism around Brady's setup? Move fast, pressure test these assumptions against your own research, then weigh the 3 key rewards.
Looking for more investment ideas beyond Brady?
If Brady has your attention, do not stop there. Use the screener to uncover companies with different risk and return profiles that may better fit your goals.
- Target resilience first and hunt for companies with stronger downside protection using the 11 resilient stocks with low risk scores.
- Pursue value and seek out quality enterprises trading below their implied worth through the 32 high quality undervalued stocks.
- Hunt for future leaders early and scan potential future standouts with the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com