


Did Commercial Aerospace Demand Just Shift Howmet Aerospace (HWM) Stock Narrative?
- Howmet Aerospace recently reported around 28% year-over-year revenue growth in Q2 2026, led by a 32% increase in Engine Products and supported by the completed purchase of Stanley Black & Decker's Consolidated Aerospace Manufacturing fastening business in April 2026.
- The combination of strong commercial engine spare demand and added fastening content from the acquired CAM portfolio points to deeper integration with major aircraft programs and greater exposure to long-cycle aerospace build schedules.
- The next area of focus is how this surge in commercial aerospace demand and the CAM acquisition reshapes Howmet Aerospace's broader investment narrative.
Compare Howmet Aerospace's aerospace exposure with a curated group of suppliers riding similar build schedules through our 39 power grid technology and infrastructure stocks
Howmet Aerospace Investment Narrative Recap
To own Howmet Aerospace, you need to be comfortable with a thesis built around commercial and defense flight activity, engine aftermarket demand, and content per aircraft. The recent 28% revenue growth in Q2 2026, led by a 32% jump in Engine Products, reinforces that the near term story still leans heavily on engine spares and narrow body build schedules.
The key short term swing factor is whether that commercial aerospace strength holds up against OEM production hiccups or destocking. The biggest risk remains exposure to a few large aircraft manufacturers and the capital already committed to capacity. On its own, the Q2 report does not change those core risks; however, it does suggest the current demand backdrop is still supportive.
The CAM fastening acquisition is the clearest operational announcement tied to this news. By adding Stanley Black & Decker's Consolidated Aerospace Manufacturing portfolio in April 2026, Howmet Aerospace broadened its catalog of aerospace fasteners that sit alongside its existing Engine Products and Fastening Systems businesses.
This deal plugs directly into the same build cycle that is driving the 2026 revenue lift. Greater fastening content on major aircraft programs can deepen ties with Boeing, Airbus, and defense platforms, while also increasing exposure to any production slowdowns, contract resets, or supply chain issues. For investors, CAM makes the upside in strong build rates more appealing, but it also concentrates the operational risk in the same set of aerospace programs.
Howmet Aerospace's narrative projects US$13.2b revenue and US$3.1b earnings by 2029, based on analyst estimates. This implies 13.0% yearly revenue growth and an earnings increase of about US$1.2b from the US$1.9b in earnings today.
Uncover why Howmet Aerospace's fair value indicates a 42% potential upside to its current price that could narrow quickly.
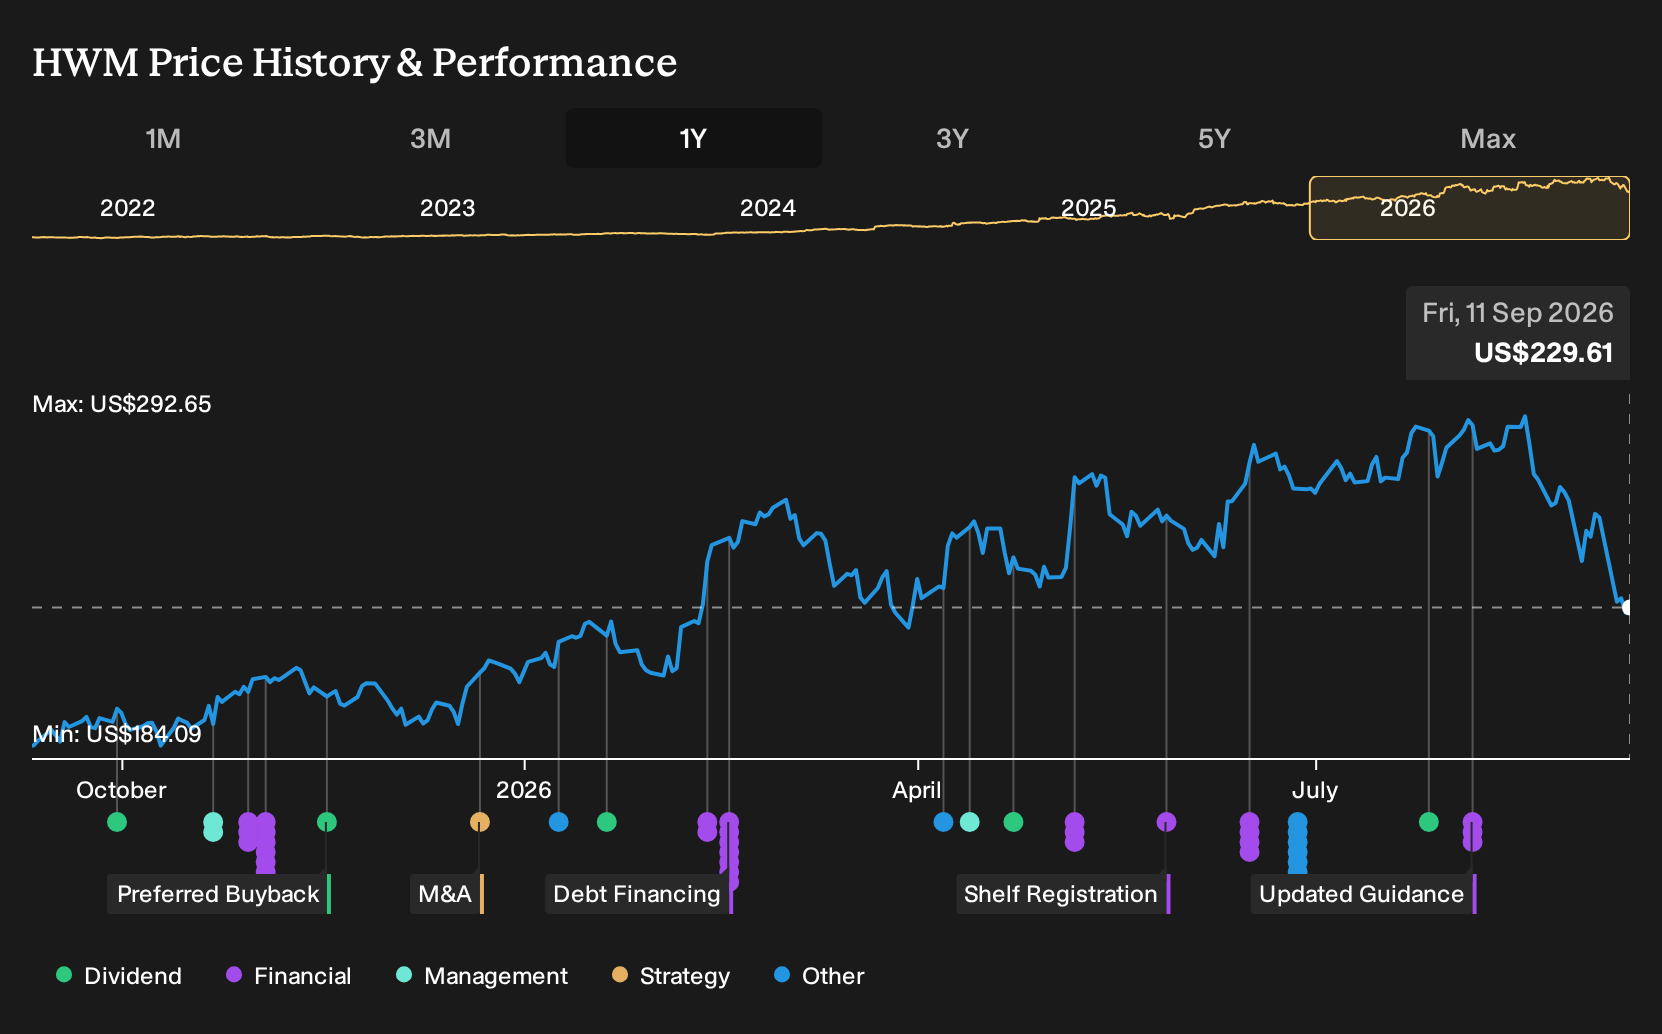
Exploring Other Perspectives
One alternate view on Howmet Aerospace leans hard into aftermarket strength as a catalyst. Bullish analysts were already penciling in revenue of about US$14.4b and earnings of US$3.9b by 2029, compared with the consensus US$13.2b and US$3.1b. The new Q2 surge and CAM deal could push those narratives to evolve.
Explore 5 other Howmet Aerospace fair value estimates, including one that suggests as much as 63% higher than the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Howmet Aerospace research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Howmet Aerospace. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Howmet Aerospace's overall financial health at a glance.
Looking for more investment ideas beyond Howmet Aerospace?
Once you have a view on Howmet Aerospace, it often helps to widen the lens and compare it with other companies that match your risk profile and income goals. The Simply Wall St Screener lets you filter for traits that matter to you, rather than just chasing headlines or the latest ticker move.
- For investors who care about resilience first and returns second, start with a focused group of companies screened for lower risk profiles through the 11 resilient stocks with low risk scores.
- If steady cash generation and healthy finances are your priority, scan a broader universe of businesses with stronger balance sheets using the list of solid balance sheet and fundamentals (23 results).
- Those hunting for opportunities the market may be underpricing can look across a curated set of higher quality stocks that screen as potentially cheap via the 32 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com