


JFrog (FROG) Launches New Security Tools As Fair Value Stays In Focus
JFrog (NasdaqGS:FROG) is back in focus after rolling out Curation and a wider suite of security tools for software supply chains, along with fresh integrations that aim to tighten AI era risk management.
Recent launches like AgentSecOps tooling, Zero-Touch Remediation and the Wiz partnership arrive after a strong run in JFrog’s stock. The share price is up 46.35% year to date and the 1-year total shareholder return is 74.57%, while shorter term momentum has cooled with a 30-day share price decline of 9.35% against an already elevated 3-year total shareholder return of about 3.2x.
Scan the AI security space beyond JFrog by reviewing a curated set of 32 AI small caps that are also focused on securing software supply chains and agent workflows.
The run in JFrog has been strong; the recent pullback less so. Does the current valuation still give buyers enough compensation for execution risk and ongoing losses, or has the reward already been pulled forward?
Most Popular Narrative: 22.2% Undervalued
JFrog’s most followed valuation storyline pegs fair value at $112, comfortably above the last close of $87.18, which frames the recent pullback in a very different light.
The need for hybrid and multi-cloud deployment models is intensifying as organizations seek cost predictability, compliance, and flexibility when running AI workloads. JFrog's platform, architected from inception for both cloud and on-prem/hybrid, appeals to enterprises facing this complexity, helping to secure large, multi-year enterprise contracts, boost retention, and expand average deal size.
Want to see what keeps that $112 figure in play even with ongoing losses on the income statement? The blueprint leans hard on sustained top line expansion, richer margins over time, and a future earnings multiple usually reserved for market darlings.
Result: Fair Value of $112 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, if hybrid or on premises deployments stretch deal cycles or if security rivals pressure pricing, the bullish JFrog narrative could look more fragile than forecasts imply.
Find out about the key risks to this JFrog narrative.
Another View: JFrog Looks Expensive On Sales
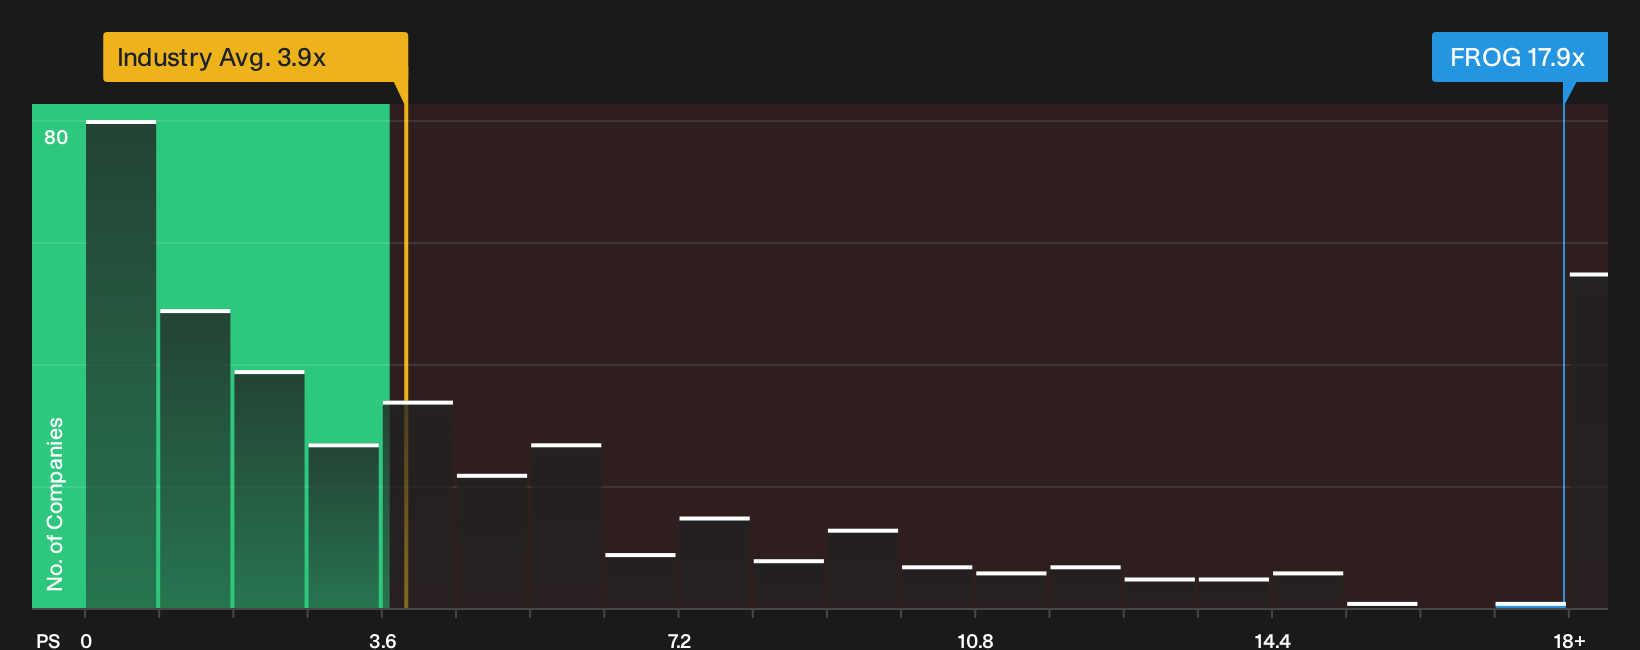
The AI narrative leans on a $112 fair value, yet JFrog’s current P/S ratio of 17.9x tells a very different story. That multiple sits far above the US Software industry at 3.9x, above peers at 5.7x, and more than double the 7.8x fair ratio the market could move toward. If growth or sentiment cools, how much compression risk are you really taking on?
For a closer look at how the numbers stack up against that fair ratio view, including where valuation pressure might show up first, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around JFrog’s valuation and risk profile can feel noisy, so move quickly, review the underlying data yourself, and then weigh the 2 key rewards and 2 important warning signs
Looking for more ideas beyond JFrog?
If JFrog has sharpened your focus on where risk and reward meet, do not stop here. Fresh opportunities rarely wait for slow decisions.
- Target dependable compounding by reviewing a curated set of steady cash generators in the 6 dividend fortresses.
- Hunt for potential mispricing by scanning the 15 high quality undiscovered gems before other investors start paying attention.
- Prioritise resilience first by filtering for companies with robust finances through the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com