


AeroVironment (AVAV) Lands Laser Wins And Record Revenue, But Is The Valuation Already Full?
AeroVironment (AVAV) just delivered record quarterly revenue of US$480.5 million and expanded its funded backlog to US$1.5b, following major U.S. Army laser contracts and its first international LOCUST order.
Despite the contract wins and record quarter, AeroVironment’s share price has retreated. The 30-day share price return is down 23.9% and the year-to-date share price return is down 42.7%. However, the 3-year total shareholder return is up 31.7% and the 5-year total shareholder return is up 70.1%. This indicates that long-term investors are still ahead, while shorter term momentum has cooled sharply.
Scan the defense-tech space for other under-the-radar plays with contract momentum similar to AeroVironment by reviewing our curated list of 15 high quality undiscovered gems.
AeroVironment’s contracts, backlog and guidance now sit against a share price that has already fallen hard. Does this reset leave more upside than downside for new buyers, or is the risk now catching up with the story?
Most Popular Narrative: 41.1% Overvalued
AeroVironment last closed at $146.71, while the most followed narrative on Simply Wall St assigns a fair value of $103.94. This marks a sizable gap between story and price.
The prior call used inflection-point language as anticipatory framing: things are approaching an inflection point. The current one uses it retrospectively, to describe something that has already arrived. Nawabi deploys the phrase in relation to LOCUST specifically at least five times across prepared remarks and Q&A: “We are at an inflection point.” “This is an inflection point.” “I think we are at a similar inflection point.” The density of the phrase is notable because inflection points, by definition, are singular. When a company declares one, the narrative utility of the declaration diminishes with each repetition. By the fifth instance, it functions more as tonal reinforcement than analytical signal.
The valuation call hinges on how much weight you put on those laser contracts, the revenue ramp already in backlog, and the timing of a turn to profitability. The narrative stitches those pieces into one price tag, but the crucial assumptions on growth, margins and future cash flows sit under the surface. If you want to see exactly how those moving parts add up to that $103.94 figure, the full breakdown is where the story really gets specific.
Result: Fair Value of $103.94 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, AeroVironment’s story can crack if execution around EHEL, LOCUST and Titan slips, or if internal control remediation and cash burn concerns regain focus.
Find out about the key risks to this AeroVironment narrative.
Another View On AeroVironment’s Valuation
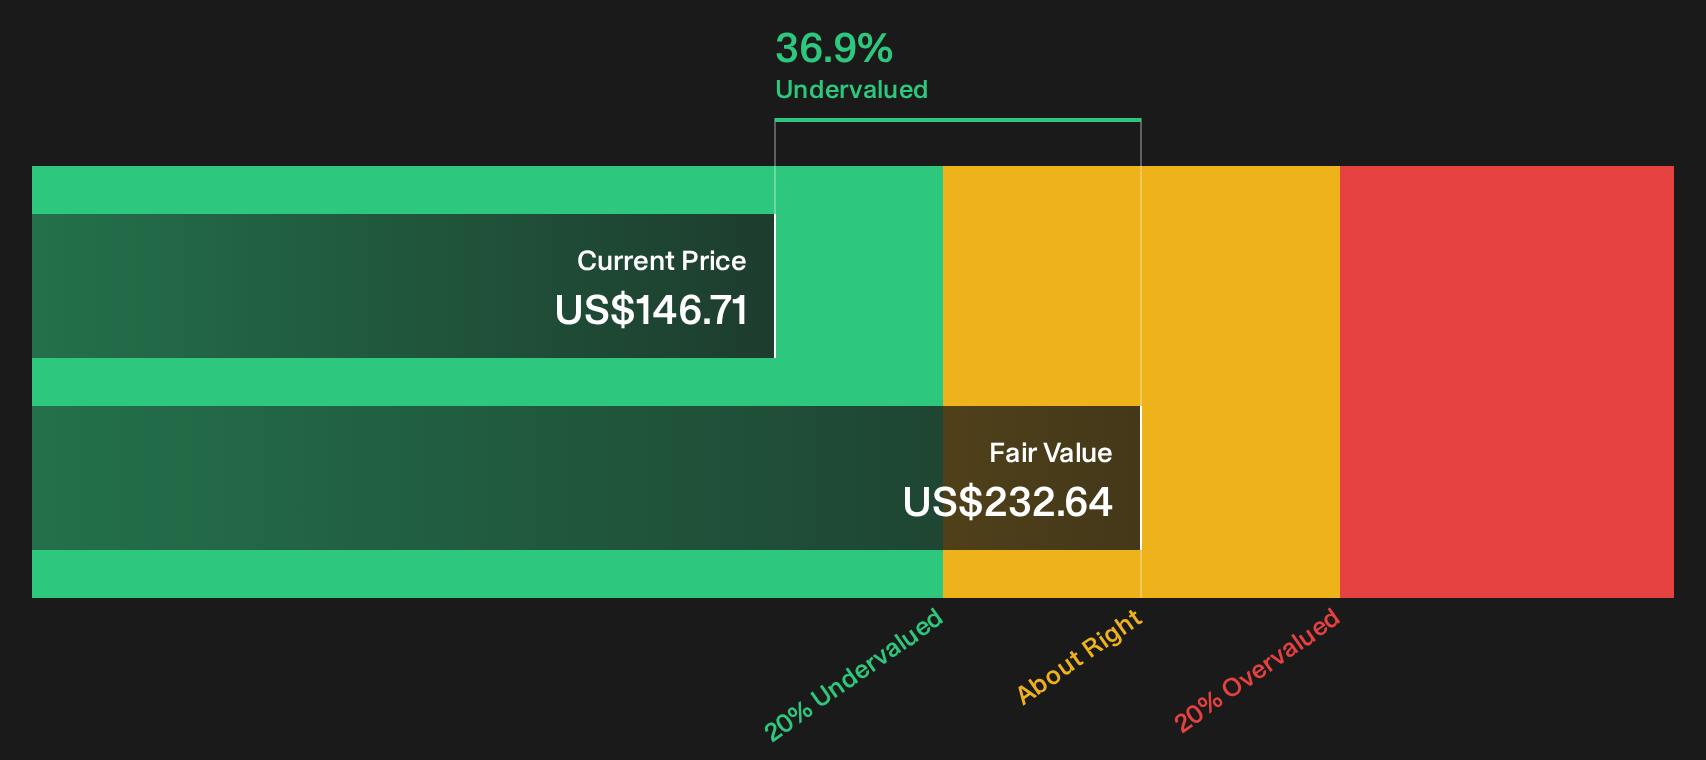
The community narrative pins AeroVironment as 41.1% overvalued at $146.71 versus a $103.94 fair value. Our DCF model points in the opposite direction. It suggests the shares are trading about 36.9% below an estimated future cash flow value of $232.64. That split forces a basic question: Which set of assumptions do you trust more, the story-based narrative or the cash flow math?
For a closer look at how those cash flows are modeled and stressed across different scenarios, Look into how the SWS DCF model arrives at its fair value.
Next Steps
That split between AeroVironment’s story and the numbers is exactly where opinion is born, so move quickly, review the key assumptions for yourself, and then weigh up the 2 key rewards and 1 important warning sign.
Looking for more AeroVironment style investment ideas?
If AeroVironment has sharpened your focus on risk, reward and timing, broaden your watchlist now so you are not late to the next opportunity.
- Target resilience by scanning a 11 resilient stocks with low risk scores that highlights businesses with steadier risk scores when markets turn choppy.
- Hunt for mispriced quality using the 32 high quality undervalued stocks to spot companies where fundamentals and current pricing look out of sync.
- Build staying power in your portfolio through the list of solid balance sheet and fundamentals (23 results) that surfaces firms with stronger financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com