


Is G-III Apparel Group (GIII) A Bargain Following Raised Full Year Guidance?
G-III Apparel Group (GIII) has put fresh numbers on the table, issuing new third quarter guidance and lifting its full year earnings outlook after reporting second quarter results for 2026.
G-III Apparel Group’s fresh guidance and raised full year outlook land against a mixed trading backdrop, with the share price down 17.7% over the past month and 19.5% over the past quarter. At the same time, the 1 year total shareholder return of 6.0% and 3 year total shareholder return of 11.6% point to momentum that has cooled recently as investors reassess both growth potential and risk after a strong multi year recovery.
Spot opportunities beyond G-III Apparel Group by reviewing the hand picked 32 high quality undervalued stocks that combine solid balance sheets with cash flows investors are watching closely.G-III Apparel Group has raised its full year earnings outlook, even as the share price has pulled back sharply. Has the recent slide already used up most of the upside, or is the valuation still leaving meaningful room ahead?
Most Popular Narrative: 30.3% Undervalued
On the most widely followed valuation narrative, G-III Apparel Group’s fair value of $40 sits well above the last close at $27.89, which puts the recent pullback into sharper context for anyone weighing the new guidance.
The PVH license roll-off (~$470M of lower-margin revenue exiting by FY2028) is a known, finite, manageable headwind. The owned-brand revenue replacing it (DKNY, Karl Lagerfeld, Donna Karan) carries structurally higher gross margins, potentially driving margin expansion even on lower absolute revenues.
Read the complete narrative. Read the complete narrative.
Curious what turns that margin story into a $40 fair value. The thesis leans on owned labels, mix shift and a future earnings multiple that usually belongs to higher profile sectors.
Result: Fair Value of $40 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the tariff hit and reliance on big wholesale customers mean a fresh trade shock or another retailer default could quickly puncture the G-III Apparel Group story.
Find out about the key risks to this G-III Apparel Group narrative.
Another View: SWS DCF Model Says Overvalued
The first narrative presents G-III Apparel Group as 30.3% undervalued at $40 fair value. The SWS DCF model lands in a very different place. On that cash flow view, GIII at $27.89 trades above an estimated value of $23.87, which points to an overvalued stock instead.
Those two anchors describe very different perspectives on risk. One leans on brand strength and earnings multiples. The other leans on modeled future cash. For an investor weighing fresh guidance against a recent share price pullback, which anchor appears more realistic for the next few years?
Look into how the SWS DCF model arrives at its fair value.
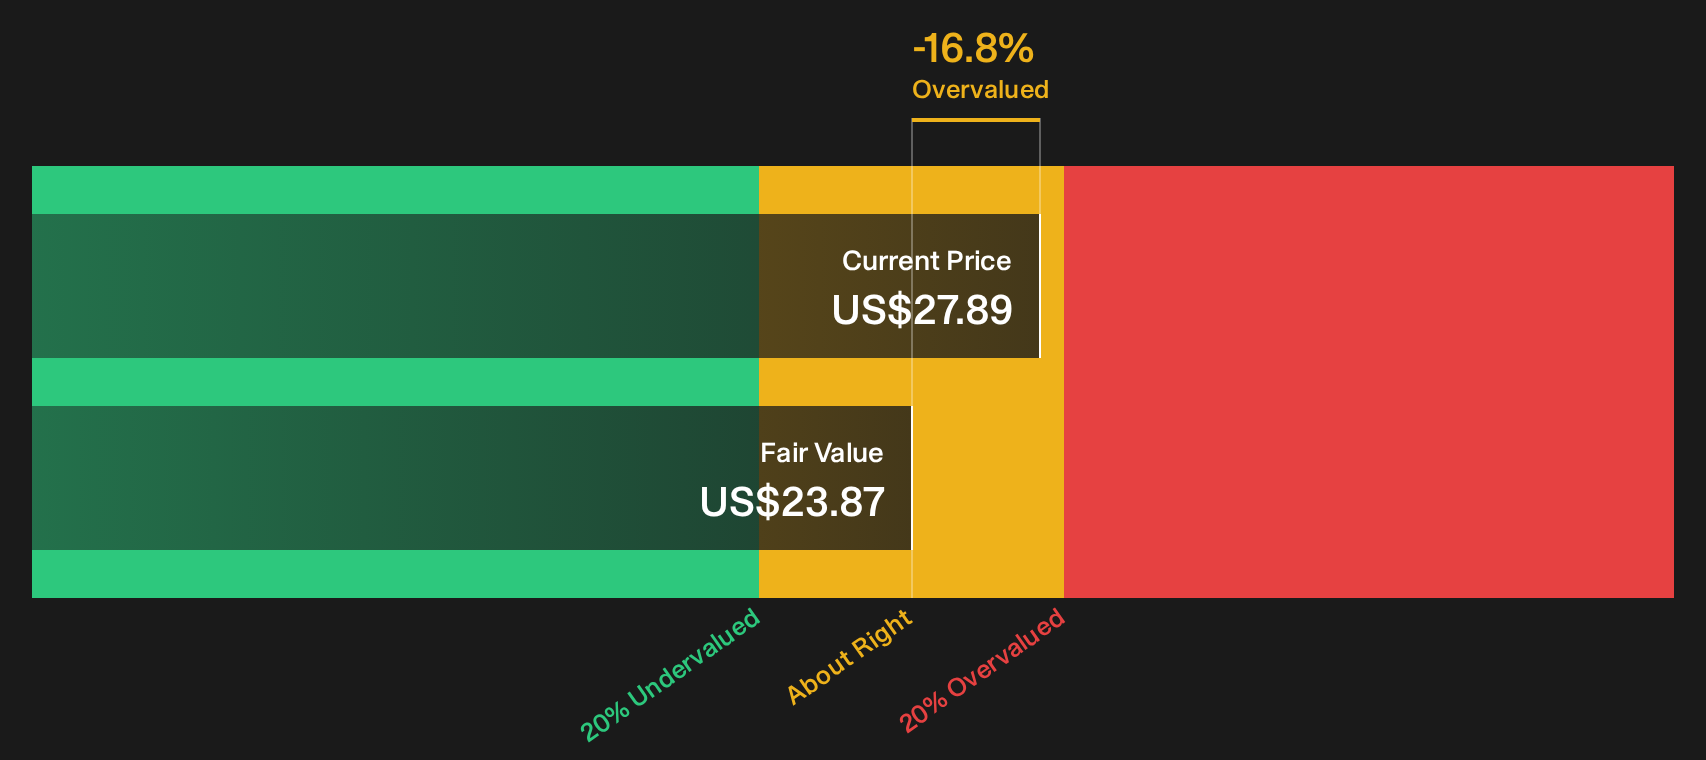
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out G-III Apparel Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around G-III Apparel Group can feel confusing, so consider reviewing the data promptly, checking the numbers for yourself, and weighing both the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond G-III Apparel Group?
Do not stop your research with G-III Apparel Group, especially when a broader watchlist can help you spot new pricing gaps and fresh themes early.
- Target potential mispricings by scanning a curated set of undervalued opportunities through the 32 high quality undervalued stocks that already meet strict balance sheet and cash flow filters.
- Prioritise resilience by reviewing a 11 resilient stocks with low risk scores that highlights businesses with sturdier financial profiles when conditions get choppy.
- Get ahead of the crowd by tracking a focused 15 high quality undiscovered gems that surfaces quality fundamentals before they gain wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com