


How Investors Are Reacting To Kalmar Oyj (HLSE:KALMAR) Test Centre Opening
- Kalmar Oyj has reorganized its operating model, combining Terminal Tractors and Horizontal Transportation into one division and reshaping its leadership team, while opening a fully automated Test Centre in Ljungby, Sweden to support electric and autonomous material handling equipment development.
- The new Ljungby facility allows Kalmar Oyj to run 24/7 automated lifetime tests on EV and diesel machines up to 45 tons under extreme temperatures, which could enhance product reliability and streamline development cycles across both ports and distribution customers.
- We will now look at how Kalmar Oyj's new combined equipment division may influence the investment narrative around automation and electrification.
Scan beyond Kalmar Oyj and spot other automation and electrification plays by zeroing in on 38 robotics and automation stocks that could benefit from similar shifts in heavy equipment and logistics.
Kalmar Oyj Investment Narrative Recap
To be comfortable owning Kalmar Oyj, you need to believe the heavy lifting in returns comes from automation and electrification gaining traction across ports and logistics, with the Equipment and Services segments both feeding that story. The new operating model and division merge point toward a tighter setup around that theme, but they do not fundamentally change the near term demand picture.
The key short term swing factor still looks like order momentum and pricing power in a choppy U.S. and AMEA market. The biggest risk remains execution on multiple operational changes at once, from reorganizing divisions to ongoing distribution shifts, which could add friction and costs if integration or implementation runs slower than planned.
The Ljungby automated Test Centre is the announcement that most directly links to Kalmar Oyj’s automation and electrification ambitions. It gives the Equipment segment a more controlled environment to stress test both EV and diesel machines under extreme conditions, which can support the eco portfolio narrative that many investors are watching closely.
For you, the catalyst angle is about whether this facility helps Kalmar Oyj shorten development cycles, keep structural uptime high and support the case for more advanced, higher value equipment feeding into Services over time. The operational risk is that heavy investment and complexity do not translate into faster time to market or better order intake if customer spending stays cautious.
Kalmar Oyj's current analyst narrative points to revenues of €2.1b and earnings of €225.3 million by 2029, built on a 4.5% yearly revenue growth rate and an earnings increase of about €51.9 million from €173.4 million today.
Uncover how Kalmar Oyj's fair value indicates a 10% potential upside to its current price before the discount to Kalmar Oyj closes.
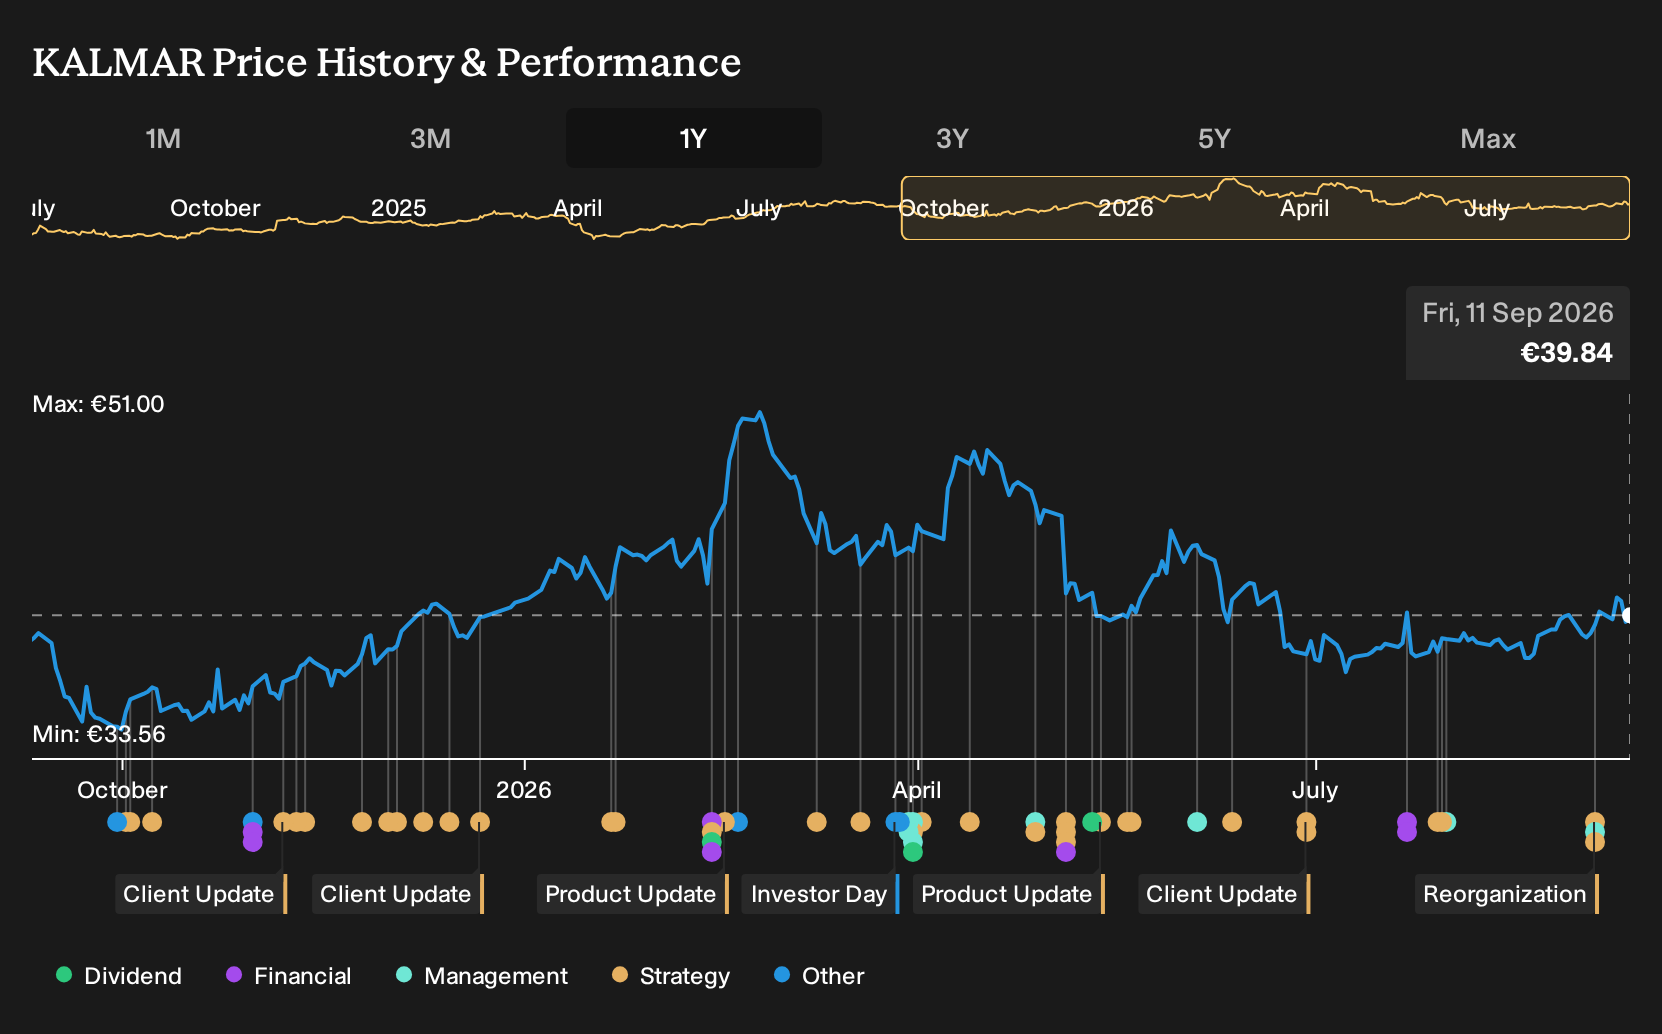
Exploring Other Perspectives
Some of the most optimistic analysts focus on Kalmar Oyj’s services engine as the real swing factor. They point to services margins of 18.5% and services orders up 12% in Q3, with earnings forecasts around €229.9 million by 2029, compared with €225.3 million in the baseline view. These estimates all pre date the Ljungby Test Centre news, so you should expect opinions to shift and should explore several viewpoints before deciding how this reorganization story fits your own thesis.
Explore 3 other Kalmar Oyj fair value estimates, including one that suggests as much as 65% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kalmar Oyj research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Kalmar Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kalmar Oyj's overall financial health at a glance.
Looking for more investment ideas beyond Kalmar Oyj?
Once you have a handle on where Kalmar Oyj fits in your watchlist, it can help to scan for other companies with traits that match your risk tolerance and return goals using the Simply Wall St Screener.
- For investors hunting for overlooked quality, consider reviewing 619 high quality undiscovered gems that pair solid fundamentals with less crowded ownership.
- If capital preservation sits high on your priority list, filter for 99 resilient stocks with low risk scores that aim to keep volatility in check while still offering earnings power.
- Income focused readers can zero in on 161 dividend fortresses that offer higher yields and may help smooth portfolio returns through different parts of the cycle.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com