


How Stronger Core Earnings At BEA Has Changed Its Investment Story
- Bank of East Asia reported stronger core earnings in the first half of 2026 as higher net interest income, healthier loan growth in trade finance and retail lending, and firmer fee income from investment products and bancassurance offset elevated credit costs tied to commercial real estate provisions.
- The bank also refreshed its governance bench, with long serving company secretary Alson Law retiring on 1 September 2026. Experienced in house lawyer Hanifa Ramjahn, a 27 year legal and financial services veteran, has taken on the company secretary and authorised representative roles.
- The next focus is on how Bank of East Asia's stronger net interest and fee income could influence its broader investment narrative.
Scan how Bank of East Asia's earnings story compares with other lenders by reviewing our curated list of list of solid balance sheet and fundamentals (194 results)
What Is Bank of East Asia's Investment Narrative?
To own Bank of East Asia, you need to be comfortable with a fairly traditional banking story. The core of it is disciplined lending in Hong Kong and mainland China, steady fee generation from wealth and insurance products, and the work of keeping credit costs in check while return on equity, currently 3.3%, remains modest. Earnings forecasts point to fast profit growth and revenue projections outpacing the wider Hong Kong market, yet the share price already embeds a P/E of 14.6x against a much lower sector average. This asks you to believe execution will stay tight.
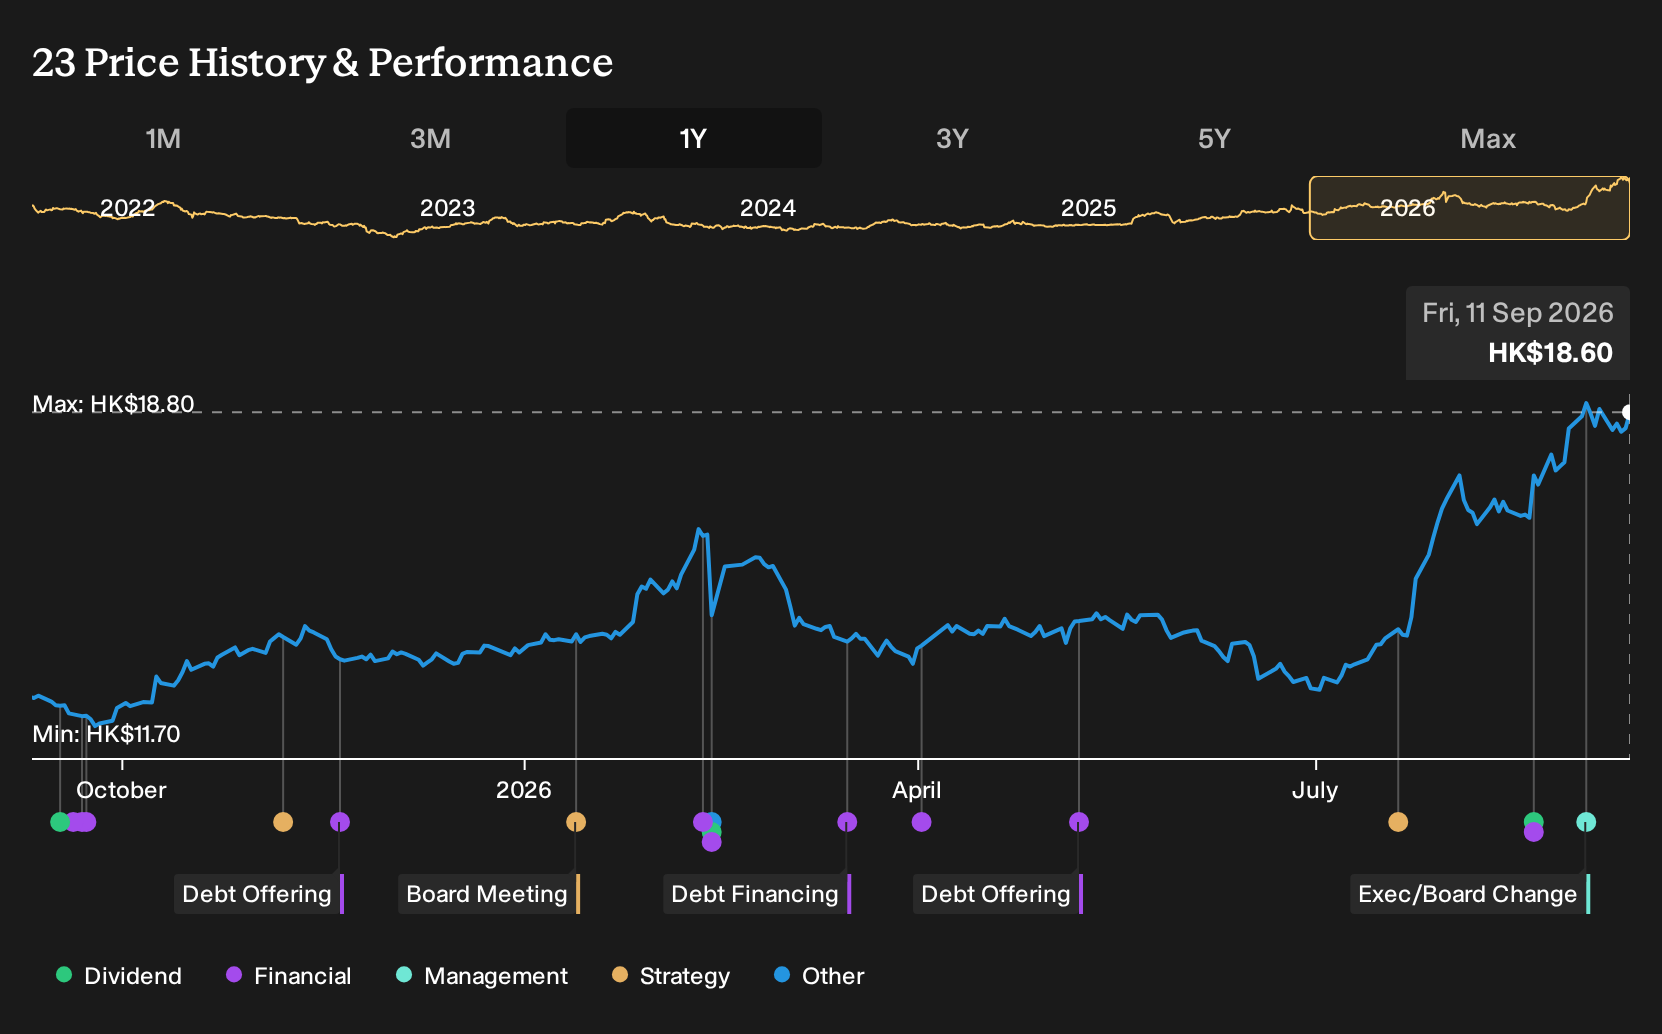
The fresh appointment of Hanifa Ramjahn as company secretary fits that thesis as a governance and compliance upgrade rather than a shift in business direction. In the short term, the more important levers are still loan quality, given a 2.7% bad loan ratio and a 49% allowance level, and how management balances growth with an unstable dividend history. Recent share gains, with a 1 year total return of 56.5%, also mean you are buying into a story the market has already started to reward.
That said, once you look past the earnings forecasts and governance refresh, one sticking point in the Bank of East Asia story is ...
There's only one way to know the right time to buy, sell or hold Bank of East Asia. Head to Simply Wall St's company report for the latest analysis of Bank of East Asia's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community has only two fair value views on Bank of East Asia so far, spread between HK$16.25 and HK$21.02 per share. Such a wide band from a small sample underlines how sharply opinions can diverge. Governance changes and shifting credit conditions could influence future community estimates in very different directions, so explore those viewpoints before forming your own stance.
Explore another Bank of East Asia fair value estimate, including one that suggests as much as 13% downside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bank of East Asia research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bank of East Asia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of East Asia's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bank of East Asia?
Once you have formed a view on Bank of East Asia, it can help to widen the lens and compare it with other opportunities that share similar financial traits or risk profiles. The Simply Wall St Screener lets you quickly filter the market using the metrics that matter most to you, so you can build a watchlist that fits your own approach rather than relying on headlines.
- If you want stronger balance sheets and fewer surprises, start with companies that clear strict financial health checks by reviewing our 99 resilient stocks with low risk scores.
- Income focused investors who care about consistency as much as yield can scan for payout heavyweights through our curated 161 dividend fortresses.
- For those hunting for businesses with solid fundamentals that fly under the radar, widen your opportunity set with our hand picked 619 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com