


Omnicom Group (OMC) Could Be 23% Undervalued Following Its Leadership Change
Omnicom Group (OMC) just announced a leadership handoff at Omnicom Advertising, with long-time executive Troy Ruhanen retiring. BBDO chairman Andrew Robertson will step in as chief executive on September 9, 2026.
For context, Omnicom Group’s share price has eased in the short term, with a 1-day move that declined 0.55% and a 30-day share price return down 9.78%, even though the 1-year total shareholder return of 5.50% and 5-year total shareholder return of 29.16% point to steadier long run progress. As a result, this leadership shift and the upcoming appearance at the Goldman Sachs Communacopia + Technology Conference may be read as fresh inputs into how investors assess growth potential and execution risk from here.
Compare how Omnicom Group’s leadership change stacks up against other communications and media players by screening for 15 high quality undiscovered gems that may be flying under most investors’ radar.
Bulls see Omnicom Group’s recent share price slide and leadership continuity as a valuation opportunity. Bears focus on execution risk after the Ruhanen handoff. Which story fits the current numbers better now?
Most Popular Narrative: 23.2% Undervalued
Omnicom Group last closed at $79.01 compared with a widely followed fair value estimate of about $102.83, which frames the leadership change against a discount that this narrative ties to execution on acquisitions, AI tooling and margin repair.
The pending acquisition and integration of Interpublic is set to create the industry's largest, most data-rich global marketing services company, unlocking significant cross-selling opportunities, cost synergies, and expanded capabilities across digital, analytics, and high-growth verticals. This is likely to drive both top-line revenue growth and margin expansion post-closing.
Curious what has to go right for Omnicom Group to justify that higher value. The narrative leans on faster earnings, steadier revenue, and richer margins over time. The gap between today’s profitability and those targets is wide. The whole story rests on how integration, cost savings, and AI driven offerings reshape the income statement.
Result: Fair Value of $102.83 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Omnicom Group’s story can break if the Interpublic integration drags on or if clients pull more work in house as AI tools get cheaper and easier to use.
Find out about the key risks to this Omnicom Group narrative.
Another View: Omnicom Group Looks Expensive On Earnings
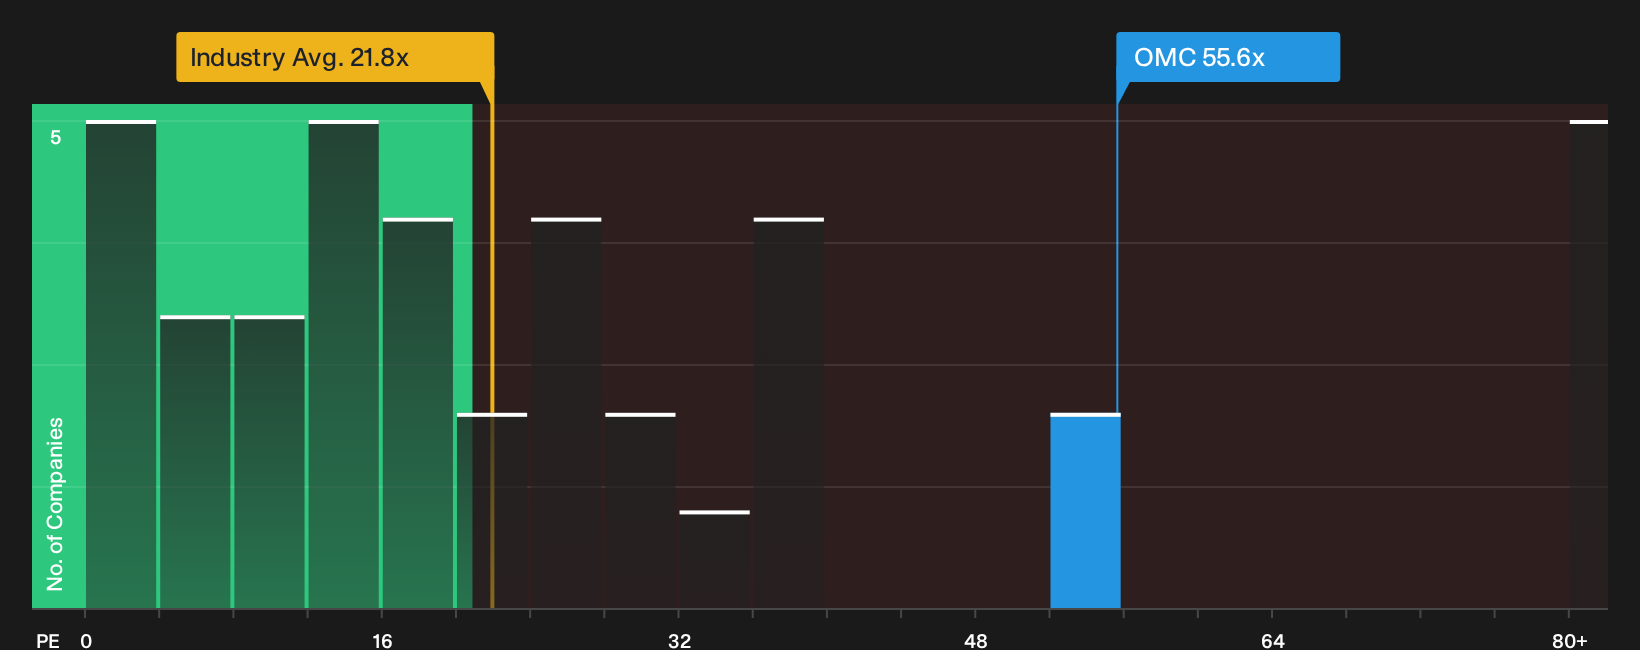
On the flip side of that 23.2% discount story, Omnicom Group is trading on a P/E of 55.6x, which is far richer than the US Media industry at 21.8x, peers at 37.1x, and its own fair ratio of 28.2x. That gap points to real valuation risk if sentiment cools.
Before leaning on any single metric, it helps to see what the numbers imply about where that P/E might drift over time, and how much room there is for disappointment or positive surprise in Omnicom Group’s earnings path. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Omnicom Group story. If that tension between upside and risk matters to you, act quickly and weigh the 2 key rewards and 5 important warning signs.
Looking for more Omnicom Group sized opportunities?
If this Omnicom Group story has you thinking harder about valuation and risk, do not stop here. Broader idea hunting often reveals the real outliers.
- Spot potential mispricing early by scanning a 32 high quality undervalued stocks that filters for quality businesses trading below their implied worth.
- Strengthen your income stream by reviewing a 6 dividend fortresses tailored to companies offering higher yields with supporting fundamentals.
- Dial back volatility and focus on resilience by working through a 11 resilient stocks with low risk scores that highlights businesses with lower risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com