


Disney (DIS) Stock Looks Fair On Cash Flow But Cheap On Earnings
Walt Disney stock has delivered a steep decline of about 40.1% over the past five years, yet current checks suggest the shares now screen closer to fairly valued on a Discounted Cash Flow (DCF) view, while earnings-based multiples look cheaper than that intrinsic value implies.
- The roughly 40.1% share price decline over five years leaves long-term holders with a material loss that may already reflect a lot of past disappointment.
- Investor focus on Disney's streaming operations and broader content portfolio can support confidence in future cash generation, while the ongoing InterDigital video technology patent dispute introduces legal and cost uncertainty that may weigh on sentiment.
- A high value score, with Walt Disney screening as undervalued in 5 of 6 checks, points to the broader set of valuation tools leaning cheap for the stock, as shown by this 5 out of 6 score.
The issue now is whether Disney's current share price already reflects the key risks around streaming, legal claims, and execution, or if the gap between market price and intrinsic value still offers enough of a cushion for new capital.
Compare Walt Disney's reset valuation and five year share price decline with a curated list of other resilient, potentially mispriced businesses in the 32 high quality undervalued stocks.
Where Does Walt Disney Sit on Cash Flow?
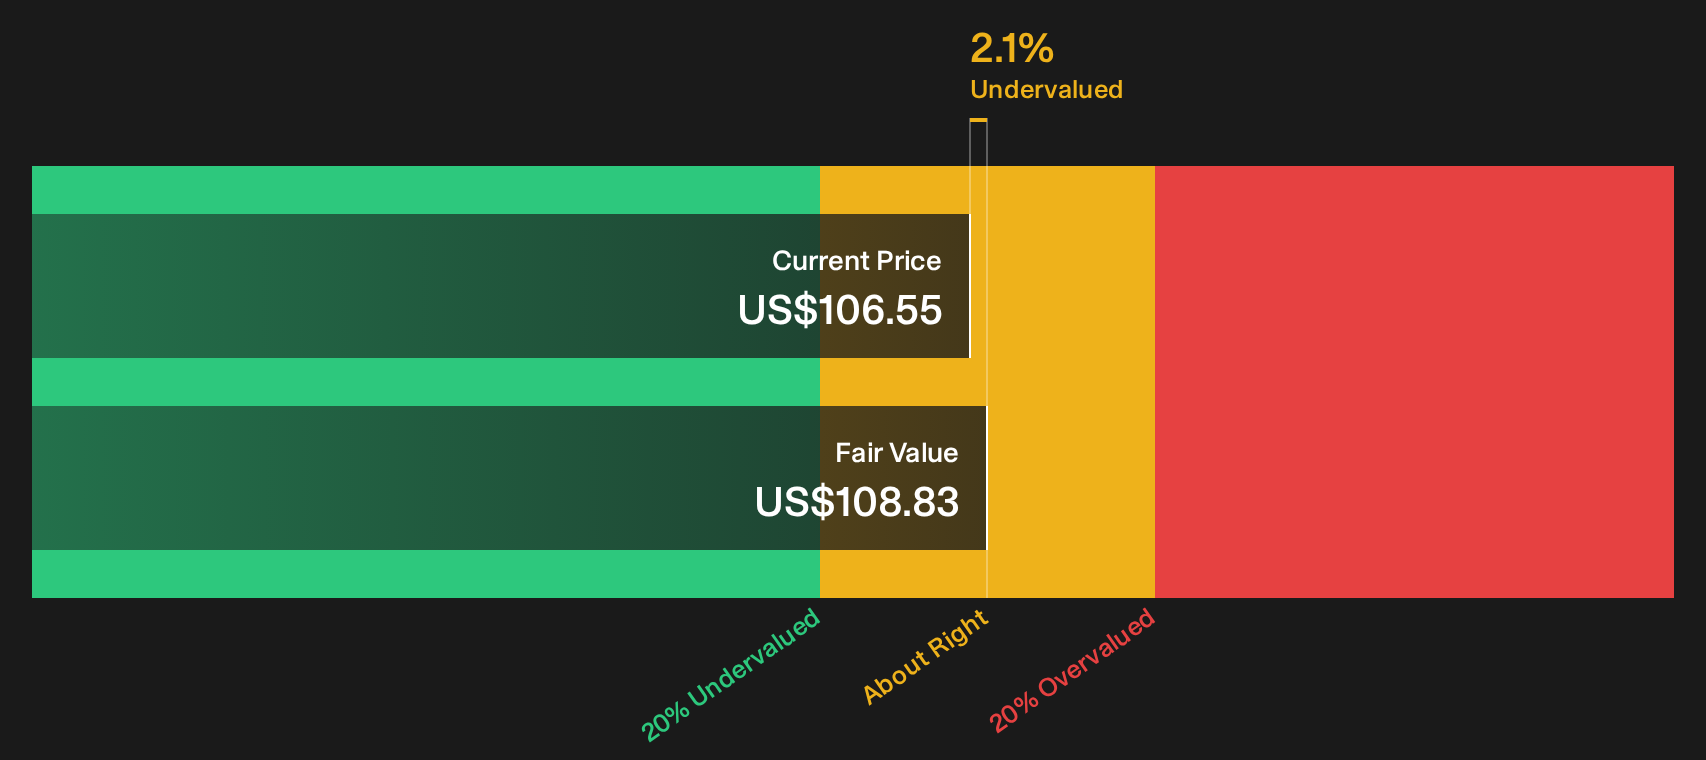
The Discounted Cash Flow (DCF) model here projects what Walt Disney could earn in free cash over time and then translates that into a per share estimate today. On this framework, Disney generated about $9.5b in free cash flow over the latest twelve months, and the DCF assumes that cash generation grows from this base rather than shrinking. That stream of projected cash flows points to an estimated intrinsic value of about $108.83 per share.
With the DCF implying the stock is only 2.1% below that estimate, Disney looks roughly fairly valued around the current market price. The InterDigital claim for €101.7m over video streaming patents helps explain why some investors may still hesitate to pay much above intrinsic value, even with cash flows screening solid.
On this cash flow view, Walt Disney stock currently screens as about fairly valued rather than clearly cheap or expensive.
Walt Disney is fairly valued according to our Discounted Cash Flow (DCF), but this can change at a moment's notice. Track the value in your watchlist or portfolio and be alerted on when to act.
Does Walt Disney Look Undervalued on Earnings?
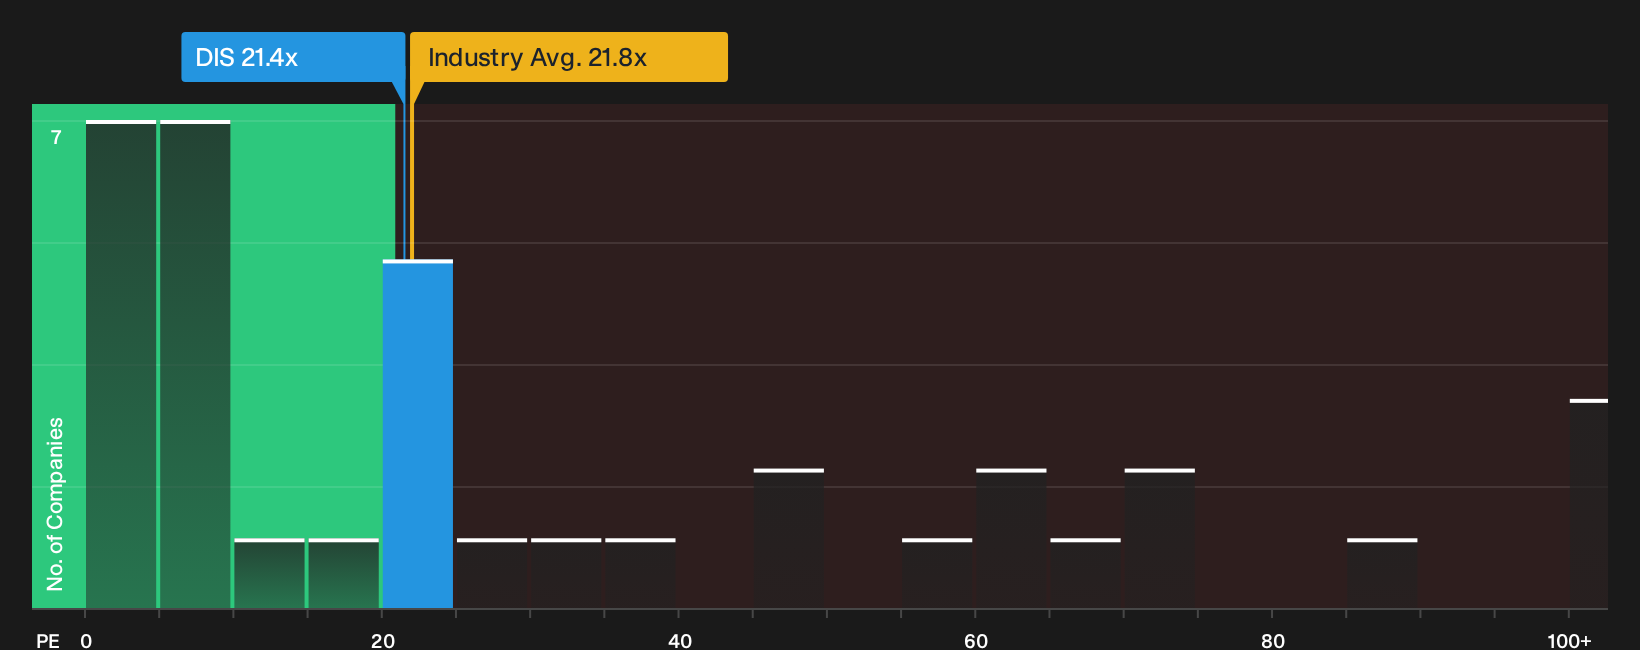
The P/E ratio suits Walt Disney because earnings still drive how many investors frame the value of a large media and entertainment group. On this lens, the stock trades on roughly 21.4x earnings, which is close to the Entertainment sector average of about 21.8x. Against that broad backdrop, the headline multiple does not look stretched.
The fair P/E that blends Disney’s size, industry, margins and risk profile comes out higher at about 26.6x. That is a sizeable gap to the current 21.4x and indicates that the shares are priced at a discount relative to what this framework suggests. Compared with a peer group that averages roughly 55.0x, the company also sits at a much lower earnings multiple, which further supports the idea that the stock appears cheap on this measure.
On the P/E yardstick, Walt Disney appears undervalued, with the current multiple sitting well below both the tailored fair ratio and the broader peer group.
See what the numbers say about this price — find out in our valuation breakdown.
The Walt Disney Narrative: What Would Justify Today's Price?
For Walt Disney, Simply Wall St Narratives act as the missing link between the valuation puzzle above and the real world assumptions that would need to hold for the current share price to make sense. They translate a single output from a ratio or model into a concrete future story about growth, margins and earnings so you can see exactly what that number relies on and then track whether the real business is following that script, all on Disney's Community page.
One of the top community narratives on Walt Disney: 21% undervalued
"Disney is a high-quality and innovative company with a proven record of benefitting from disruption, which has been consistently priced as if it were an aging dinosaur..."
Read one of the top narratives on Walt Disney
Do you think there's more to the story for Walt Disney? Head over to our Community to see what others are saying!
The Bottom Line
On the numbers, Walt Disney looks roughly in line with its Discounted Cash Flow (DCF) intrinsic value, while trading on an earnings multiple that screens as undervalued versus both its tailored fair P/E and peers. That mix points to a stock where most of the easy mispricing may sit in sentiment and earnings expectations rather than in the cash flow model. The crux for investors now is whether Disney can turn its content and streaming assets into durable, growing earnings without legal disputes and execution risk eroding that apparent discount.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com