


COMPASS Pathways (CMPS) Stock Looks Above Fair Value While Its 176% Return Stays Strong
COMPASS Pathways has seen a sharp share price climb over the past year, yet current valuation checks describe a mixed picture while traditional market multiples screen the stock as expensive. For investors looking at COMPASS Pathways today, the puzzle is how to weigh that strong recent return against a broader set of signals that do not clearly point to either a bargain or an obvious bubble.
- The 1 year return of about 176% suggests sentiment around COMPASS Pathways has become very optimistic in a short span of time.
- Positive Phase 3 data for COMP360 and early preparation for potential provider training can support expectations for future revenue. At the same time, regulatory risk and execution around a possible launch may still weigh on how much investors are willing to pay today.
- A value score of 3 signals a mixed picture rather than a clear bargain or clear overvaluation when all the valuation checks are viewed together.
The issue now is whether the recent surge in COMPASS Pathways shares already prices in the key upside scenarios that investors are focused on.
Scan beyond COMPASS Pathways' 176% 1 year surge and compare it with other stocks flagged in our 32 high quality undervalued stocks for a different mix of momentum and valuation.
Does COMPASS Pathways Look Pricey on Book Value?
P/B is a decent sanity check for COMPASS Pathways because investors are effectively paying for an asset base that is still pre commercial and heavily tied to intellectual property and trial data rather than steady earnings.
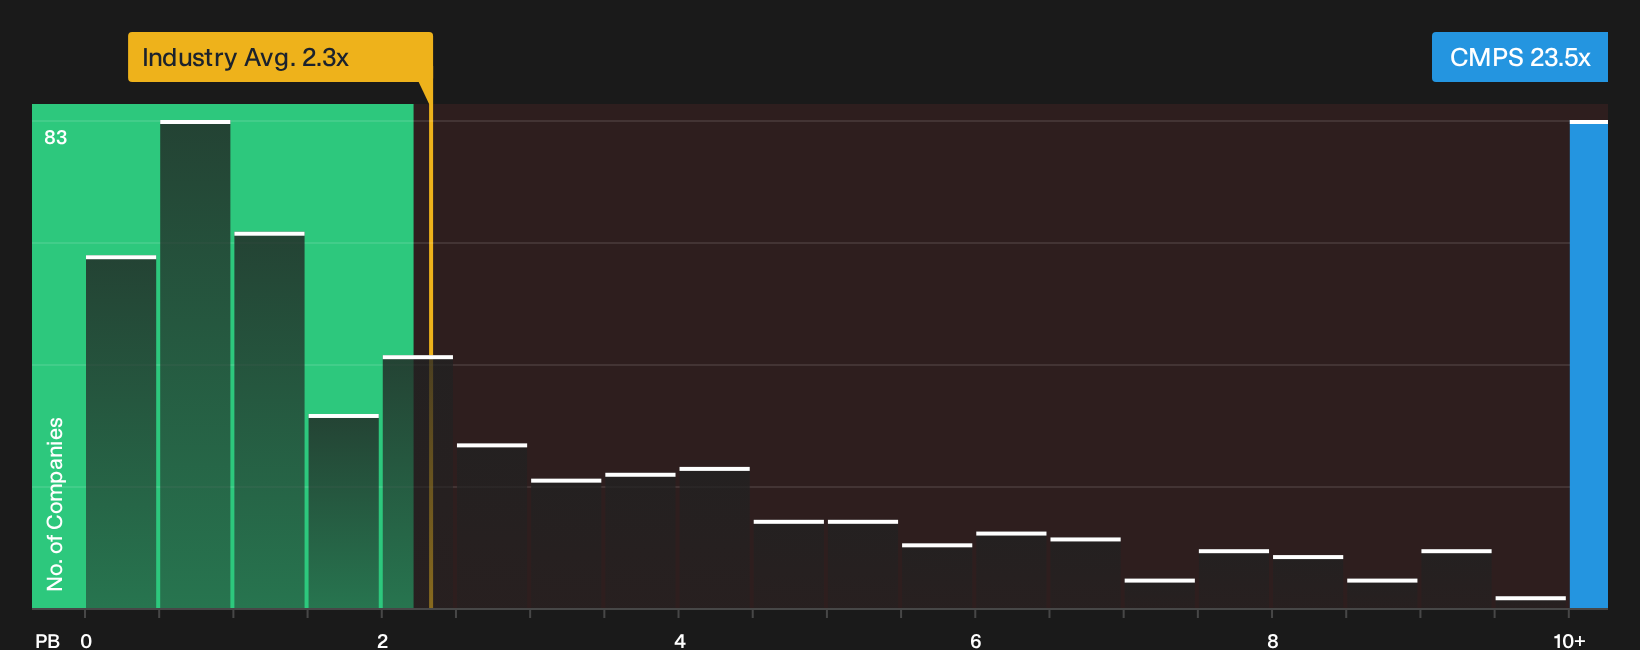
On this measure, COMPASS Pathways trades at about 23.5x book value, compared with roughly 2.3x for the wider biotech industry and a peer average near 42.2x. The stock therefore sits well above the sector norm but below some closer comparables that the market prices more aggressively on this yardstick. This remains a rich premium to the typical biotech balance sheet.
On a pure P/B basis, COMPASS Pathways screens as overvalued relative to the broader biotech group even after allowing for sector specific enthusiasm.
See what the numbers say about this price — find out in our valuation breakdown.
The COMPASS Pathways Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for COMPASS Pathways aim to close the gap between that valuation puzzle and the assumptions sitting underneath it by spelling out what kind of future for growth, margins and earnings would be needed for the share price to end up meaningfully higher or lower than it is today on the Community page. Where a single ratio or model points to one number, Narratives unpack the future scenario that number rests on so you can watch how reality compares over time.
Community views on COMPASS Pathways sit far apart, with some investors focused on a long runway for COMP360 and others fixated on execution risk and dilution.
Bull case: 41% undervalued
"Years of preparatory work with strategic collaborations, medical science liaisons and interventional centers, combined with the decision to pull forward marketing, sales force design and market access activities, positions COMPASS to convert any approval into earlier prescription volume…"
Read the full Bull Case to see why COMPASS Pathways could be undervalued
Bear case: 10% overvalued
"Although completion of enrollment in the COMP006 Phase III trial and an FDA supported plan for a rolling NDA could shorten the path to potential approval and earlier revenue, the company still relies heavily on successful 26 week outcomes from both Phase III trials…"
Read the full Bear Case to see why COMPASS Pathways could be overvalued
Do you think there's more to the story for COMPASS Pathways? Head over to our Community to see what others are saying!
The Bottom Line
On current market multiples, COMPASS Pathways screens as overvalued, especially on P/B, which asks you to pay a steep price for a still pre commercial asset base. The mixed value score underlines that this is not a clean call either way and that simple screens do not fully settle the argument. What really decides the outcome from here is whether COMP360 can convert regulatory progress into a durable commercial franchise without heavy dilution or execution missteps that challenge the premium being asked today.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com