


Accenture (ACN) Could Be 39% Undervalued Following Its MotoGP Streaming Deal
Accenture (ACN) just landed a new role inside live motorsport. MotoGP has hired the consulting group to build a next generation direct to fan streaming platform that unifies its key race properties.
For investors, the MotoGP win lands at an interesting moment for Accenture. The 1-day share price return of 3.37% to US$183.90 comes after a year-to-date share price decline of 29.26% and a 1-year total shareholder return down 20.34%. Short-term momentum is picking up, while longer-term performance remains weak as the market reassesses both growth opportunities and risks.
Scan how Accenture’s MotoGP deal fits into a wider push toward digital platforms by reviewing a curated set of 89 AI infrastructure stocks.
Accenture appears to be a high-quality operator winning complex work such as MotoGP’s streaming overhaul. After a share price slide and modest rebound, the key question is whether that quality is being offered at a sensible price or not yet.
Most Popular Narrative: 38.9% Undervalued
The most followed narrative on Accenture pegs fair value at $301 per share, which is well above the last close of $183.90. That sets up a clear gap between market pricing and what this framework thinks the business is worth.
My core view: ACN is not a broken company, it is a strong company going through a credibility reset. The market is asking whether Accenture can convert AI from a threat into a growth engine. Based on its enterprise relationships, AI Refinery platform, NVIDIA partnership, sovereign/private AI positioning, and quantum-security work, I think Accenture is one of the better-positioned legacy services firms. However, near-term demand weakness, federal spending pressure, AI-led workforce disruption, and slower bookings make the short-term case less clean.
The valuation story here hinges on how long Accenture can keep free cash flow near current levels. The narrative leans heavily on bookings, margins, and AI-driven project work to justify that $301 figure. Curious which mix of earnings power, contract wins, and profitability assumptions has to line up for that to hold.
Result: Fair Value of $301 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the thesis breaks if AI project wins fail to offset pressure on traditional consulting work and if restructuring costs continue to squeeze Accenture’s margins.
Find out about the key risks to this Accenture narrative.
Another View on Accenture’s Valuation
Where the narrative-driven model points to a fair value of $301, the Simply Wall St DCF model tells a cooler story. On that framework, Accenture at $183.90 trades above an estimated future cash flow value of $156.88, which screens as overvalued rather than cheap. For anyone weighing both views, the key question is which cash flow path feels more realistic over the next decade.
Look into how the SWS DCF model arrives at its fair value.
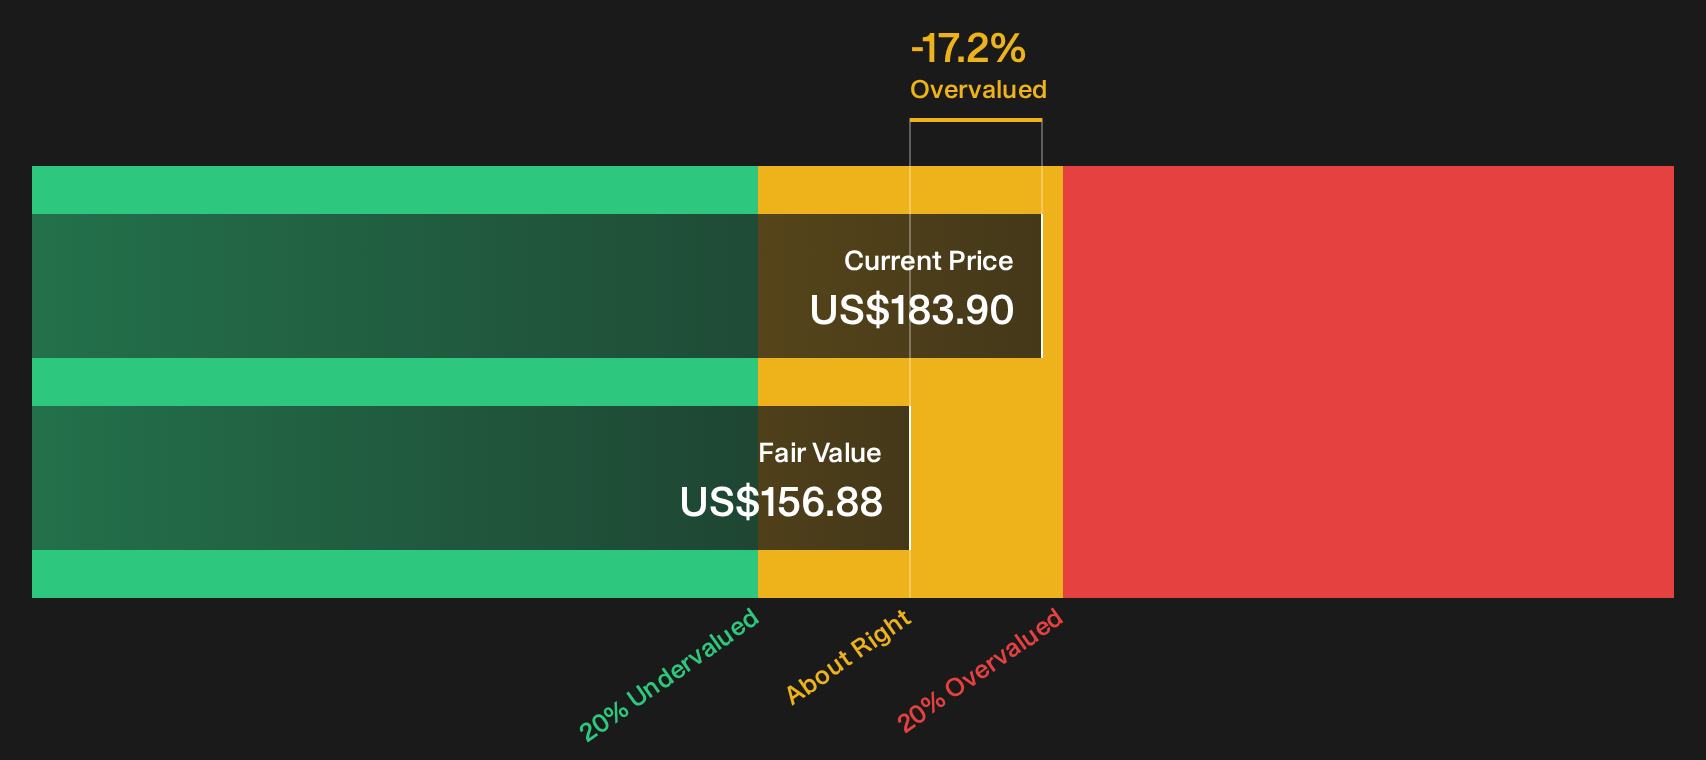
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Accenture for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Accenture in this piece may feel mixed. Move quickly, check the underlying numbers for yourself, and weigh those 4 key rewards.
Looking for more investment ideas beyond Accenture?
If Accenture has you thinking harder about pricing power and resilience, use that momentum. Line up a few fresh candidates and pressure test your thesis.
Miss these ideas and you risk keeping capital parked in the same tired watchlist instead of giving your money a chance to work harder.
- Target resilience first by scanning a 11 resilient stocks with low risk scores that can help you focus on businesses with more defensive profiles.
- Hunt for value by reviewing a 32 high quality undervalued stocks that highlights companies with strong fundamentals trading at more modest prices.
- Prioritize balance sheet strength by checking a list of solid balance sheet and fundamentals (23 results) that filters for firms with healthier financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com