


Can ConnectOne Bancorp (CNOB) Stay Reasonable After An 87% Run?
ConnectOne Bancorp stock has put up a strong 3 year run, yet current valuation checks still frame it as inexpensive on several fronts. For investors, the question is whether a share price that has already moved higher now properly reflects that backdrop of solid historical returns and a market view that leans cheap.
- Over the past 3 years, ConnectOne Bancorp has returned 87.4%, which puts recent short term pullbacks into context for anyone looking at the longer chart.
- For a regional bank, the key support for the equity story may come from how consistently it can compound loan and fee income. Credit quality and funding costs remain the main threats to any valuation case.
- The broader checklist of valuation metrics points to ConnectOne Bancorp screening cheap overall, with the value score of 5 suggesting the stock looks undervalued on most of the tests applied.
The stock's next move may depend on whether that gap between a strong multi year share gain and a still cheap profile on the valuation screens can persist.
Compare ConnectOne Bancorp's run with a curated group of other potentially underpriced opportunities by scanning 32 high quality undervalued stocks built around quality and valuation discipline.
Is ConnectOne Bancorp Still Cheap on Earnings?
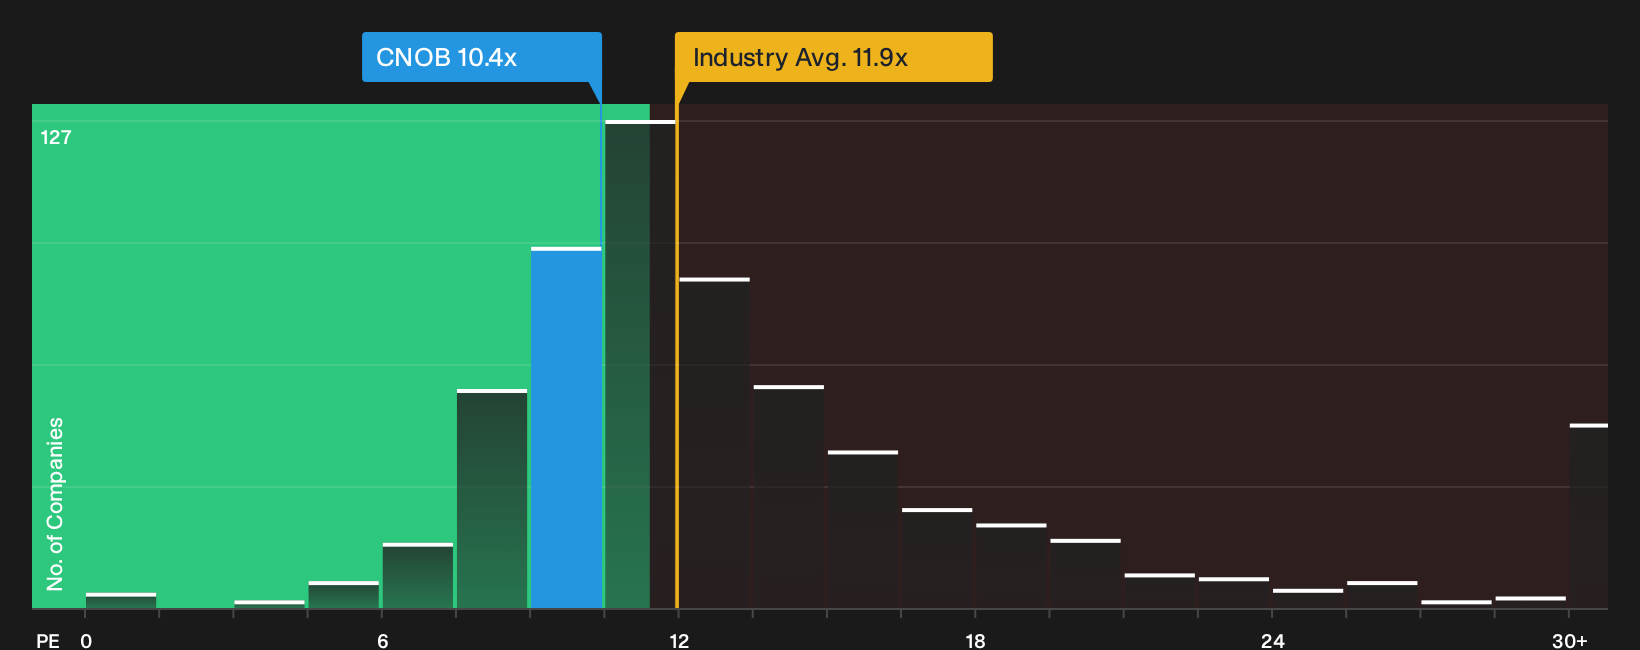
P/E tends to be the cleanest snapshot for a lender like ConnectOne Bancorp because earnings sit at the center of how investors usually value banks. On that yardstick, the stock trades on roughly 10.4x earnings, using the latest ratio provided. The broader Banks group sits nearer 11.9x, so you are paying a lower earnings multiple than the sector average for ConnectOne Bancorp.
The comparison with closer peers is even more striking. Similar companies in the peer set trade around 15.7x, while a fair P/E for ConnectOne Bancorp based on its own profile is estimated at 12.8x. That is a meaningful gap between what the market currently pays and what the tailored fair multiple suggests could be reasonable for this business.
On the P/E yardstick, ConnectOne Bancorp stock currently screens as undervalued relative to both its peer group and its own estimated fair multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The ConnectOne Bancorp Narrative: What Would Justify Today's Price?
ConnectOne Bancorp's valuation picture raises a clear question for anyone holding or watching the stock. Narratives on Simply Wall St's Community page turn that puzzle into specific assumptions about future growth, profitability and earnings that would need to play out for the current share price to look either too low or too high. Instead of stopping at a single model output, they spell out the future that number rests on so you can see over time whether reality is lining up with the implied story.
Add your take on ConnectOne Bancorp's valuation story by posting a Narrative that spells out your view on where its growth, margins and execution go from here. Put a number driven case on the stock and track how it holds up as fresh results and market reactions come through, and be one of the first voices in the Simply Wall St community shaping that discussion.
Do you think there's more to the story for ConnectOne Bancorp? Head over to our Community to see what others are saying!
The Bottom Line
On current market multiples, ConnectOne Bancorp still screens as undervalued, with investors paying less for each dollar of earnings than for many peers. The broader valuation checks look supportive, which gives the discount some fundamental backing rather than leaving it as a purely sentiment driven gap. The real hinge from here is whether the bank can keep credit quality and funding costs in a range that lets earnings hold up, so the market is willing to close some of that valuation gap instead of treating it as a value trap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com