


Ferrari (BIT:RACE) Stock May Still Look Fully Priced On Monza Setbacks
Ferrari stock has delivered a very strong 5 year run, yet the latest checks still flag it as expensive rather than a clear bargain. With a low value score and an overvalued signal on market multiples, investors are being asked to pay up for the brand and its future earnings story.
- A roughly 101% gain over 5 years means long term holders have already seen a sizeable payoff, which raises the bar for any new entry point.
- Ongoing share buybacks and the broader Ferrari brand strength can support sentiment, while any disappointment around execution in Formula 1 or road-car performance may challenge the premium attached to the shares.
- The valuation checks show a low score, so Ferrari does not screen as a clear bargain on broader measures, with only 0 of 6 tests passing on value.
The issue now is whether Ferrari’s current premium is still reasonable given what the market is pricing in after such a strong multi year climb.
Spot under-the-radar alternatives to Ferrari's rich valuation by scanning our screener containing 619 high quality undiscovered gems that have stronger fundamentals and less demanding expectations reflected in their prices.Has Ferrari Run Too Far on Earnings?
For a branded luxury manufacturer like Ferrari, the P/E ratio is a concise way to show how much investors are paying for each euro of earnings.
Ferrari trades on a P/E of about 41.9x. The broader auto industry sits near 14.2x and the peer group average is roughly 20.9x, so the stock carries a hefty premium to both the sector and direct rivals. On a more tailored view that blends Ferrari’s size, margins and risk profile, a fair P/E multiple comes out at about 22.3x. That is roughly half of where the shares change hands today, which suggests that buyers are already accepting a rich price tag for the earnings stream.
Despite recent scrutiny of Ferrari’s Formula 1 performance and the pressure that creates around execution, the market is still willing to assign a luxury-level multiple that reflects significant confidence in the franchise.
On the P/E lens alone, Ferrari stock appears clearly overvalued relative to both its tailored fair multiple and traditional auto benchmarks.
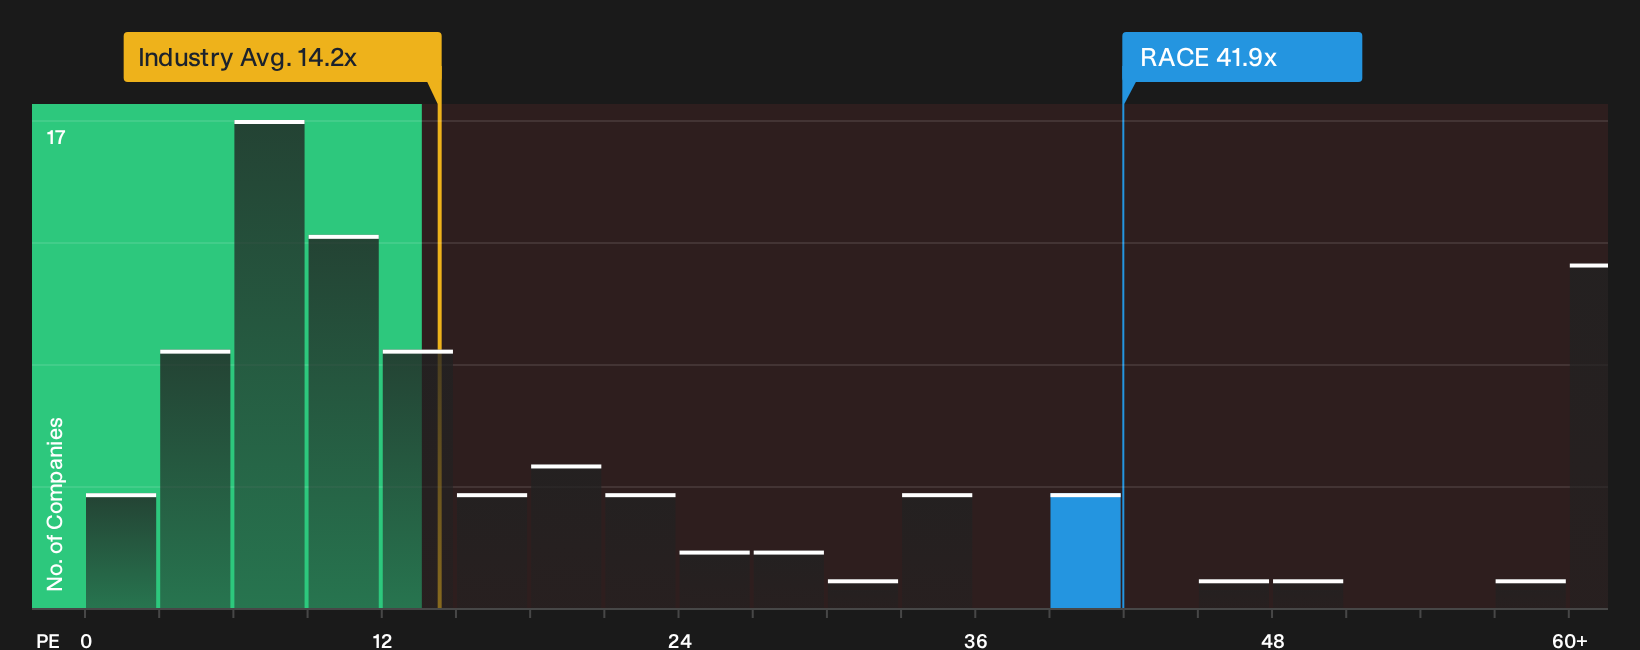
See what the numbers say about this price — find out in our valuation breakdown.
The Ferrari Narrative: What Would Justify Today's Price?
Ferrari’s valuation puzzle invites a clear next step: spell out what kind of future growth, profitability and earnings power would actually need to show up for today’s share price to prove too high or too low. Simply Wall St Narratives on Ferrari’s Community page are built for that job, since each one lays out the assumptions behind its view of fair value so you can track those expectations against the company’s results as they are reported.
Ferrari attracts sharply different narratives, with some community members arguing the premium is backed by durable demand while others see the valuation as stretched on more conservative models.
Bull case: 8% undervalued
"Ferrari's disciplined restriction of vehicle production and its resulting backlog (orders stretching well into 2027) underscores enduring demand, pricing power, and exclusivity..."
Read the full Bull Case to see why Ferrari could be undervalued
Bear case: 46% overvalued
"As you can see from the above Ferrari seems to be overvalued, using DCF, because even on the higher end of the simulations its DCF estimated fair value is still very low compared to the company's price..."
Read the full Bear Case to see why Ferrari could be overvalued
Do you think there's more to the story for Ferrari? Head over to our Community to see what others are saying!
The Bottom Line
Ferrari trades on market multiples that point to an overvalued stock, with investors clearly willing to pay a luxury price for each euro of earnings. The crux now is whether that premium can be sustained by execution in core models and Formula 1, rather than any further stretch in the P/E. For new capital, the key question is simple: Does Ferrari’s brand and earnings power justify paying far above sector norms, or does the current valuation already bake in most of the good news you are hoping for?
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com