


Chevron (CVX) Stock Looks Discounted Even After A 170% Run
Chevron stock is trading near record territory after a powerful 5 year run, yet both the Discounted Cash Flow (DCF) intrinsic value estimate and market based multiples currently point to the shares being undervalued relative to that track record.
- Chevron has returned 170.3% over the past 5 years. This puts recent valuation checks front and center for anyone considering fresh capital today.
- Rising oil prices, heightened geopolitical risk and projects such as the Venezuela expansion and the Microsoft power partnership can support cash flow expectations. However, any reversal in energy prices or disruption to major projects may weigh heavily on what investors are willing to pay.
- The stock screens as undervalued on both a Discounted Cash Flow (DCF) intrinsic value estimate and earnings multiples. At the same time, a mixed overall value profile, with a value score of 3, suggests neither a clear bargain nor a clear overpricing.
The issue now is whether Chevron's current share price already fairly reflects this mix of strong recent returns, supportive cash generation drivers and the risks tied to energy prices and geopolitics.
Spot 32 high quality undervalued stocks that, like Chevron, combine strong long term returns with valuations that still screen as discounted on both cash flow and earnings multiples.Is Chevron a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here values Chevron on the cash it is expected to generate for shareholders over time. On the latest twelve month numbers, the business produced free cash flow of about $27.2b, and the projections assume broadly growing cash flows rather than a sharp decline or step change.
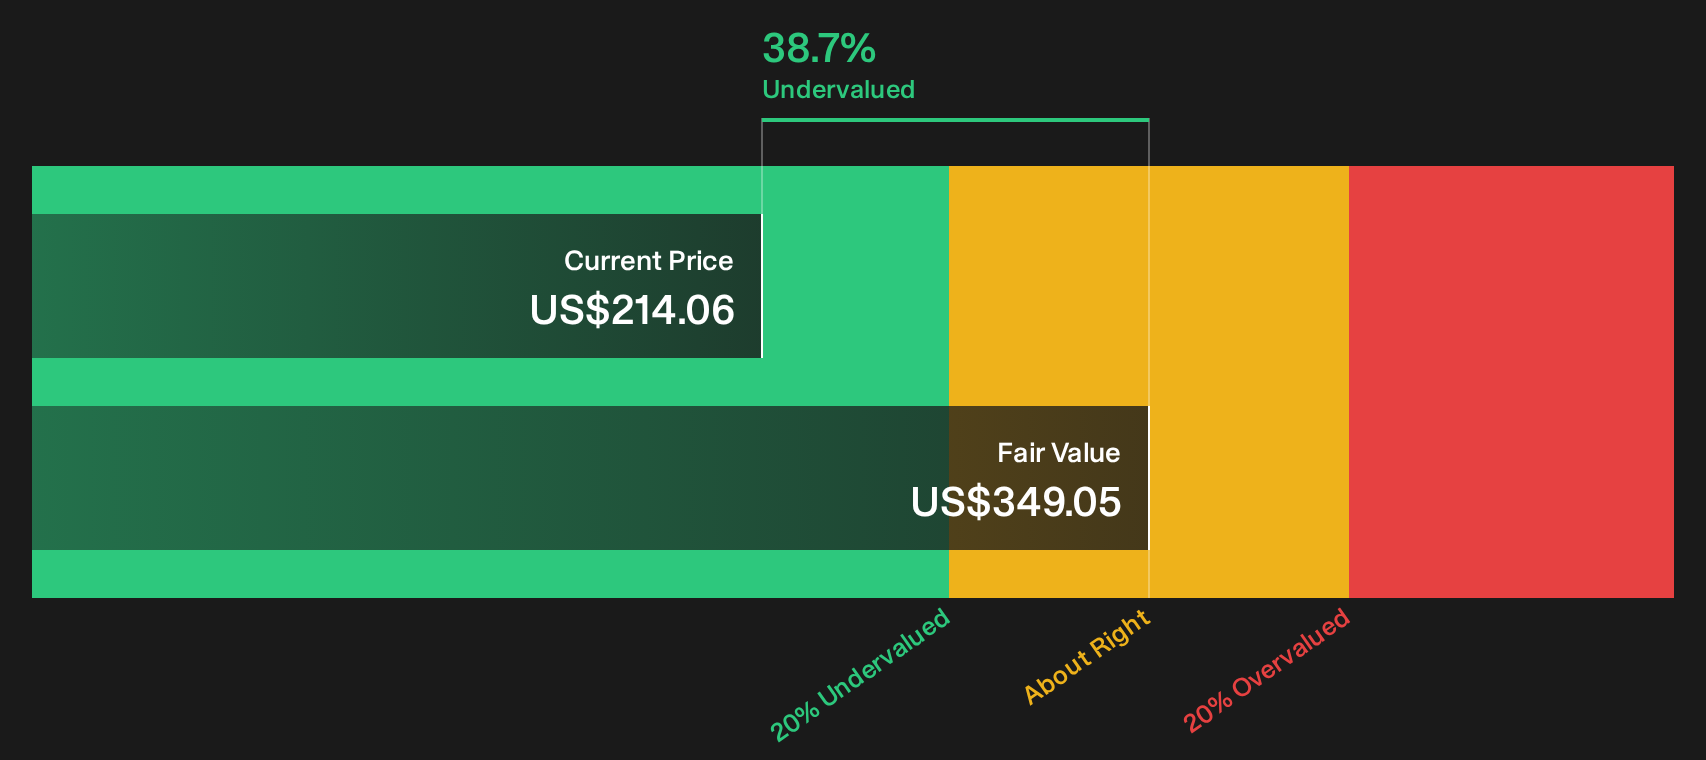
Feeding those cash flow estimates into the 2 Stage Free Cash Flow to Equity framework gives an intrinsic value of about $349 per share. That figure indicates the stock trades at roughly a 38.7% discount to this cash based estimate. The recent surge in oil prices after renewed US and Iran conflict helps explain why the market price has moved higher; however, the model still points to a gap between Chevron’s cash flow profile and where the shares change hands today.
On this DCF view, Chevron appears undervalued relative to the cash the business is expected to generate.
Our Discounted Cash Flow (DCF) analysis suggests Chevron is undervalued by 38.7%. Track this in your watchlist or portfolio, or discover 32 more high quality undervalued stocks.
Does Chevron Look Undervalued on Earnings?
P/E works well for Chevron because earnings are a primary focus for an integrated oil and gas group with sizeable, relatively mature operations.
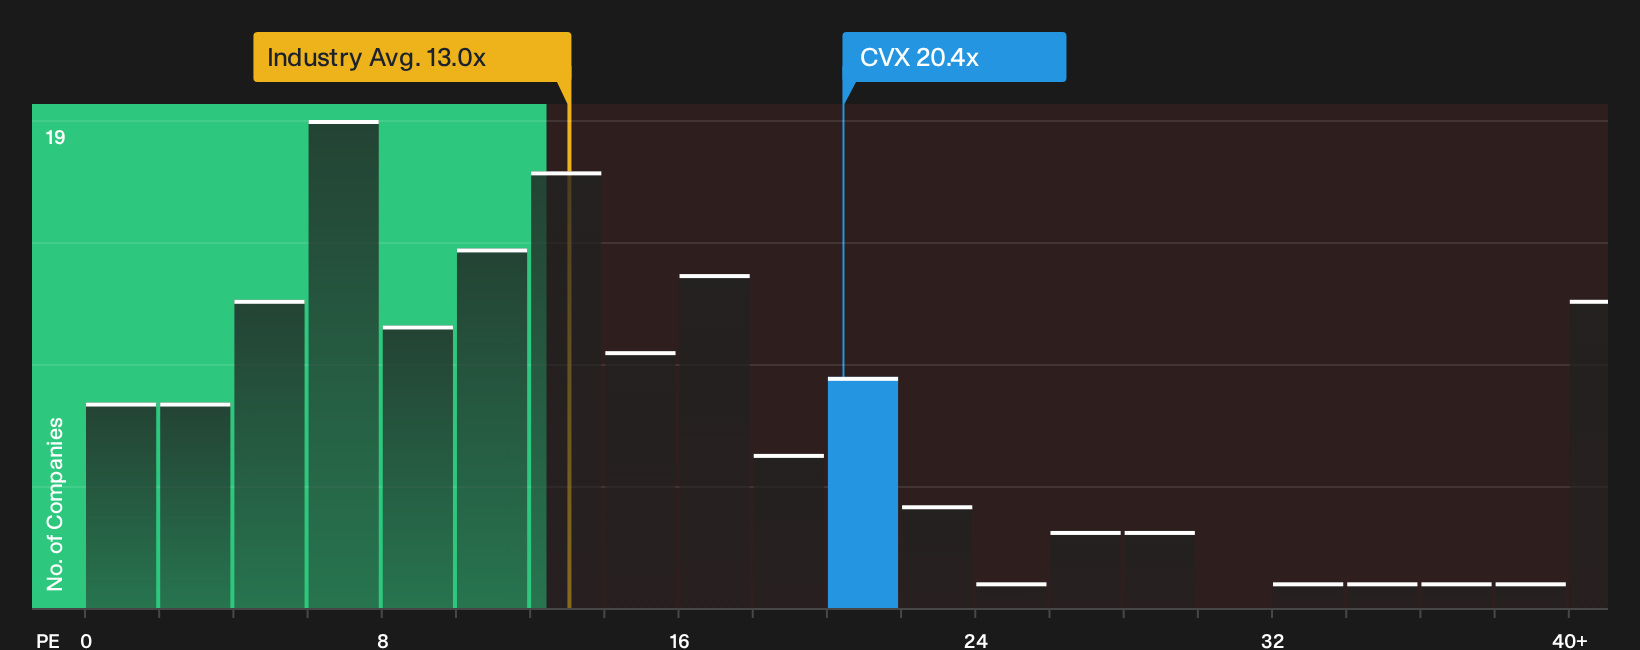
On this lens, Chevron trades on a P/E of about 20.4x. That sits above the broader oil and gas industry average of roughly 13.0x and also above the peer group average of about 17.4x. The modelled fair P/E for Chevron is higher again, at around 24.8x. This reflects what investors might typically pay given its scale, profitability profile and risk mix.
The current P/E is therefore below that fair ratio, even though it carries a premium to the wider sector and direct peers. For investors comparing Chevron to its own fundamentals rather than just the group it sits in, the multiple still points to a valuation that has not fully closed that gap.
On the P/E yardstick, Chevron appears undervalued relative to the earnings multiple the model suggests would be justified.
See what the numbers say about this price — find out in our valuation breakdown.
The Chevron Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Chevron's valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price on the Community page. Instead of one neat figure from a ratio or model, Narratives map the underlying assumptions so you can watch how Chevron's actual progress lines up with the scenario you have in mind.
Have a number driven view on whether Chevron's Venezuela expansion and Microsoft power partnership really support today's valuation range. Share a Narrative on Chevron to add your voice to the Simply Wall St community and track how your thesis holds up as new results and news are released.
Do you think there's more to the story for Chevron? Head over to our Community to see what others are saying!
The Bottom Line
Chevron screens as undervalued on both the Discounted Cash Flow (DCF) intrinsic value estimate and earnings multiples, yet the overall value profile remains mixed rather than outright compelling. For you as an investor, the key question is whether that DCF gap and P/E discount reflect mispricing or simply the market baking in real execution and commodity risks. The crux from here is how sustainably Chevron can convert its project pipeline and current energy pricing into resilient cash flows without major disruption. That single assumption tends to decide whether this current discount is an opportunity or a warning.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com