


Cboe Global Markets (CBOE) Shares Slid, So What Is Drawing Attention Now?
Cboe Global Markets (CBOE) has drawn attention after a period of weaker recent share performance, with the stock down over the past week, month, and past 3 months despite a positive year-to-date return.
Recent trading suggests that momentum in Cboe Global Markets is fading in the short term, with the share price down 2.24% over one day and 5.81% over the past week. This comes even though the year-to-date share price return is 13.27% and the 5-year total shareholder return is 142.79%.
Scan how Cboe Global Markets stacks up against other potential opportunities by comparing it with a hand-picked 31 high quality undervalued stocks.
Cboe Global Markets has given back some recent gains after a strong multi year run, which puts a simple question in front of you: Is the meaningful upside still ahead, or has most of it already been earned at this price?
Most Popular Narrative: 16.2% Overvalued
Cboe Global Markets is trading at a last close of $281.04, while the most followed narrative anchors fair value at about $241.95 based on its own model inputs.
The DDM values are lower than DCF as they only capture dividend returns, not the full value of retained earnings and business growth. Based on this comprehensive analysis using appropriate risk-adjusted discount rates, CBOE appears undervalued when using WACC-based DCF methodology.
Want to see why one valuation framework points to meaningful upside while another pins the value much closer to today’s price? The core assumptions around future cash generation, reinvestment, and long run growth rates are doing all the heavy lifting in this narrative. If you want to understand how those moving parts translate into a single fair value line for Cboe Global Markets, the full write up lays out every step.
Result: Fair Value of $241.95 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, this Cboe Global Markets narrative leans heavily on optimistic growth and discount rate assumptions, which could break if trading volumes or regulation move against it.
Find out about the key risks to this Cboe Global Markets narrative.
Another View: Cboe Global Markets Through Earnings Multiples
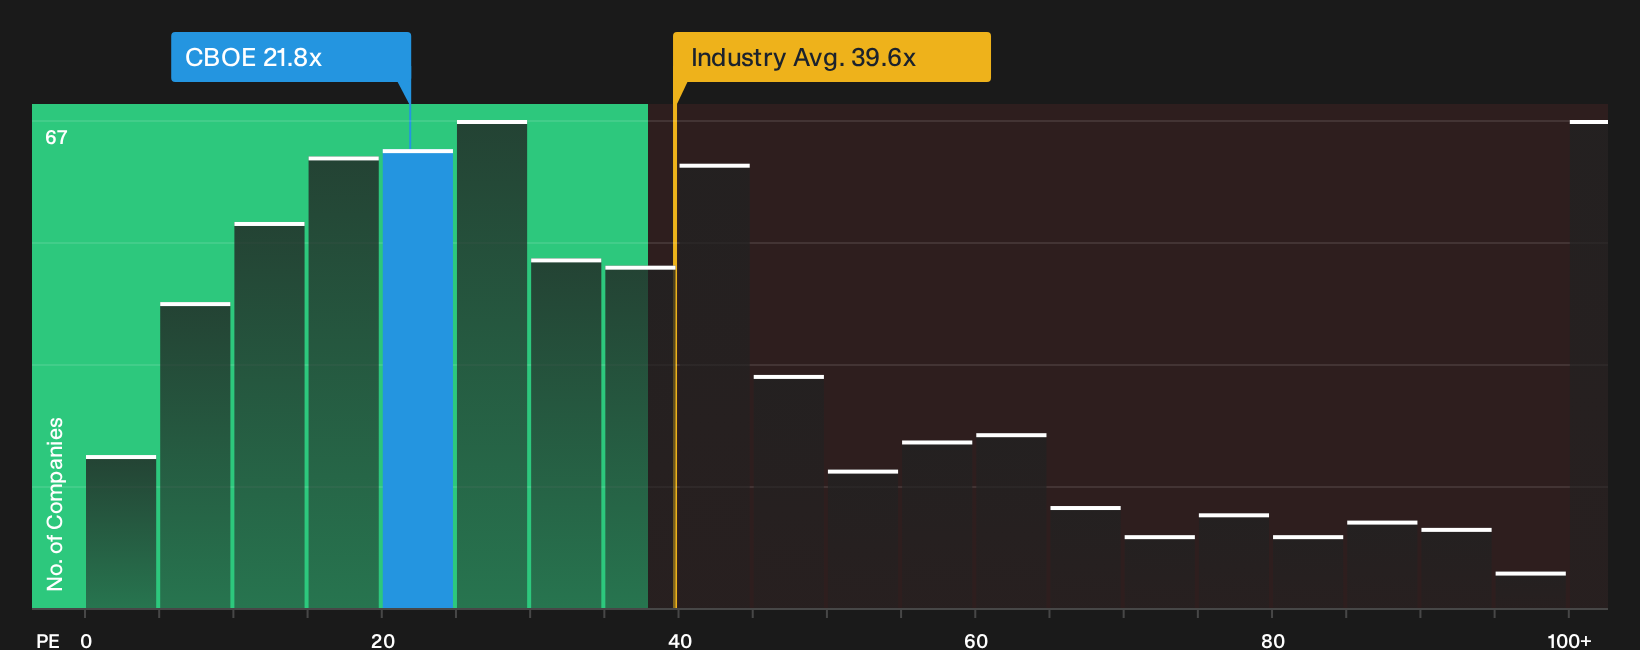
The narrative model flags Cboe Global Markets as 16.2% overvalued around a fair value of $241.95. A simple earnings lens tells a different story. The stock trades on a 21.8x P/E, which is lower than both the US Capital Markets industry at 39.6x and the peer average at 27.2x.
That discount sounds helpful, yet the fair ratio sits at 14.7x, which implies investors are already paying a premium to where the P/E could drift if sentiment cools. Is the stronger growth and high 24.1% return on equity enough to justify staying above that fair ratio, or does this gap leave less room for error at $281.04?
To pressure test that earnings multiple against a fuller valuation breakdown, including how it ties back to cash flows and quality metrics, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages across Cboe Global Markets valuations can create a strong pull in either direction, so it may be important to move quickly and pressure test the numbers yourself. To see exactly what investors are optimistic about right now, review the 3 key rewards
Looking for more Cboe Global Markets style investment ideas?
Sticking with only one opportunity can mean overlooking other stocks that better fit your goals. Use the Simply Wall St screener to quickly surface ideas that match your risk, income, and quality preferences.
- Target resilient balance sheets and robust fundamentals by scanning a focused list of solid balance sheet and fundamentals (23 results) that filters for financial strength and staying power.
- Hunt for mispriced opportunities by running through a curated 31 high quality undervalued stocks that highlights companies where quality and current pricing appear out of sync.
- Spot potential long term compounders early by checking a hand picked 15 high quality undiscovered gems before attention and capital crowd in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com