


Siemens Healthineers (XTRA:SHL) Stock Could Trade At A Discount After A 28% Five Year Slide
Siemens Healthineers stock has delivered a decline of 28.4% over the past five years, yet the valuation checks currently suggest the shares lean cheap rather than fully priced in. That gap between weak long term returns and a stronger value read is what investors now have to weigh.
- The share price performance over five years is down 28.4%, which signals that expectations embedded in the stock have already reset meaningfully.
- Expanding capacity in areas like MRI and molecular imaging can support longer term earnings power. However, execution risk around large capital projects and product cycles may still weigh on how much of that potential is reflected in the share price.
- The broader valuation work points to Siemens Healthineers trading on the cheap side, with a high value score of 5 indicating it screens undervalued on most checks.
The issue now is whether Siemens Healthineers is priced as a value trap after years of underperformance or as a discounted entry point for patient shareholders.
Spot opportunities that echo the Siemens Healthineers setup by scanning our curated list of 184 high quality undervalued stocks.Is Siemens Healthineers a Bargain on Earnings?
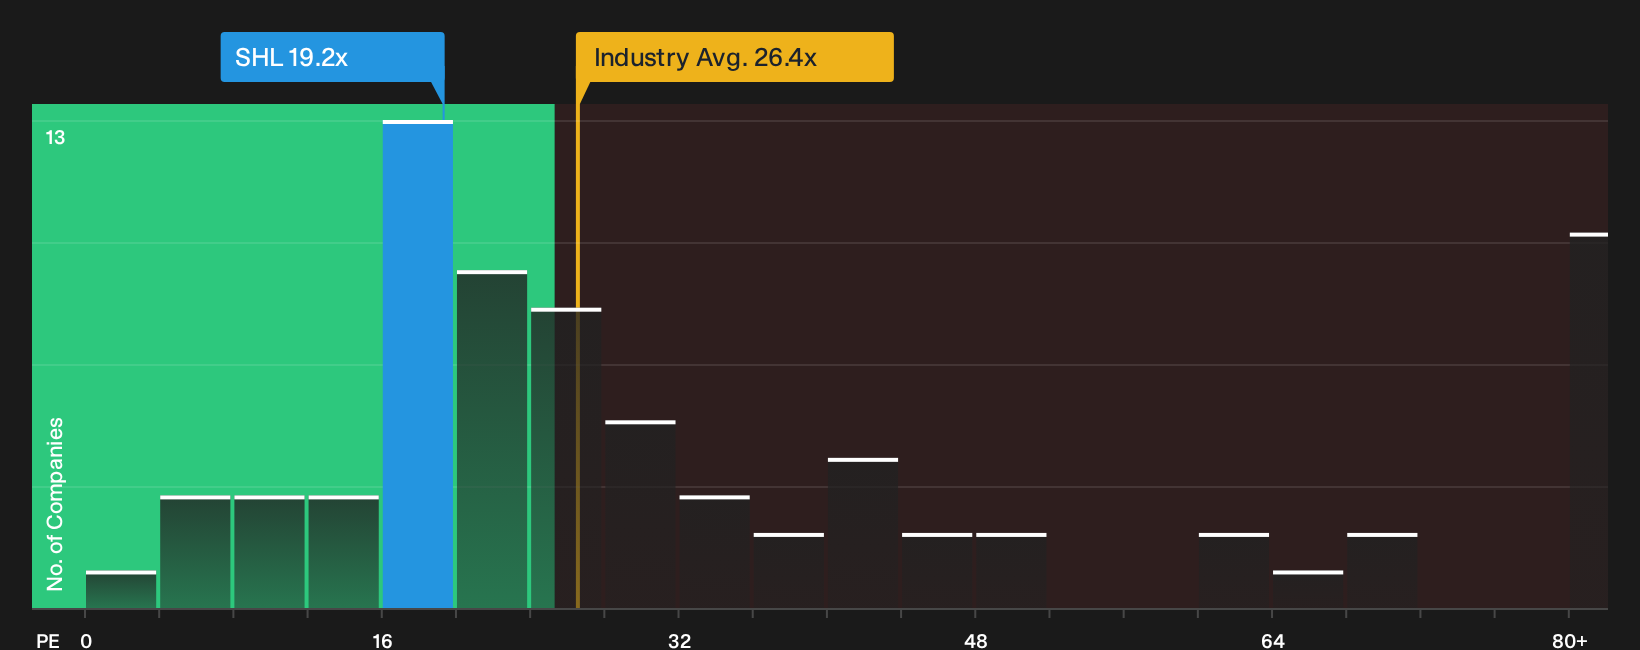
The P/E ratio suits Siemens Healthineers because earnings remain a key anchor for how investors assess medical equipment businesses. On that yardstick, the shares trade on about 19.2x earnings, which is almost in line with the 19.3x peer average and sits below the wider Medical Equipment sector on 23.2x. That places the stock in the middle of the pack against direct competitors, but at a discount to the broader industry.
The fair P/E multiple implied by the valuation model is about 24.9x, which is materially higher than where Siemens Healthineers changes hands today. Despite recent news around MRI and molecular imaging capacity expansions, the market is still pricing the business at a lower earnings multiple than this tailored fair ratio suggests.
On this P/E yardstick, Siemens Healthineers appears undervalued relative to what the model implies the business could reasonably justify.
See what the numbers say about this price — find out in our valuation breakdown.
The Siemens Healthineers Narrative: What Would Justify Today's Price?
Siemens Healthineers' valuation puzzle only really comes into focus once you spell out the future that would need to unfold for today’s price to be too low or too high. Simply Wall St Narratives draw a straight line from the current P/E and model outputs to those underlying assumptions on growth, profitability and earnings, so you can see the specific future they rely on and track whether reality is moving in that direction.
The community is looking at Siemens Healthineers through two very different lenses, with one camp focused on margin upside and the other fixated on Diagnostics risk.
Bull case: 16% undervalued
"Expansion of long-term Value Partnerships with hospitals and healthcare systems is shifting the business mix toward higher recurring revenue streams. These help stabilize earnings, improve revenue visibility, and support sustained operating margin expansion…"
Read the full Bull Case to see why Siemens Healthineers could be undervalued
Bear case: 6% overvalued
"The need to keep investments high in advanced modalities like Photon Counting CT, interventional MRI and new angiography systems may cap near term margin gains at the group level. Equipment mix and R&D may weigh on net margins…"
Read the full Bear Case to see why Siemens Healthineers could be overvalued
Do you think there's more to the story for Siemens Healthineers? Head over to our Community to see what others are saying!
The Bottom Line
On today's numbers, Siemens Healthineers screens as undervalued on earnings, with the tailored P/E framework implying more headroom than the current market multiple reflects. That discount only matters if the group can turn capacity expansions and Value Partnerships into durable margin strength, rather than letting capital intensity and Diagnostics concerns erode returns. The crux for investors is whether Siemens Healthineers deserves to trade closer to its implied fair P/E or whether the present gap is the right price for execution risk and a mixed recent track record.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com