


Adobe (ADBE) Emerges As A Key Vendor In An AI MarTech Market Set To Triple
- Adobe (NasdaqGS:ADBE) is identified as a key vendor in the rapidly expanding global AI MarTech sector.
- The AI MarTech market is forecast to nearly triple in size by 2031, supported by agentic AI and privacy-first tools.
- Adobe is highlighted for its role in agentic AI, privacy-first personalization, and platform consolidation within marketing technology.
- This new focus on Adobe's AI MarTech position sits alongside wider industry and competitive shifts our research has uncovered. We have also spotted 4 other big wins worth knowing about at Adobe.
This surge in AI-driven marketing tools reaches well beyond Adobe, so it is worth scanning other companies leveraged to AI infrastructure via 89 AI infrastructure stocks.
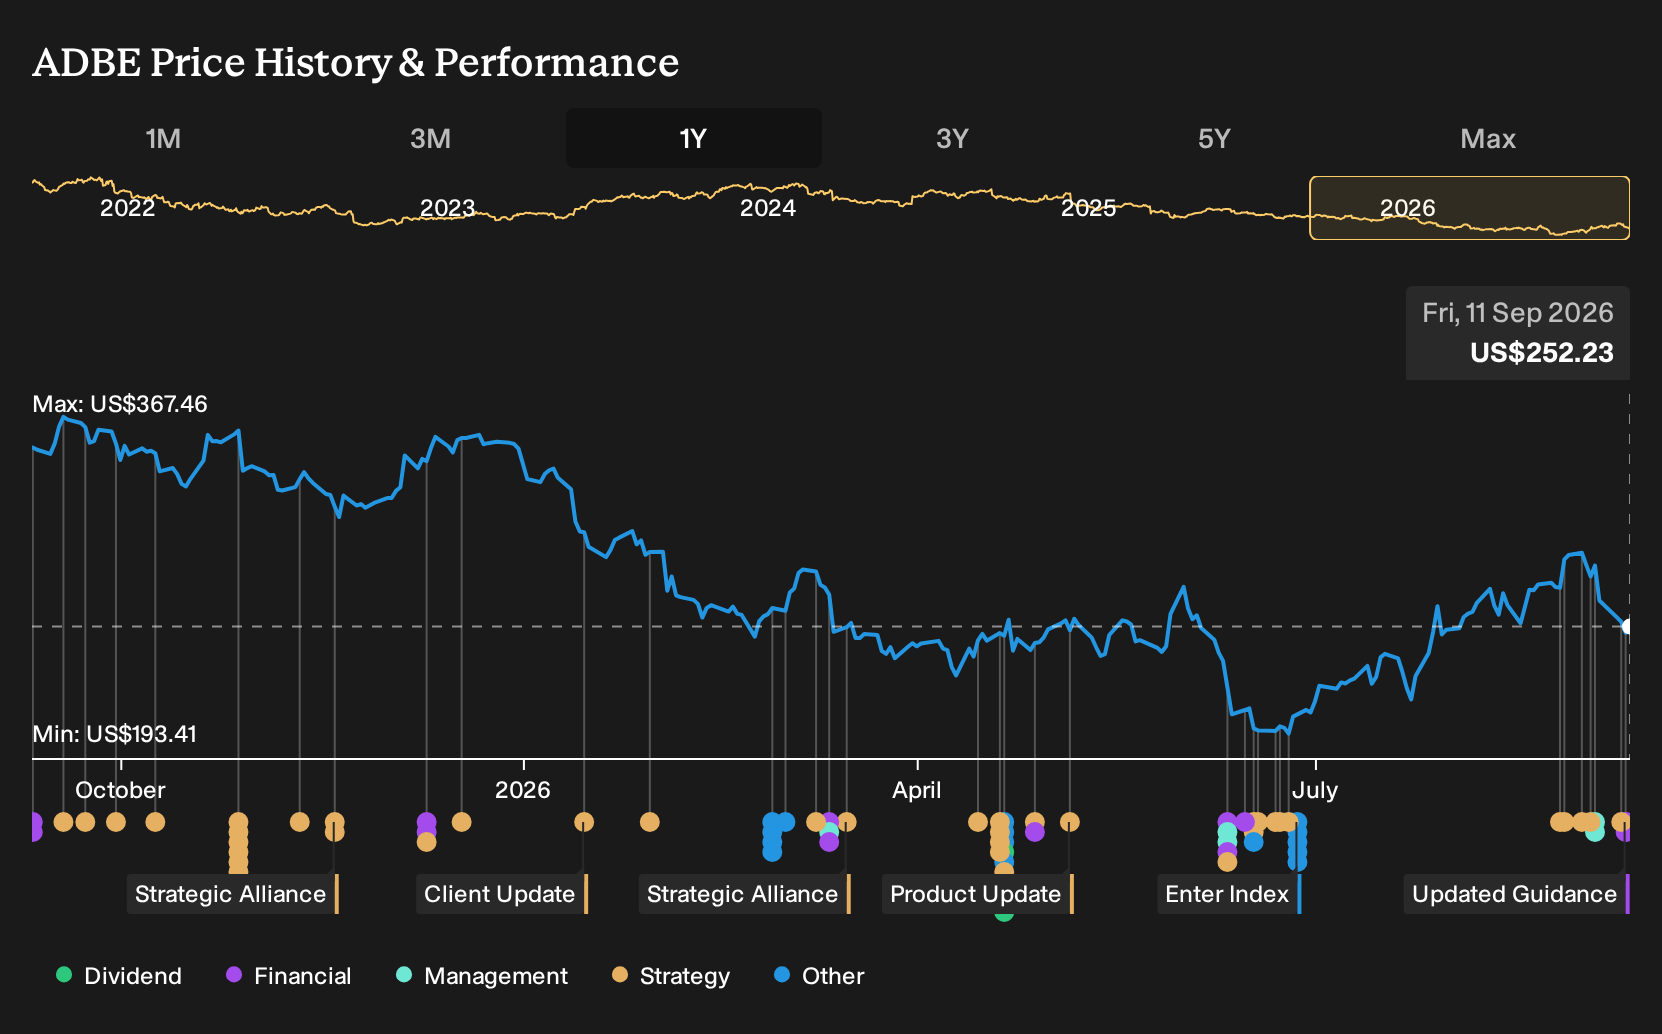
Adobe operates as a global software group that builds creative, document, and customer experience tools. Its role in AI MarTech plugs directly into the systems marketers already use to design content, manage data, and run campaigns across channels.
What Adobe’s AI MarTech role signals for its freemium and leadership tests
For Adobe, being named a key vendor in AI MarTech directly links its freemium and AI product push to the Narrative catalyst around One Adobe integration and partner ecosystems. The focus on agentic AI, privacy first personalization and platform consolidation supports the idea that Acrobat, Firefly, Express and Experience Cloud can sit inside larger marketing stacks rather than operate as isolated tools. That supports the existing thesis that AI infused products can deepen engagement and help the business win more enterprise workflows, while still leaving the Narrative risks around competitive pressure and execution on cross cloud offerings very much alive.
See how these catalysts shape Adobe's path to a $275 fair value.
The clearest early test is how far marketing and AI related demand shows up in Adobe’s Experience and AI MarTech aligned revenue and ARR compared with the current 2026 guidance range of US$26.576b to US$26.626b. Watch upcoming quarters for concrete commentary on AI MarTech deal wins, agent based features in production and how much of that activity feeds into annualized recurring revenue tied to marketing workflows rather than just creative tools.
The question about Adobe most headlines never answer
News focuses on products, competition and guidance, but the quieter question is what Adobe’s stream of cash actually suggests the whole business might be worth next to today’s share price. Find out exactly what Adobe is worth today based on its cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com