


IMAX (IMAX) Stock May Be Cheap On Cash Flow Yet Pricey On Earnings
IMAX has quietly turned a long run in the stock into a valuation puzzle for investors, with a strong five year gain set against signals that the shares are not obviously cheap, even though the Discounted Cash Flow (DCF) intrinsic value estimate points to roughly fair pricing.
- The stock has returned 209.9% over the past five years, which puts fresh pressure on whether current buyers are paying up for those past gains.
- Record box office performance for Christopher Nolan’s “The Odyssey” and related screen expansion deals can support revenue and cash flow expectations, while reliance on a limited slate of large format friendly blockbusters may leave the business exposed if the content pipeline weakens.
- The broader valuation checks give IMAX a low score, with 1 out of 6 screens suggesting the shares look more expensive than cheap on standard measures.
The stock's next move may depend on whether that mix of fair intrinsic value, rich market multiples and blockbuster driven momentum still leaves enough room for long term returns from here.
Scan beyond IMAX by reviewing 31 high quality undervalued stocks, which combine solid cash flows with stronger valuation checks than this blockbuster driven story.
Where Does IMAX Sit on Cash Flow?
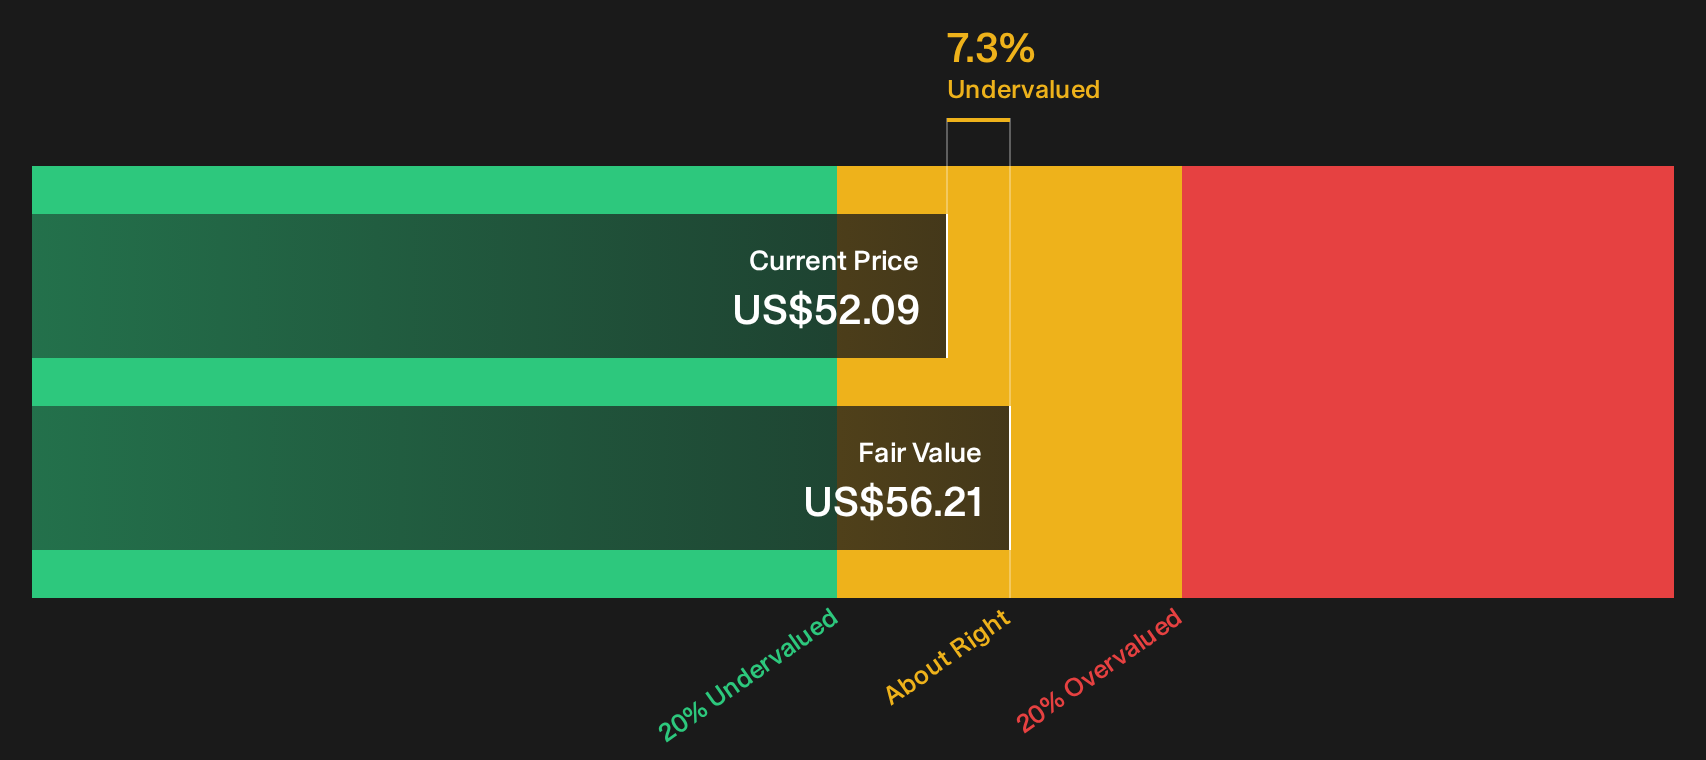
The Discounted Cash Flow model values IMAX by projecting the cash it could return to shareholders and discounting those sums back to today. IMAX is currently generating last twelve month free cash flow of about $88.8 million and the model assumes that these cash flows grow over time rather than shrink. On those inputs, the 2 Stage Free Cash Flow to Equity framework lands on an estimated intrinsic value of around $56 per share.
That figure sits only modestly above the prevailing share price, which implies roughly a 7.3% discount and suggests IMAX may be trading close to what the model indicates is a fair value rather than at an extreme discount or premium. Record performance for Christopher Nolan’s “The Odyssey” and the related screen rollout helps explain why the market may be keeping the price close to where the projected cash flows indicate it could be.
Overall, the stock appears roughly fairly valued on this cash flow view, with IMAX trading close to the Discounted Cash Flow estimate.
IMAX is fairly valued according to our Discounted Cash Flow (DCF), but this can change at a moment's notice. Track the value in your watchlist or portfolio and be alerted on when to act.
Is IMAX Getting Expensive on Earnings?
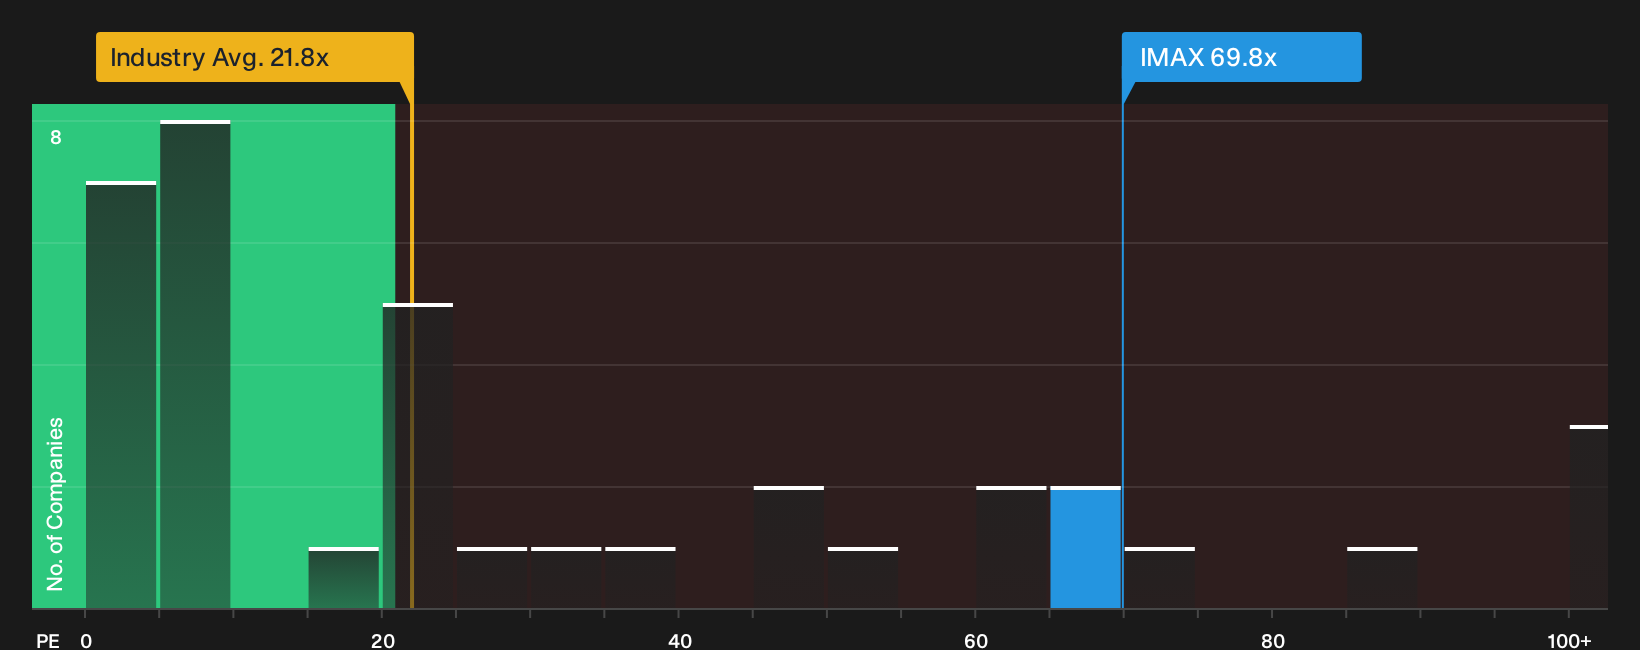
P/E suits IMAX because earnings remain a key reference point for a mature, profitable entertainment business. On this measure, the shares trade at about 69.8x earnings, compared with an Entertainment industry average of roughly 21.8x and a peer group closer to 30.5x. That is more than triple the sector yardstick, so the stock is already assuming a rich earnings profile relative to many listed rivals.
A tailored “fair” P/E based on IMAX specific characteristics sits nearer 21.4x. The gap to the near 70x market price is wide enough that the model reads less like a precise target and more like a warning flag. The framework is heavily penalising risk and earnings quality, which suggests the current multiple bakes in a lot of optimism about the business, far beyond what the fair ratio would support.
On a P/E basis alone, IMAX looks overvalued, with the market pricing its earnings at a substantial premium to both peers and the modelled fair multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The IMAX Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the IMAX valuation puzzle leaves off. They spell out which paths for future growth, margins and earnings would need to hold for the shares to justify a meaningfully higher or lower price than today. They also lay out the assumptions that sit behind each implied fair value so you can compare those expectations with how IMAX's actual results develop over time, all housed on the stock's Community page.
IMAX splits opinion sharply, with some community narratives seeing a premium format growth story and others focused on cinema specific structural risks.
Bull case: 6% undervalued
"Rapid acceleration of new system installations and a replenishing, geographically diverse backlog driven by consumer demand for premium, differentiated out of home entertainment positions IMAX for continued growth in both top line revenue and recurring cash flows…"
Read the full Bull Case to see why IMAX could be undervalued
Bear case: 27% overvalued
"The rapid improvements and affordability of premium home cinema technology, such as large OLED TVs and advanced in home sound systems, are narrowing IMAX's historical experiential advantage…"
Read the full Bear Case to see why IMAX could be overvalued
Do you think there's more to the story for IMAX? Head over to our Community to see what others are saying!
The Bottom Line
IMAX screens as roughly fairly valued on a Discounted Cash Flow (DCF) view, with the intrinsic value estimate only modestly above the current price. Market multiples tell a very different story, with an extreme gap between the rich P/E and the modelled fair ratio that reflects heavy reliance on optimistic earnings expectations and sentiment. Broader valuation checks remain weak despite the DCF support. The key question is whether premium format demand and blockbuster supply stay strong enough to sustain those elevated earnings assumptions rather than justifying a cheaper, less optimistic multiple over time.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com