


Hooker Furnishings (HOFT) Stock Finds Profit Traction As Revenue Keeps Sliding
Hooker Furnishings stock ticked up 2.1% to $12.83 into the weekend, a modest move for what felt like a much bigger psychological shift. The company is a retailer coming off a weak three-month share performance, then quietly posting a third straight profitable quarter with Q2 net income of $1.7 million and a gross margin of 31.8%.
The real story sits beyond today’s bounce. A furniture maker that was losing money on a trailing 12-month basis is now leaning on tariff recoveries, cost cuts and a cleaner balance sheet. Forecasts currently indicate expectations for earnings to turn the corner over the coming years.
Is Hooker Furnishings a genuine value opportunity or just a low-price mirage given trailing losses and a 0.5x P/S against peers? Compare the stock’s current valuation, growth forecasts and margin profile in the valuation analysis for Hooker Furnishings.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): US$63.25 million vs. US$69.24 million (fell about 9%).
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): US$1.19 million profit vs. US$0.57 million loss (swing back to profitability).
- Basic EPS (Q2 2027 vs. Q2 2026): US$0.11 vs. a loss of US$0.05 per share (return to positive earnings per share).
- Gross Margin (Q2 2027 vs. Q2 2026): 31.8% vs. roughly 24.9% (expansion of about 690 basis points).
If you are tired of scrolling through dense earnings tables and raw figures for Hooker Furnishings, you can view a clearer picture of the business in an easy visual format. See how its valuation compares with its recent return to profitability with the company report for Hooker Furnishings.
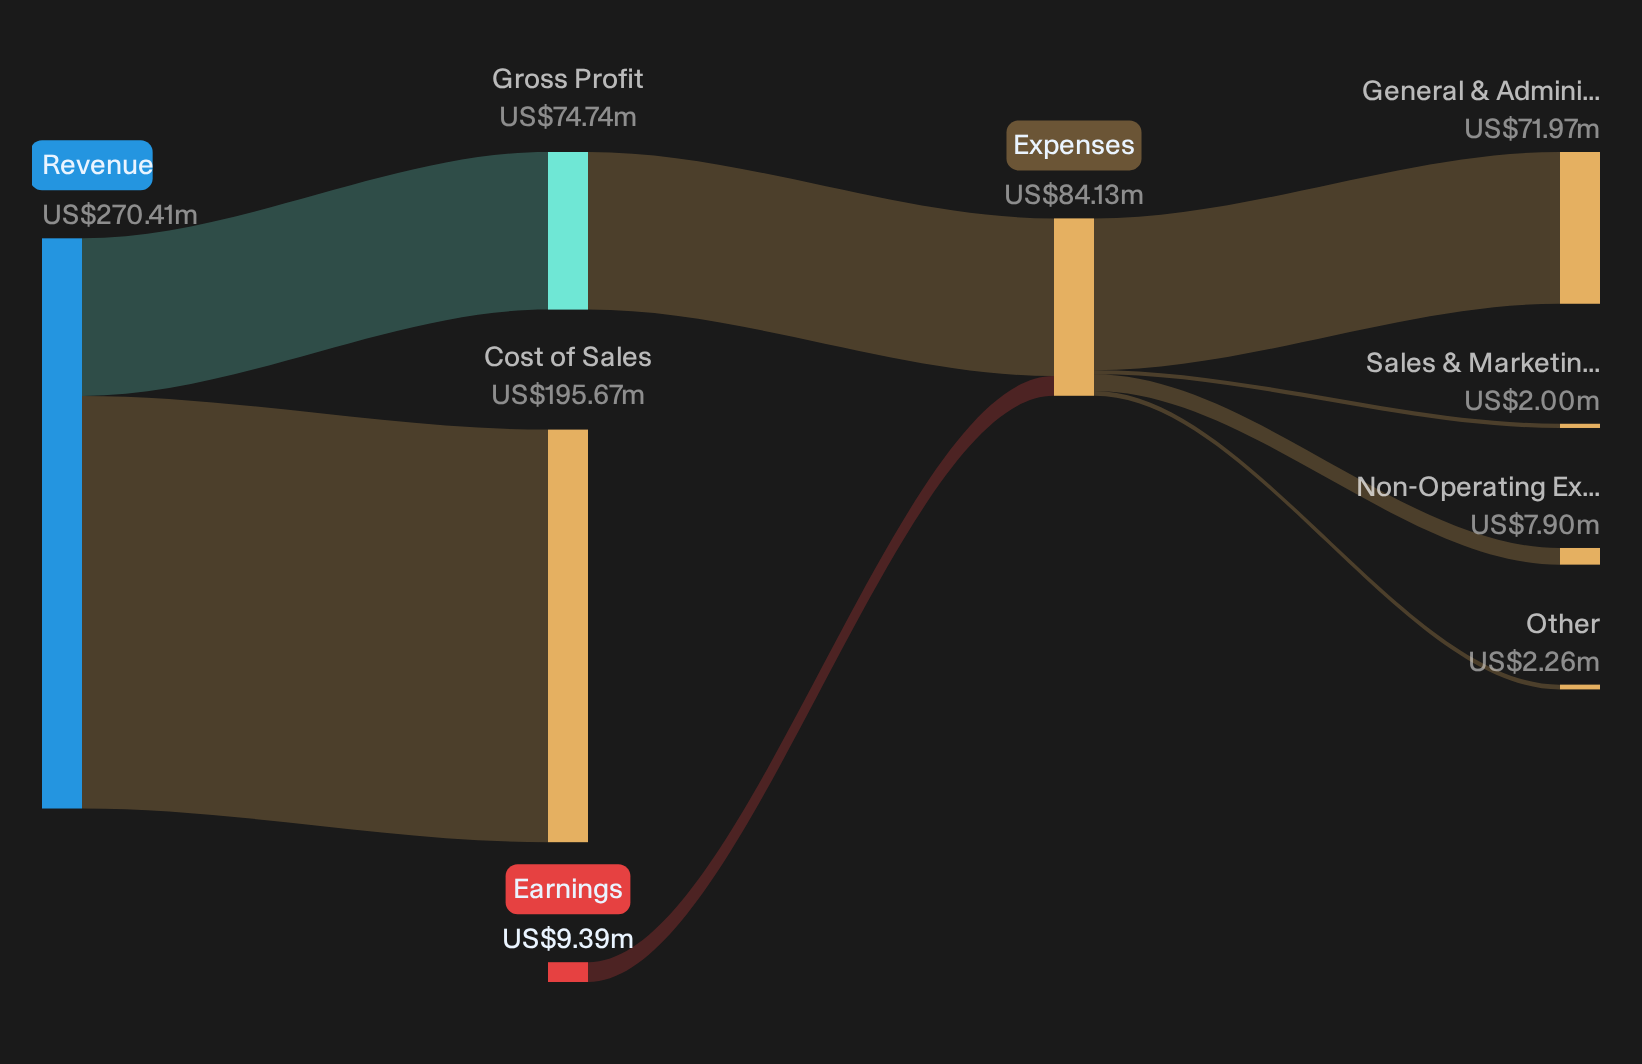
Hooker Furnishings bull case meets early proof points
Bulls argue Hooker Furnishings is rebuilding a higher margin business on a leaner footprint, with logistics changes and cost cuts doing the heavy lifting. Q2 backs up part of that story. Revenue fell about 9%, yet gross margin reached 31.8%, up 690 bps, and operating income moved to a US$1.3 million profit from a loss. That points to real cost savings, not just volume leverage. Hooker Branded gross margin near 40% and Domestic Upholstery margin at 23% both reflect tariff recoveries and lower imported material costs feeding through. Three straight profitable quarters and US$24 million operating cash flow in six months show the restructuring is translating into cash, not just adjusted metrics. Backlog growth in Hooker Branded, up roughly 35%, and in Domestic Upholstery, up about 5%, also supports the idea that merchandising tweaks and better inventory are starting to gain traction.
Bear case flags revenue drag and one off support
Skeptics worry that Hooker Furnishings is leaning on temporary boosts while underlying demand stays soft. The Q2 print gives them some backing. Sales declined about 9% year on year and management still describes housing turnover and big ticket spending as weak. A large slice of the margin story ties to tariff recoveries that management admits only partially offset past costs, which means a meaningful portion of today’s profitability is non recurring. Hooker Branded relied on promotions and a higher e commerce mix, which pressured pricing power even as gross profit improved. All Other sales dropped about 66% on hospitality timing and that unit posted a quarterly loss. The share price is only modestly higher into a weekend close after a weak 90 day run, which suggests investors are not yet convinced that cost cuts, Margaritaville rollout and backlog alone can offset ongoing demand and earnings volatility risks.
Compare Hooker Furnishings’ margin rebuild story with what institutional desks actually expect from here. See whether analysts think this turnaround has real legs or is already priced in through the consensus price target analysis for Hooker Furnishings.
Stay Ahead Of Your Next Move
Hooker Furnishings just posted a third straight profitable quarter while revenue pressure and one off tariff recoveries keep the story finely balanced, which makes timing and entry price matter even more. Register free with Simply Wall St and add Hooker Furnishings to your Watchlist so you can track its share price against fair value and watch how margins and cash flow progress before you act. Once you are invested, keep your decisions focused with the Portfolio Command Center that cuts through noise and highlights only the key fundamental changes across your holdings. For a longer term edge, tap into crowd views and different angles on Hooker Furnishings through the Community so you can spot fresh catalysts or emerging risks early and stay a step ahead of the market.
Seeking Fresh Alternatives Beyond Hooker Furnishings
Fresh opportunities move fast. The next breakout cluster of ideas can gain momentum while you are still caught on yesterday’s stories. Scan these under the radar picks before the crowd moves in and act now.
- Track resilient performers with strong balance sheets and steady fundamentals using the curated list of solid balance sheet and fundamentals stocks (23 results) that helps you spot potential compounders while prices are still dropping or stalled.
- Hunt for potential income workhorses that pair rich yields with sturdier financial profiles by reviewing the curated 6 dividend fortresses before investors rush toward defensive payouts and compress the returns on offer.
- Target early movers in AI infrastructure and support plays by scanning the hand picked 89 AI infrastructure stocks while they are still under the radar for now and before momentum really starts flying.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com