


Bending Spoons (BSP) Agreed To Buy Miro, Is The Stock Fully Priced?
Bending Spoons (NasdaqGS:BSP) moved back into focus after agreeing to acquire visual collaboration platform Miro in an all cash deal valuing the target at about US$1.355b, with some shareholders reinvesting into new BSP equity.
For all the attention on the Miro deal, Bending Spoons’ share price has eased in recent weeks. The 30 day share price return is 5.25% and the year to date share price return of 4.27% is below water, suggesting momentum has cooled as investors weigh the acquisition and the broader portfolio of recent software purchases.
Compare Bending Spoons’ deal making with other software platforms by scanning our hand picked list of 15 high quality undiscovered gems that are also buying assets and reshaping their portfolios.
Bending Spoons now trades below recent highs while committing US$1.355b to Miro. Do you pay up for this portfolio shift today, or wait for a cheaper entry before the next leg of analysis on value?
Most Popular Narrative: 19.7% Undervalued
Bending Spoons’ most followed narrative pegs fair value at about $48.27, above the recent $38.77 close, putting a spotlight on the assumptions behind that gap.
The availability of a large pool of digital businesses that Bending Spoons views as potential targets, combined with expanded access to term loans, revolving credit facilities and IPO proceeds, supports ongoing M&A capacity, which can influence future revenue scale and earnings power.
Investors may want to examine what kind of revenue path and margin profile would need to materialize for that valuation to hold over time. The narrative highlights ambitious expectations for top line expansion, improving profitability and a future earnings multiple that many investors usually associate with mature software platforms.
Result: Fair Value of $48.27 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Bending Spoons story can break if deal flow dries up, or if its US$4.09b net debt and 2.4x leverage ratio start to bite.
Find out about the key risks to this Bending Spoons narrative.
Another View On Bending Spoons’ Valuation
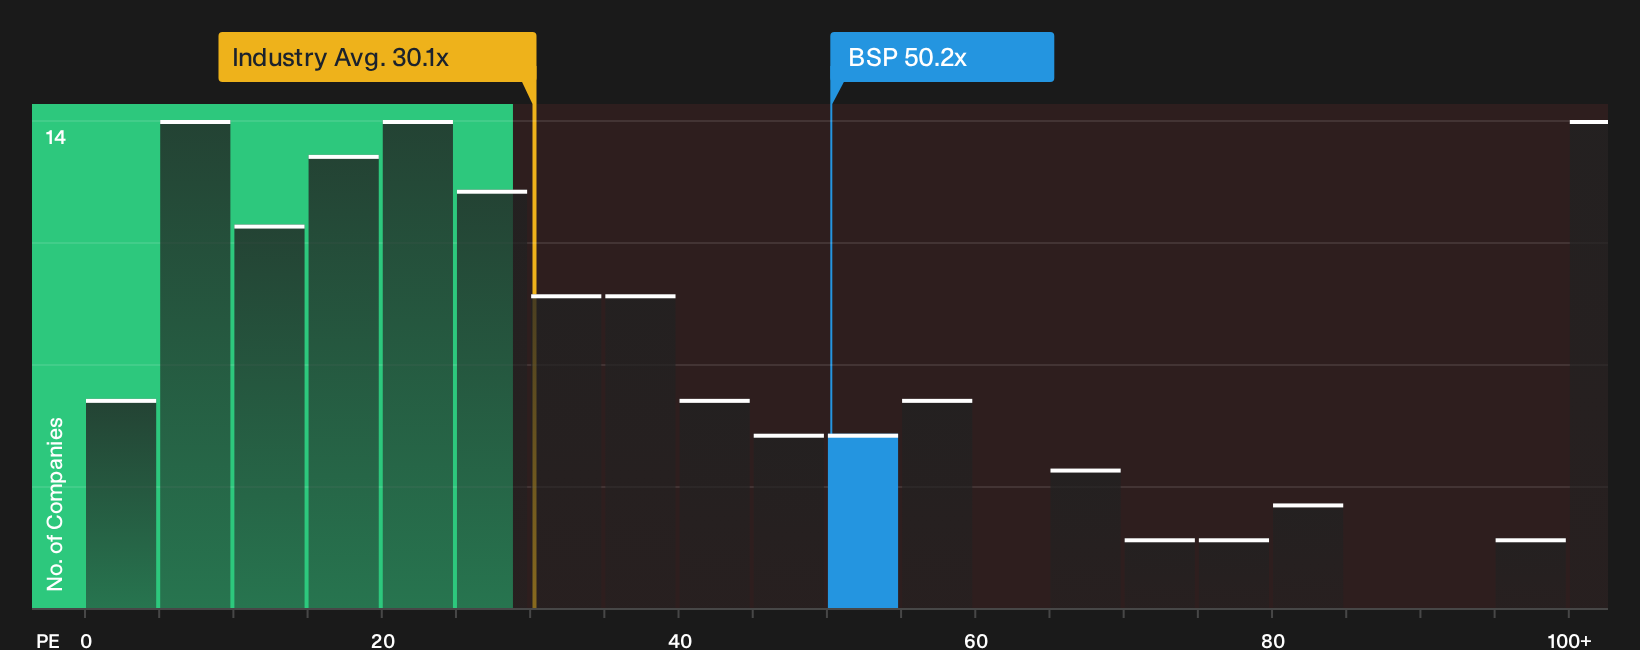
The first story around Bending Spoons leans heavily on fair value estimates and future earnings power. A simple P/E lens tells a tougher story. At about 50.2x earnings versus 30.1x for the wider US software group, BSP trades on a much richer multiple than the sector average.
Peer stocks on similar fundamentals average 66.8x, so BSP also sits below that cluster. That mix of premium to the industry but discount to peers raises a practical question for you as an investor: Is this a justified quality premium or a valuation risk if expectations reset?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of debate runs through this Bending Spoons story, so move fast, review the upside and downside data, and anchor your own conviction using the 3 key rewards and 3 important warning signs
Looking for more Bending Spoons style investment ideas?
If you stop with Bending Spoons, you risk missing other opportunities that fit your style, your risk comfort and your return expectations across the market.
- Target mispriced quality by reviewing the 32 high quality undervalued stocks that combine solid fundamentals with prices that some investors may be overlooking.
- Anchor your portfolio with stability by scanning the 6 dividend fortresses that focus on higher yielding payouts from established businesses.
- Dial back risk while staying invested by checking the 11 resilient stocks with low risk scores that screen for companies with more resilient profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com