


AT&T (T) Stock Looks Undervalued While Its 100% Return Raises Questions
AT&T stock has more than doubled over the past three years, yet the company still screens as undervalued on broad valuation checks, which gives investors an unusual mix of a strong past run and a price tag that still looks restrained. The question is whether that combination reflects durable fundamentals or simply a rebuild from earlier weakness that leaves limited room for error.
- AT&T has delivered a 100.4% return over three years, which means anyone looking at the chart sees a full recovery story rather than a beaten down telecom.
- The push into fiber, wireless bundles and new satellite partnerships with Amazon can support long term cash generation, while competitive pressure from rivals and emerging satellite services like SpaceX Starlink may cap pricing power and weigh on future returns.
- With a value score of 5, the broader checks lean cheap and suggest AT&T is pricing in relatively low expectations compared with what its fundamentals may be able to support.
The issue now is whether AT&T's current share price already reflects the recent recovery in performance, or if the valuation still leaves meaningful upside for patient holders over the next few years.
Spot other telecoms and infrastructure players that also screen as high quality yet undervalued by running through 32 high quality undervalued stocks alongside AT&T.Does AT&T Look Undervalued on Earnings?
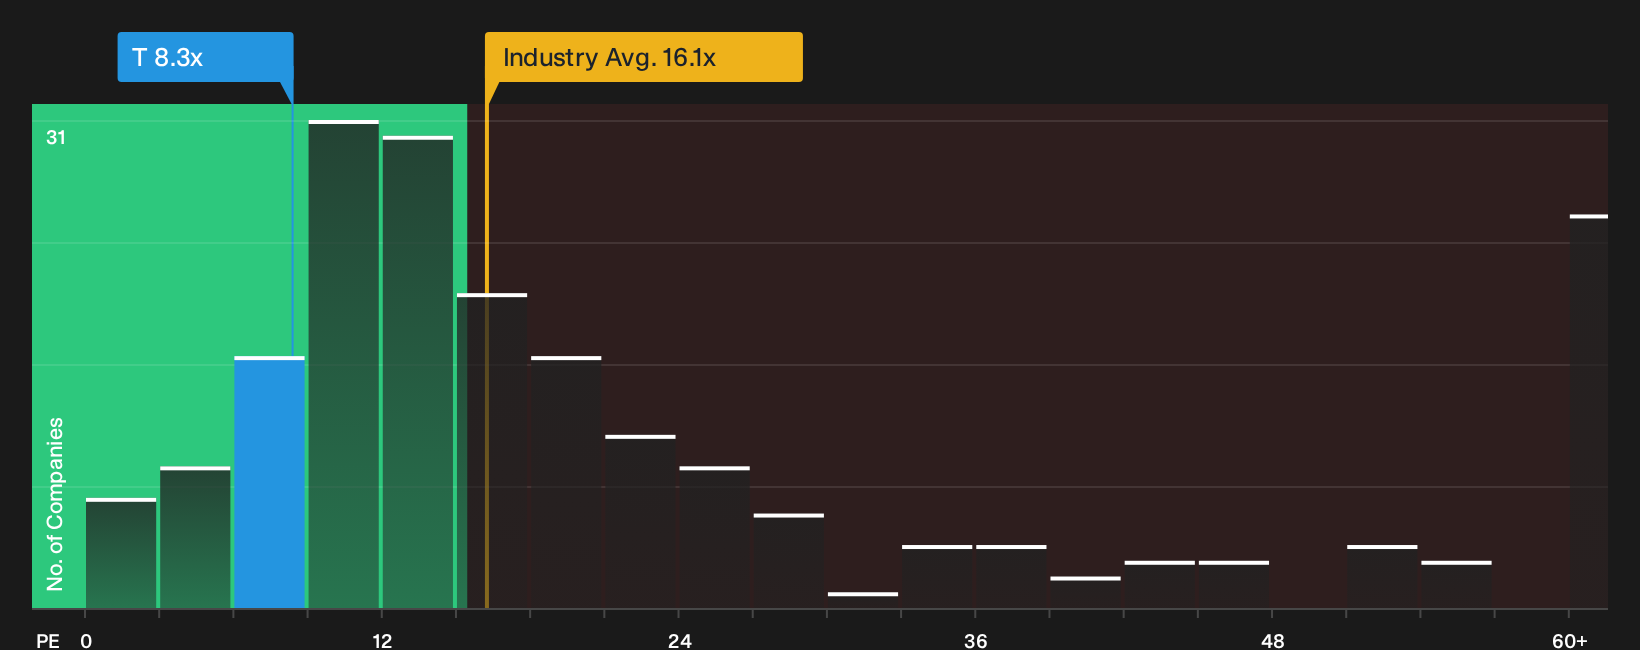
The P/E ratio is a useful shorthand for AT&T because earnings remain a key anchor for how investors judge large, mature telecom groups. AT&T trades on roughly 8.3x earnings, which sits well below the telecom sector average of about 16.1x and under the peer group near 11.9x. That puts the stock on a visibly lower earnings multiple than many comparable carriers.
A more tailored fair P/E for AT&T, which incorporates its margins, risk profile and size, comes out at about 14.8x. The current 8.3x level is a sizeable step under that yardstick and points to an undervalued earnings stream if the business can hold its footing. Despite recent attention around satellite competition and AT&T’s partnership with Amazon on low Earth orbit services, the market is still pricing the shares at a clear discount to what this framework suggests.
On a P/E basis, AT&T stock appears undervalued relative to both sector norms and the level implied by its own fundamentals.
See what the numbers say about this price — find out in our valuation breakdown.
The AT&T Narrative: What Would Justify Today's Price?
Narratives on AT&T pick up where the valuation puzzle leaves off. They spell out which paths for growth, profit margins and earnings would need to play out for the current price to look either too low or too full. Each one links its number to a clear view on how AT&T's opportunities and risks might shift, giving you something concrete to revisit as fresh information comes through the Community page.
Community narratives around AT&T are pulling in opposite directions, with one camp focused on fiber driven cash generation and the other wary of heavy spend and tougher competition.
Bull case: 10% undervalued
"Retiring legacy copper and wireline infrastructure is driving structural cost reductions, enabling improved operating leverage and higher free cash flow that can be reinvested for growth or returned to shareholders..."
Read the full Bull Case to see why AT&T could be undervalued
Bear case: 23% overvalued
"AT&T's continued heavy investment in 5G and fiber infrastructure, amounting to $22 billion, coupled with reliance on potential tax incentives for expanded investment, may not yield sufficient returns as competition and market saturation in these areas increase, risking revenue growth stagnation..."
Read the full Bear Case to see why AT&T could be overvalued
Do you think there's more to the story for AT&T? Head over to our Community to see what others are saying!
The Bottom Line
AT&T screens as undervalued on earnings multiples, so the market is pricing in a fairly muted future for a business that still throws off meaningful cash. That discount only turns into an opportunity if fiber and wireless investments translate into stable profitability rather than ongoing heavy spend with flat returns. The key question is whether AT&T can keep funding network upgrades and satellite partnerships while holding margins together. If that balance tilts the wrong way, the current gap to sector P/E levels can prove more value trap than mispricing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com