


Hinge Health (HNGE) Stock Looks Overvalued On Earnings But Mixed On Broader Checks
Hinge Health stock has nearly doubled year to date, yet the latest valuation checks point to a company that screens as overvalued on market multiples and only delivers a mixed overall value score. For anyone tracking the recent rally, the question is whether the current price already bakes in most of the optimism around the business.
- Hinge Health is up 94.4% year to date, which puts recent buyers on notice that expectations embedded in the share price have moved a long way in a short time.
- The long term case can benefit from confidence in Hinge Health's ability to scale its digital musculoskeletal care model efficiently. However, any stumble in execution or slower adoption may weigh heavily on how much investors are willing to pay for that growth story.
- The broader checklist is a mixed picture rather than a clear bargain or clear overvaluation, with a value score of 4 out of 6 suggesting neither the bull nor bear case fully dominates right now.
The issue now is whether the current valuation of Hinge Health leaves enough room for error after such a strong year to date move.
Balance the excitement around Hinge Health's 94.4% year to date surge by stress testing your ideas against 32 high quality undervalued stocks that still screen well on quality.
Does Hinge Health Look Pricey on Earnings?
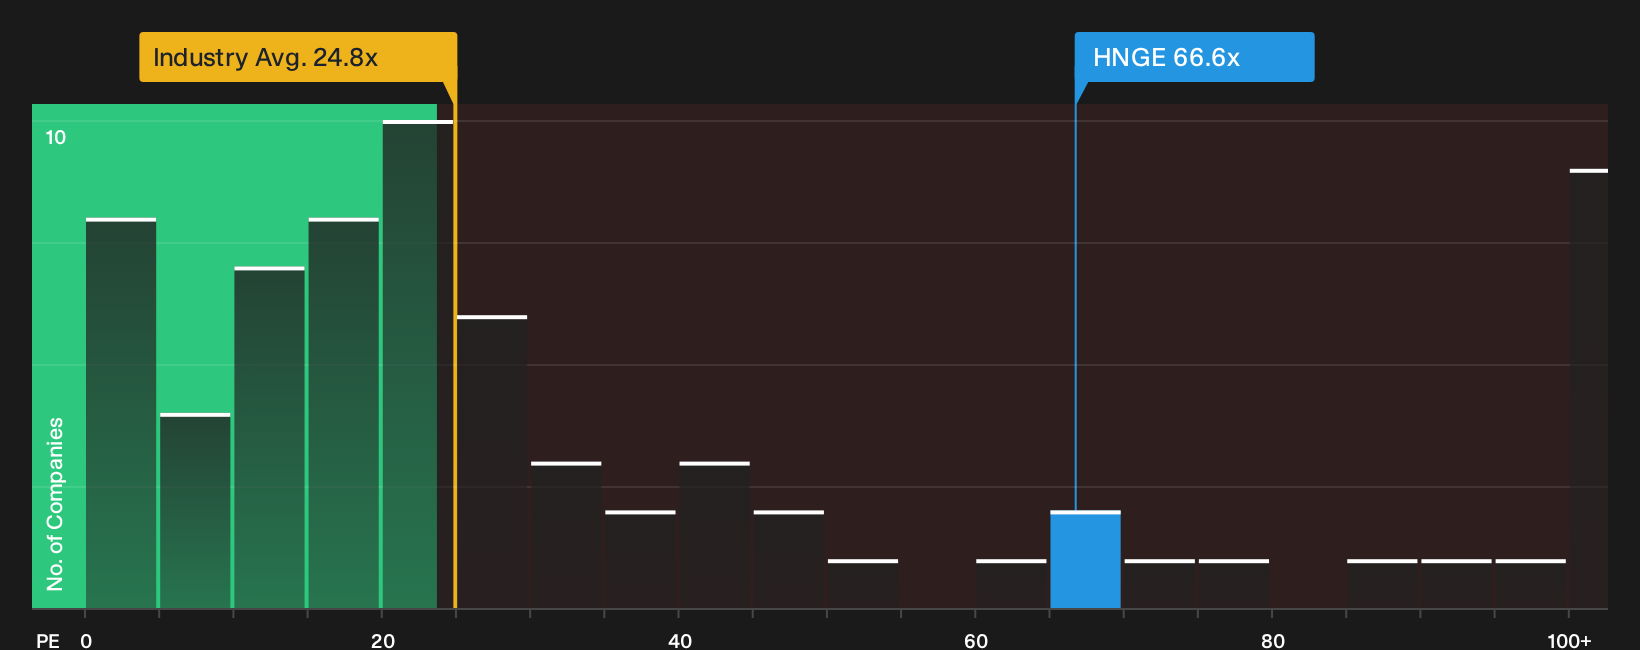
P/E works well for Hinge Health because the stock already has positive earnings, so investors can compare its price directly with profits today. On that yardstick, Hinge Health trades at about 66.6x earnings, against a Healthcare sector average of roughly 24.8x and a peer set around 69.2x. The shares are priced close to peers but far above the broader industry, which indicates the market is willing to pay a premium for this business model.
The fair P/E ratio implied by the valuation framework is about 38.7x. That is well below the current 66.6x, so the market is attaching a much richer multiple than the model suggests, based on factors such as scale, risk and profitability. Anyone considering Hinge Health stock needs to ask whether the current earnings base and business profile justify paying an earnings multiple that far above the tailored fair level.
On this P/E yardstick, Hinge Health stock screens as overvalued, with the share price implying a significantly higher multiple than the model’s fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
The Hinge Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Hinge Health's valuation puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the shares to be worth materially more or materially less than today’s price on the Community page. Each scenario links its number to a specific view on how Hinge Health's revenue potential, margin profile and risk picture might evolve, which you can revisit as fresh information comes through.
Community views on Hinge Health sit on a wide spectrum, from material upside potential to a case that current expectations already look demanding.
Bull case: 17% undervalued
"Expansion of integrated digital and in person offerings through HingeSelect and broader provider network build out positions the company to pursue a larger share of MSK and adjacent care pathways…"
Read the full Bull Case to see why Hinge Health could be undervalued
Bear case: roughly fairly valued
"Although HingeSelect is positioned around high quality providers and lower cost care, it is a multi year buildout of a two sided network…"
Read the full Bear Case to see why Hinge Health could be overvalued
Do you think there's more to the story for Hinge Health? Head over to our Community to see what others are saying!
The Bottom Line
Hinge Health now trades on a richer P/E than both the wider Healthcare sector and the modelled fair multiple, so the valuation skews toward overvalued on current earnings. That does not end the debate, but it raises the bar for what the business needs to deliver for today’s price to look sensible in hindsight. The real hinge point is whether Hinge Health can translate its musculoskeletal care platform into sustained profitability improvements that make this premium multiple feel earned rather than optimistic.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com