


Should Strong Half Year Earnings Growth Require Action From LU-VE (BIT:LUVE) Investors?
- LU-VE S.p.A. reported half-year 2026 results, with sales of €325.14 million and net income of €26.45 million, compared with €294.71 million and €16.28 million respectively a year earlier.
- The wider gap between revenue and profit versus last year may indicate tighter cost control or stronger pricing power within LU-VE’s operations.
- We will look at how LU-VE’s investment narrative is influenced by this step up in half-year sales and net income performance.
Scan how LU-VE's latest half-year results compare to peers by reviewing our curated list of list of solid balance sheet and fundamentals (195 results).
What Is LU-VE's Investment Narrative?
To own LU-VE, you need to be comfortable with a fairly straightforward industrial story. The group builds heat exchangers and cooling equipment for refrigeration, air conditioning and power applications, so the thesis hinges on consistent demand from those end markets, disciplined project execution and the ability to protect pricing against input costs. The latest half year, with higher sales and net income than a year earlier, suggests operations are scaling efficiently rather than just chasing volume.
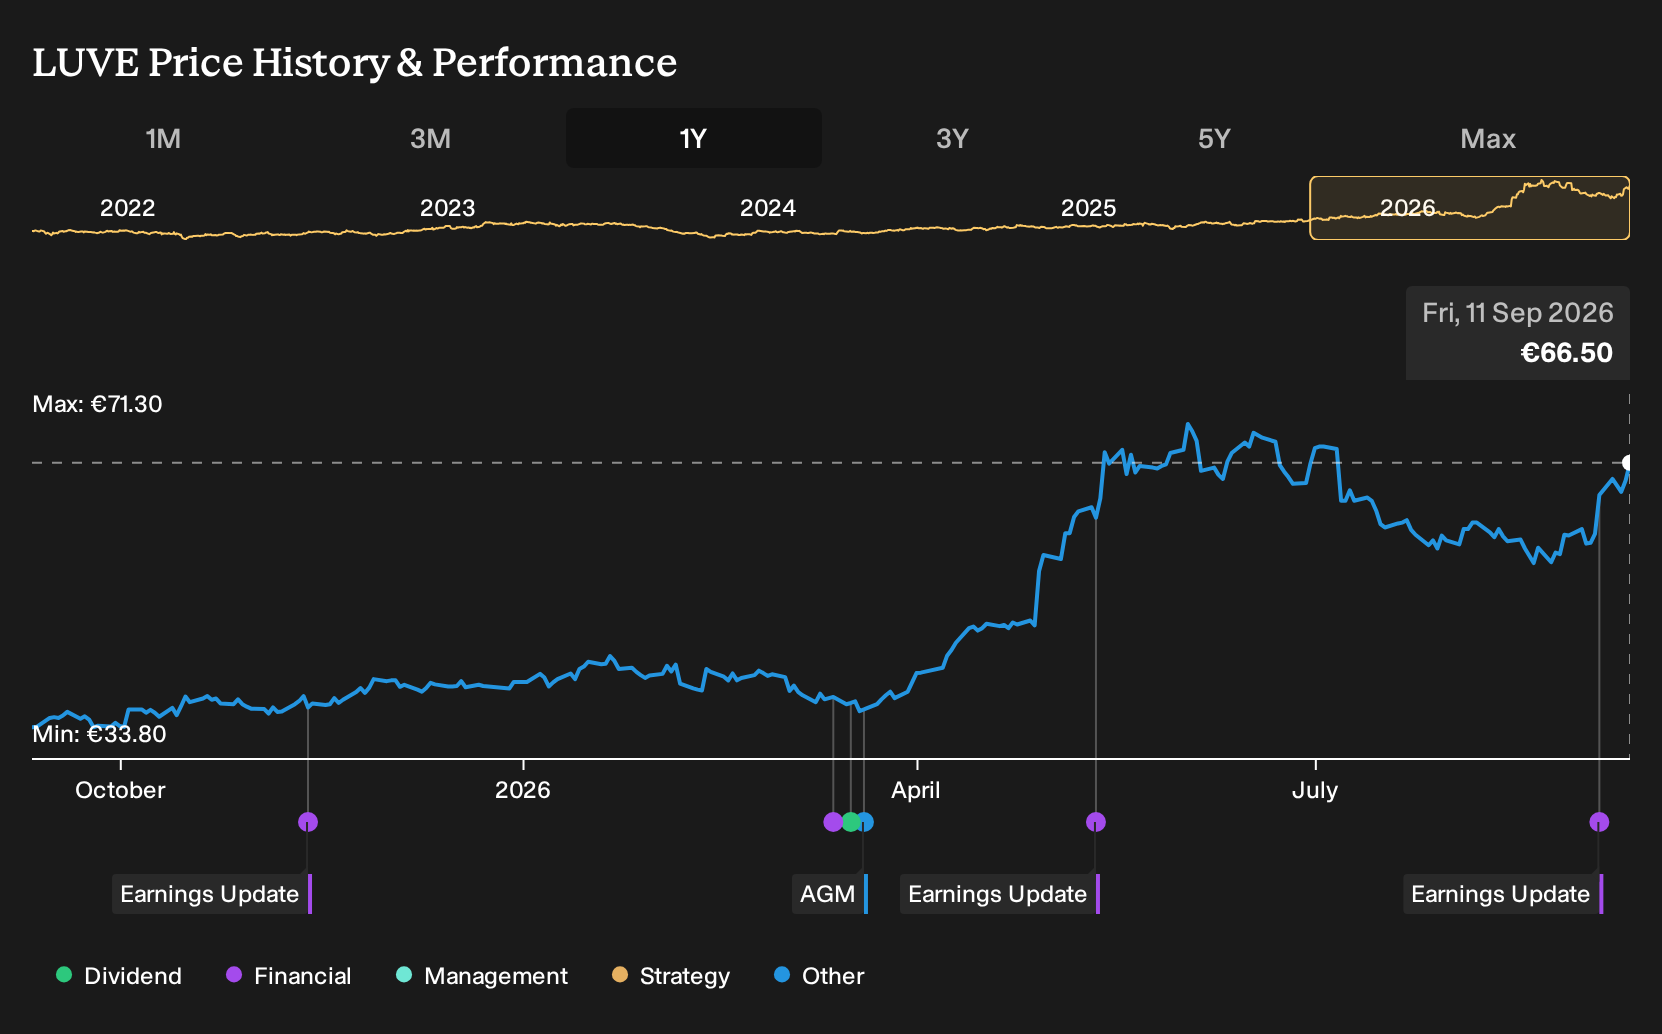
The immediate focus now is whether that profit profile can support ongoing investment in capex heavy manufacturing without stretching the balance sheet, given funding relies on external borrowing. In the short term, the share price already had a strong 1 year run and has been volatile over 3 months, while trading on a P/E of 30.6x. That makes the earnings step up an important support for the current valuation, rather than a free upside surprise.
That said, there is one operational pressure point inside LU-VE's story that does not get much attention.
There's only one way to know the right time to buy, sell or hold LU-VE. Head to Simply Wall St's company report for the latest analysis of LU-VE's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your LU-VE research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for LU-VE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate LU-VE's overall financial health at a glance.
Looking For More Investment Ideas Beyond LU-VE?
If LU-VE has sharpened your interest in quality industrial stories, it can help to line it up next to other stocks with different balance sheet strength, income profiles and risk levels. The Simply Wall St Screener lets you move from a single ticker to a short list of candidates that fit the way you prefer to invest.
Here are a few focused stock lists that can broaden your watchlist:
- If capital preservation sits high on your checklist, start with a 98 resilient stocks with low risk scores that keeps volatility and business risk scores in tighter ranges.
- Income oriented investors can zero in on established payers by scanning 164 dividend fortresses that combine higher yields with a record of distributions.
- For those willing to dig deeper into underfollowed opportunities, short list 620 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com