


How Investors Are Reacting To MSC Stock New CFO Appointment
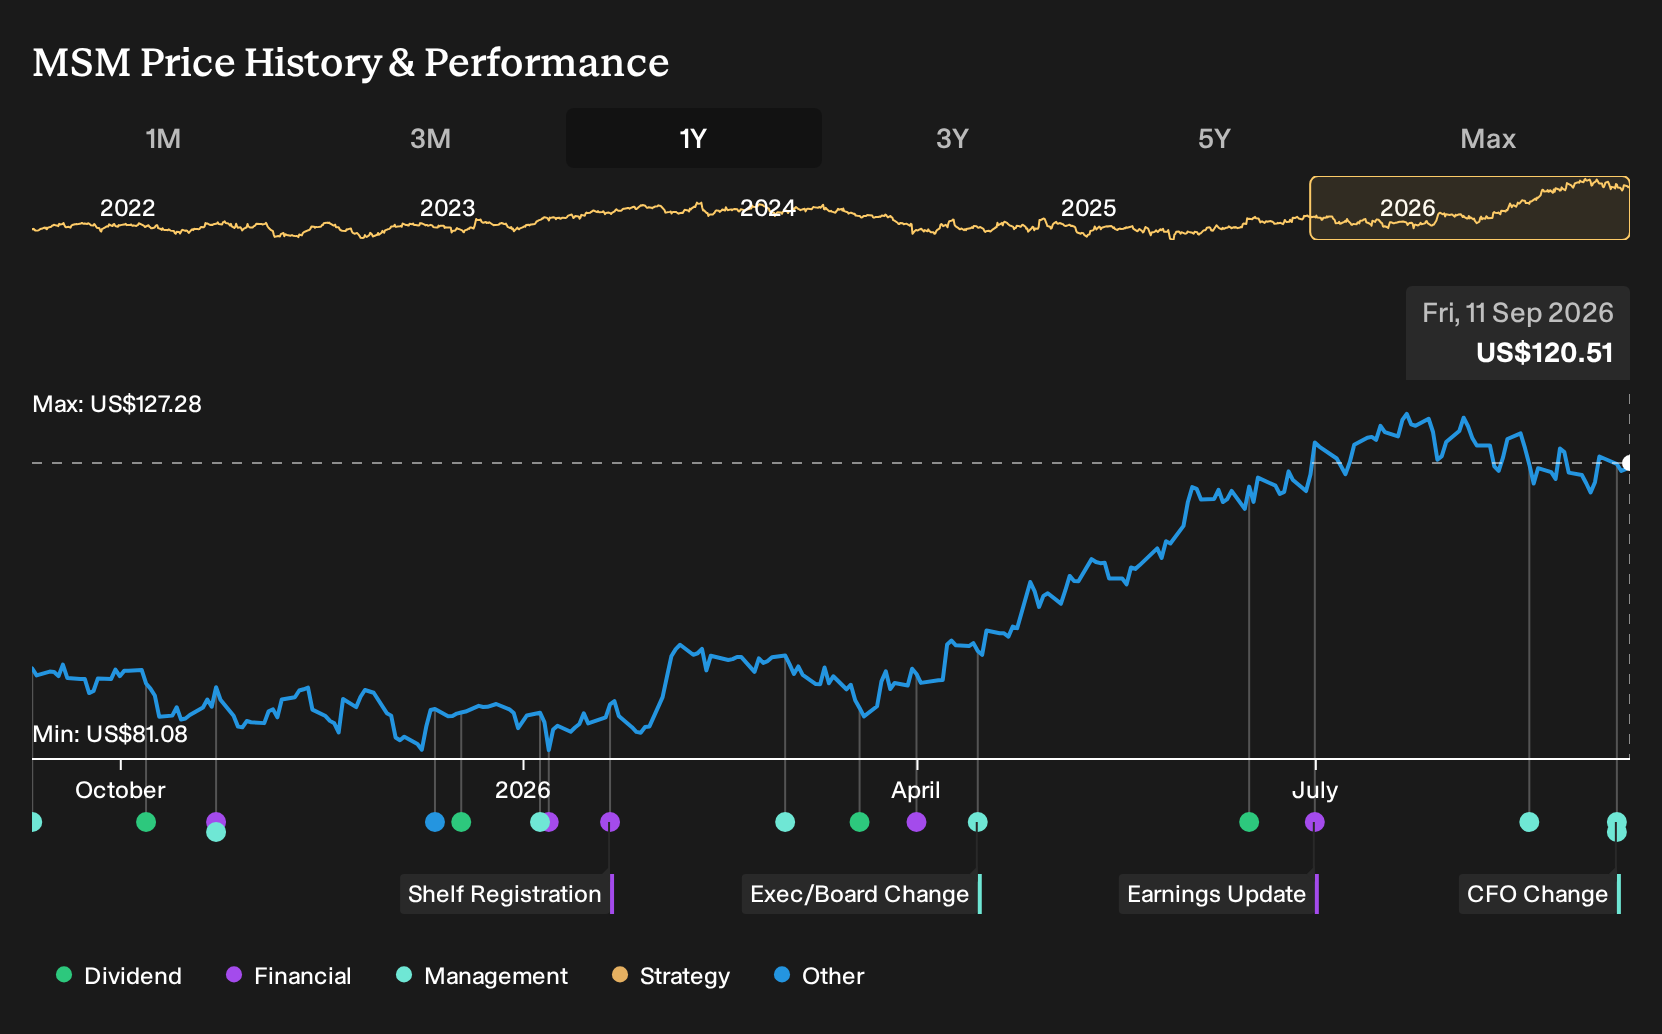
- MSC Industrial Direct appointed Robert Kuhns as Executive Vice President and Chief Financial Officer on September 14, 2026, moving Greg Clark back to his prior role as Vice President of Finance and Corporate Controller.
- Kuhns brings fresh financial leadership to MSC Industrial Direct after serving as CFO and previously Controller at TopBuild, with earlier finance roles at Mohawk Industries, NCH Corporation and Ingersoll Rand, which could influence how the business manages costs, capital allocation and execution on its operational initiatives.
- We will now look at how MSC Industrial Direct's investment narrative could be shaped by Robert Kuhns stepping in as permanent CFO.
MSC Industrial Direct Investment Narrative Recap
To own MSC Industrial Direct, you need to believe its investments in In Plant programs, vending, and digital channels can offset soft industrial demand and tariff uncertainty over time. The immediate story still hinges on execution. The Kuhns appointment does not radically change that in the near term. The key catalyst remains whether recent efficiency and sales initiatives show up in steadier daily volumes and margin resilience.
The biggest risk continues to be weaker manufacturing activity and tariff exposure on roughly 10% of cost of goods from China, especially with higher operating expenses already pressuring profitability. A permanent CFO may help tighten cost discipline and capital allocation, but the announcement itself does not materially reduce those external and execution risks right now.
The Jefferies Global Industrials Conference on September 9, 2026 is the most relevant recent event to watch around this CFO transition. President and CEO Martina McIsaac and the Head of Investor Relations are scheduled to speak, which gives management a timely platform to explain how MSC Industrial Direct is thinking about demand softness, tariffs, and cost structure with a new finance leader in place.
Investors can listen for detail on how network optimization, technology investments, and seller effectiveness programs are tracking against internal expectations. Clarity on how Kuhns will support these efforts, plus any commentary on capital allocation priorities in light of MSC Industrial Direct's valuation and dividend profile, could shape how you weigh the near term catalysts against the macro and execution risks already on the table.
MSC Industrial Direct's narrative projects revenues of US$4.6b and earnings of US$345.5m by 2029. This is based on analysts' assumptions of 5.9% yearly revenue growth and an earnings increase of about US$114.3m from current earnings of US$231.2m.
Discover why MSC Industrial Direct's fair value indicates a 9% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view around MSC Industrial Direct focuses less on tariffs and more on pricing risk. The lowest analysts were already cautious, working off revenue expectations of about US$4.5b and earnings of roughly US$354.2m by 2029. Those forecasts came before the Kuhns appointment, so your own take may shift as the new CFO’s approach becomes clearer.
Explore 2 other MSC Industrial Direct fair value estimates, including one that suggests as much as 31% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your MSC Industrial Direct research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for MSC Industrial Direct. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MSC Industrial Direct's overall financial health at a glance.
Looking For More Investment Ideas Beyond MSC Industrial Direct?
If you want to round out your view of MSC Industrial Direct with options in other areas of the market, the Simply Wall St Screener can help you quickly sort through companies that fit different risk, income, and balance sheet profiles.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (23 results) that can help you focus on businesses with stronger fundamentals and cleaner balance sheets.
- If value is your priority, filter for mispriced opportunities by running a search across 31 high quality undervalued stocks that may align better with your return and risk goals.
- Income focused portfolios can benefit from steady cash returns, so consider a sweep of 6 dividend fortresses that may fit a yield driven approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com