


Is Coinbase Global (COIN) Fully Priced For Its Everything Exchange Push?
Coinbase Global has delivered a powerful 113.3% gain over the past three years, yet the current valuation checks and low value score suggest the stock is priced at a premium rather than offering an obvious bargain.
- Over the past three years, Coinbase Global is up 113.3%, which puts recent weakness into context and underlines how much optimism is already in the share price.
- Momentum around the "Everything Exchange" push, from Bitcoin ETF activity to new derivatives and tokenized products, can support higher expectations, while regulatory and crypto market risk may quickly pressure those expectations and the valuation that sits on top of them.
- On Simply Wall St's broader assessment, Coinbase Global is undervalued in only 1 of 6 valuation checks, which leans expensive rather than suggesting a clear value opportunity.
The issue now is whether that premium setup for Coinbase Global is justified by the business it already has, rather than the future story investors are currently paying for.
Spot opportunities with Coinbase Global’s peers by scanning hand-picked crypto and blockchain exposed companies using 21 cryptocurrency and blockchain stocks.Is Coinbase Global Getting Expensive on Sales?
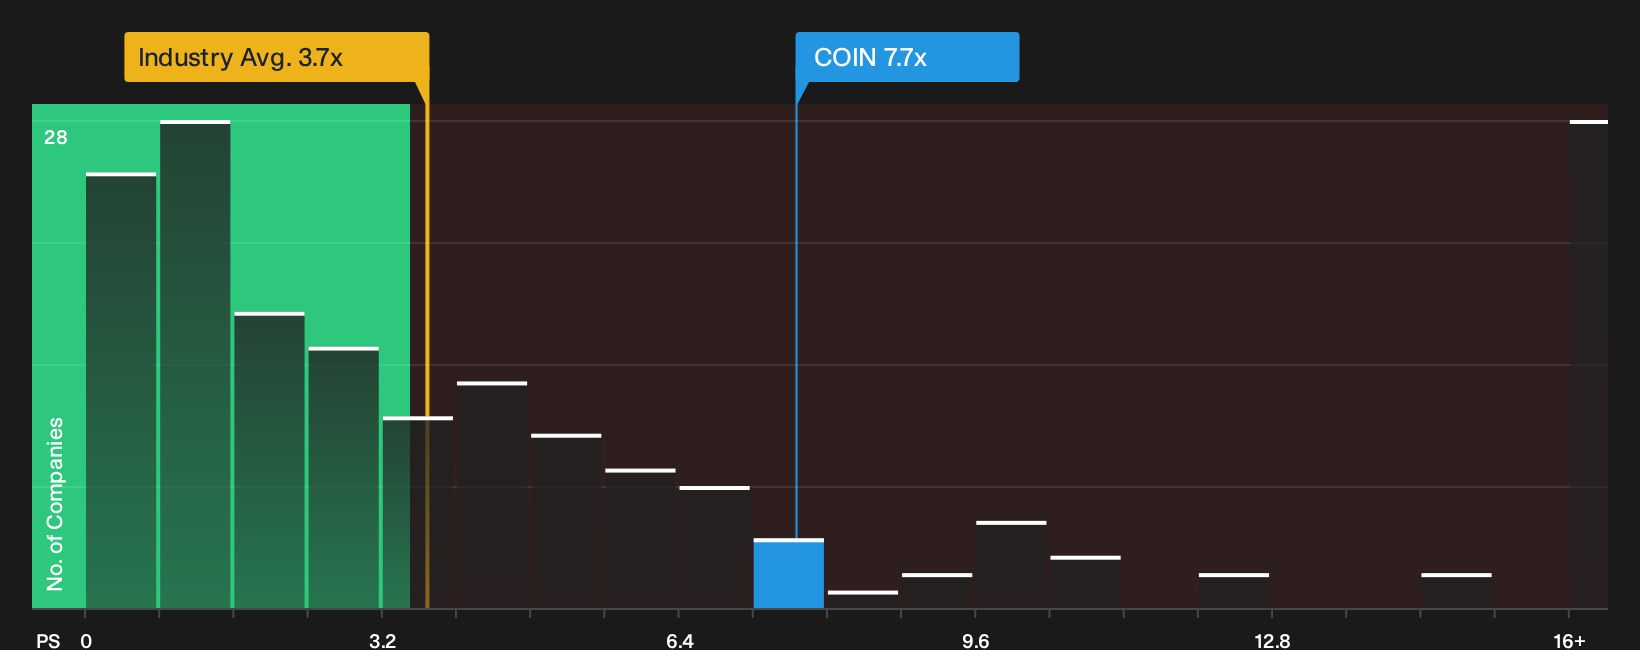
P/S suits Coinbase Global because revenue tends to swing with trading activity, so sales give you a clean anchor when earnings jump around. On this measure, the stock trades on a P/S of 7.7x, compared with a Capital Markets industry average of 3.7x and a peer group around 9.2x. That puts Coinbase somewhere between a typical broker valuation and the richer pricing of closer crypto peers.
The fair P/S ratio from Simply Wall St’s model sits at 4.7x. This reflects what investors might usually pay given Coinbase Global’s size, margins and risk profile. Against that yardstick, today’s 7.7x suggests investors are paying a sizeable premium for the Everything Exchange story, even after recent excitement around Bitcoin ETFs and new derivatives products.
On the preferred P/S yardstick, Coinbase Global currently screens as overvalued compared with both its tailored fair multiple and the wider industry.
See what the numbers say about this price — find out in our valuation breakdown.
The Coinbase Global Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Coinbase Global's valuation puzzle leaves off. They spell out which growth, margin and earnings paths would need to play out for the share price to end up meaningfully higher or lower than it is today. Each scenario ties a fair value to a particular mix of potential catalysts and risks so you can track over time which version of Coinbase Global's story is actually unfolding.
Community views on Coinbase Global could hardly be further apart, with one side leaning into the Everything Exchange roadmap and the other fixated on cyclicality and regulatory drag.
Bull case: 54% undervalued
"Launch and adoption of proprietary blockchain platforms such as Base and the Base super app could drive user growth via novel on-chain utilities, fostering ecosystem lock-in and potentially improving net margins as higher-margin, service-based revenues increase in the overall mix..."
Read the full Bull Case to see why Coinbase Global could be undervalued
Bear case: 84% overvalued
"The rapid commoditization of crypto trading services and the accelerating shift of users and capital to decentralized finance platforms is likely to erode Coinbase's core retail business, compressing net margins as price competition intensifies and transaction fees trend toward zero..."
Read the full Bear Case to see why Coinbase Global could be overvalued
Do you think there's more to the story for Coinbase Global? Head over to our Community to see what others are saying!
The Bottom Line
Coinbase Global now trades on market multiples that point to an overvalued profile, with investors clearly paying up for the Everything Exchange pitch and related optionality. That kind of setup can persist if confidence in future revenue and margin potential stays high; however, it also leaves the share price more exposed if sentiment around crypto activity, regulation or competition cools. The real hinge from here is whether Coinbase Global can translate its broader ecosystem ambitions into durable, higher quality earnings that justify a premium, rather than a valuation built mainly on story and momentum.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com