


3 US Freight Stocks Facing Diesel Margin Pressure
Inflation is proving stubborn, diesel prices have surged, and freight operators are caught in the crossfire as fuel costs squeeze margins while customers still expect fast, cheap delivery. That mix creates both risk and potential openings for investors who can sort resilient freight and logistics stocks from the rest. This article walks through three companies from our diesel-sensitive screener that appear better positioned in the latest macro reset.
The companies highlighted below are just a small sample from this fuel-sensitive freight group, and the full screen surfaced 20 more US operators with equally detailed stories that are not covered here. To identify potential opportunities that fit your own risk tolerance, head straight into the US Freight and Logistics Operators Facing Diesel-Driven Margin Pressure screener to filter the universe and analyze which businesses you want to research further.
Werner Enterprises (WERN)
Overview: Werner Enterprises is a large truckload carrier moving general and temperature controlled freight for retailers and manufacturers across North America, so diesel costs matter.
Operations: Werner generates about US$2.3b from Truckload Transportation Services, US$848 million from Werner Logistics, and almost all revenue from the United States.
Market Cap: US$2.3b
Werner Enterprises is a useful test case for this diesel driven screener, because its truckload fleet, logistics arm and customer mix all feel rising fuel and input costs in slightly different ways.
"The rapid acceleration of automation, AI, and emerging logistics technology threatens to displace traditional trucking models, forcing Werner Enterprises to make increasingly large, ongoing capital investments just to remain competitive."
What happens to Werner Enterprises' margins if a single unseen pressure on pricing power and fuel cost recovery shifts against it?
If that squeeze on Werner Enterprises' pricing power worries you, read the full narrative for Werner Enterprises to see how diesel risk, automation spend and contract structures could be decoupling.

Old Dominion Freight Line (ODFL)
Overview: Old Dominion Freight Line runs a dense less than truckload network across the US, where diesel costs and fuel surcharges directly shape profitability.
Operations: Old Dominion Freight Line generates about US$5.6b in revenue from regional, inter regional and national LTL freight services.
Market Cap: US$37.4b
In a world of persistent inflation and volatile diesel prices, Old Dominion Freight Line matters because its dense LTL network makes fuel costs, surcharge discipline and operating efficiency key factors that can separate resilient carriers from those that see margins pressured.
"Old Dominion Freight Line is focused on maximizing operating efficiencies and reducing discretionary spending to protect their operating ratio, which could support net margins."
A key risk is that any unresolved pressure on pricing power and diesel surcharge recovery may start to work against those carefully managed margins.
That pressure on Old Dominion Freight Line's pricing levers makes the full narrative for Old Dominion Freight Line a useful next step to see whether fuel volatility is masking a stronger long term story.

Covenant Logistics Group (CVLG)
Overview: Covenant Logistics Group runs trucking, freight brokerage and warehousing operations across the US, so diesel costs flow straight through to profitability.
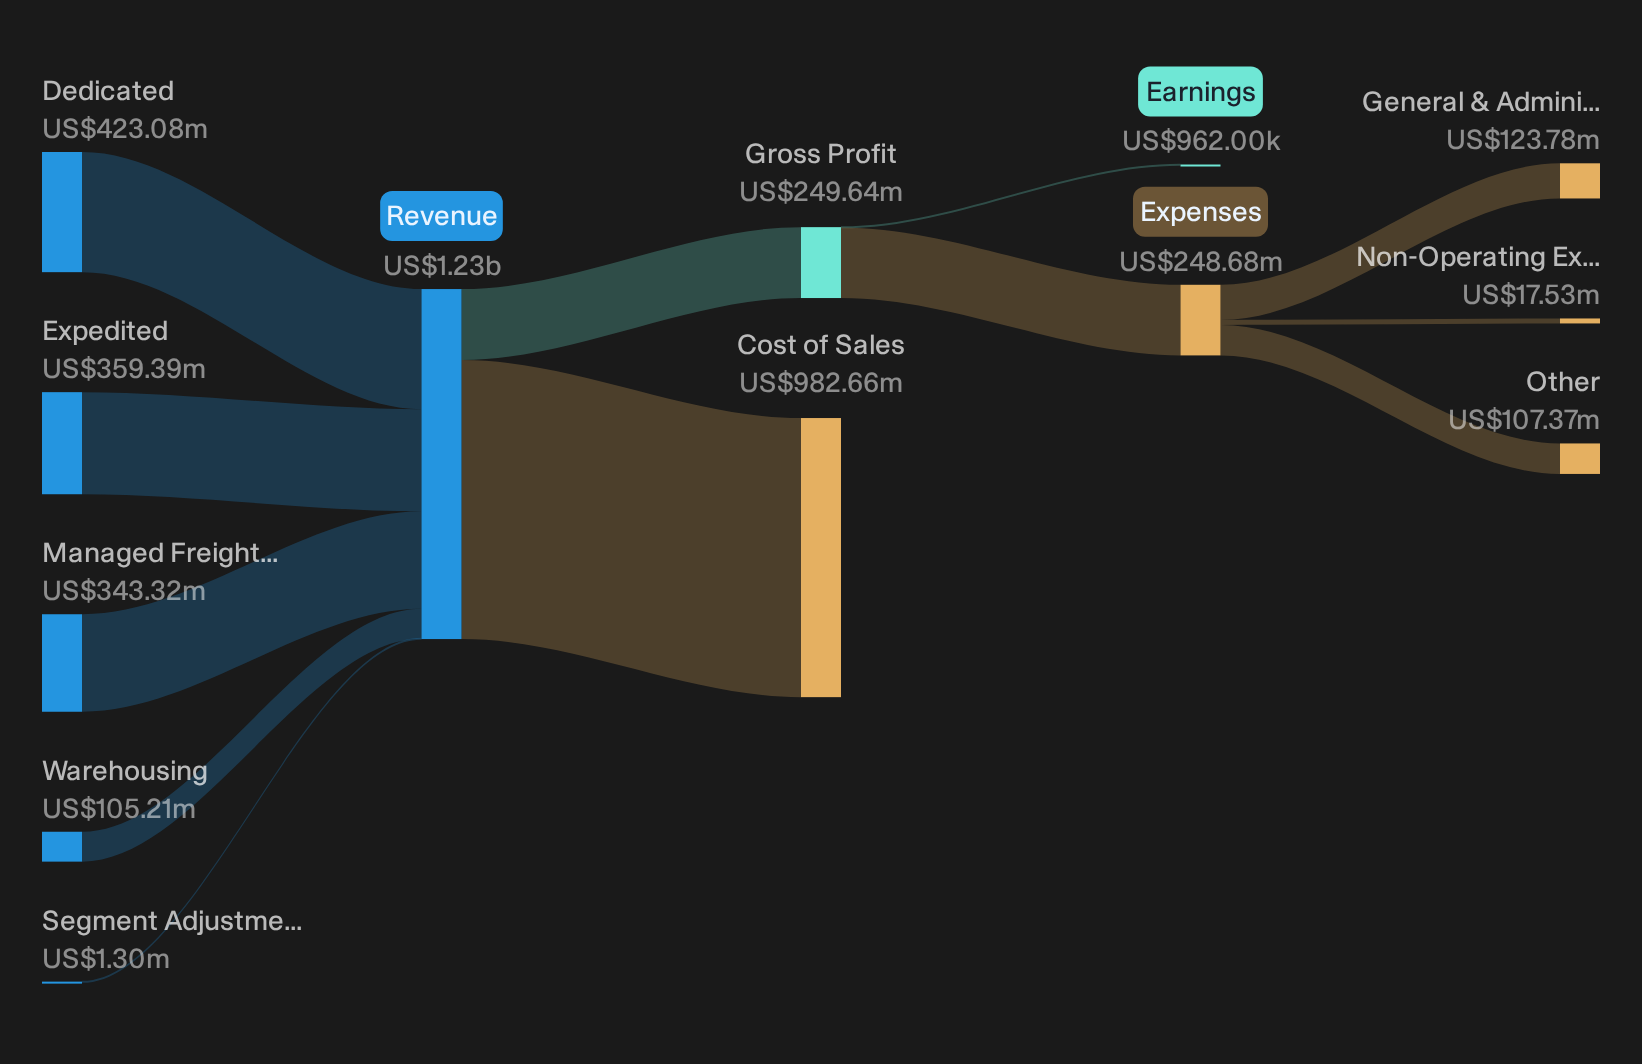
Operations: Covenant Logistics Group generates US$423 million from Dedicated, US$359 million from Expedited, US$343 million from Managed Freight and US$105 million from Warehousing, almost entirely in the United States.
Market Cap: US$895 million
Covenant Logistics Group matters to this diesel focused screen because a large truckload fleet, time critical freight and multi year contracts all shape how rising fuel costs show up in cash flow rather than just in headline rates.
"Industry wide constraints on driver availability and increased enforcement of ELD and safety rules are removing capacity from the market and are contributing to rising contract rates, which Covenant Logistics Group expects to capture over time in the form of higher revenue per mile and improved operating margin."
What happens to Covenant Logistics Group's thin margins if a single unseen pressure on contract repricing and fuel cost recovery shifts against it?
If that fuel recovery risk is on your mind, read the full narrative for Covenant Logistics Group to see whether diesel pressure is masking an accelerating earnings reset story.
Seeking Alternatives Before They Take Off
Fresh ideas move first, and slow capital often gets caught chasing momentum once prices are already flying. Scan these curated lists while it matters and get in early.
- Spot stronger balance sheets before they attract broad attention by reviewing the curated list of solid balance sheet and fundamentals (23 results) that filters for resilience while others are still reacting.
- Ride early breakout potential in resource producers by working through the focused 35 elite gold producer stocks before renewed interest drives wider crowd momentum.
- Track early moves in power infrastructure demand by scanning the curated 39 power grid technology and infrastructure stocks while these stories remain under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com