


Toyoda Gosei (TSE:7282) Could Be 53% Undervalued As New Bond Sale Tests Valuation
Toyoda Gosei (TSE:7282) has moved into the bond market with new unsecured sustainable straight notes, due September 10, 2031, totaling ¥10 billion. This funding decision gives investors fresh information about capital structure and financing priorities.
Against that funding backdrop, Toyoda Gosei’s recent trading activity indicates that investors are still engaged. The share price is up 12.5% over 90 days and has a 27.9% year-to-date share price return, while the 1-year total shareholder return of 41.7% points to positive longer-term momentum.
Scan beyond Toyoda Gosei and see how other auto suppliers with sizeable funding needs and a focus on the balance sheet line up in the list of solid balance sheet and fundamentals (19 results).
Bulls point to Toyoda Gosei’s recent returns and fresh sustainable funding as signs the market still underestimates it. Bears see new debt as a warning flag. Which story fits the valuation that follows?
Price-to-Earnings of 9.1x: Is it justified?
Toyoda Gosei looks inexpensive on paper, with a P/E of 9.1x while earnings have been growing and the SWS DCF model points to a higher cash flow value than the current ¥5,149 share price.
The P/E ratio compares what investors pay today for each unit of profit. For an auto components supplier like Toyoda Gosei, it often reflects how confident the market feels about the durability of margins and future demand in a cyclical industry.
Here, the stock is described as good value on several fronts. The P/E of 9.1x is below the peer average of 24x and also slightly under the broader JP Auto Components industry on 9.6x. That discount is reinforced by the estimated fair P/E of 12.4x, which is higher than where the shares trade today and indicates the valuation may move closer to that level if the current earnings profile and growth outlook are sustained.
To understand how that fair P/E level is derived and what would need to change for the market to close the gap, take a closer look at the SWS fair ratio workup in the Explore the SWS fair ratio for Toyoda Gosei.
Result: Price-to-Earnings of 9.1x (UNDERVALUED)
Still, Toyoda Gosei carries risks if auto demand softens, or if the new ¥10b sustainable notes increase pressure on cash flows and limit flexibility.
Find out about the key risks to this Toyoda Gosei narrative.
Another View on Toyoda Gosei’s Value
There is a different lens you can use. Our DCF model estimates Toyoda Gosei’s future cash flow value at ¥11,069.96 per share, compared with the current ¥5,149 price. That gap points to an undervalued stock on this measure. The question is whether you trust the cash flow assumptions more than the earnings multiple story.
Look into how the SWS DCF model arrives at its fair value.
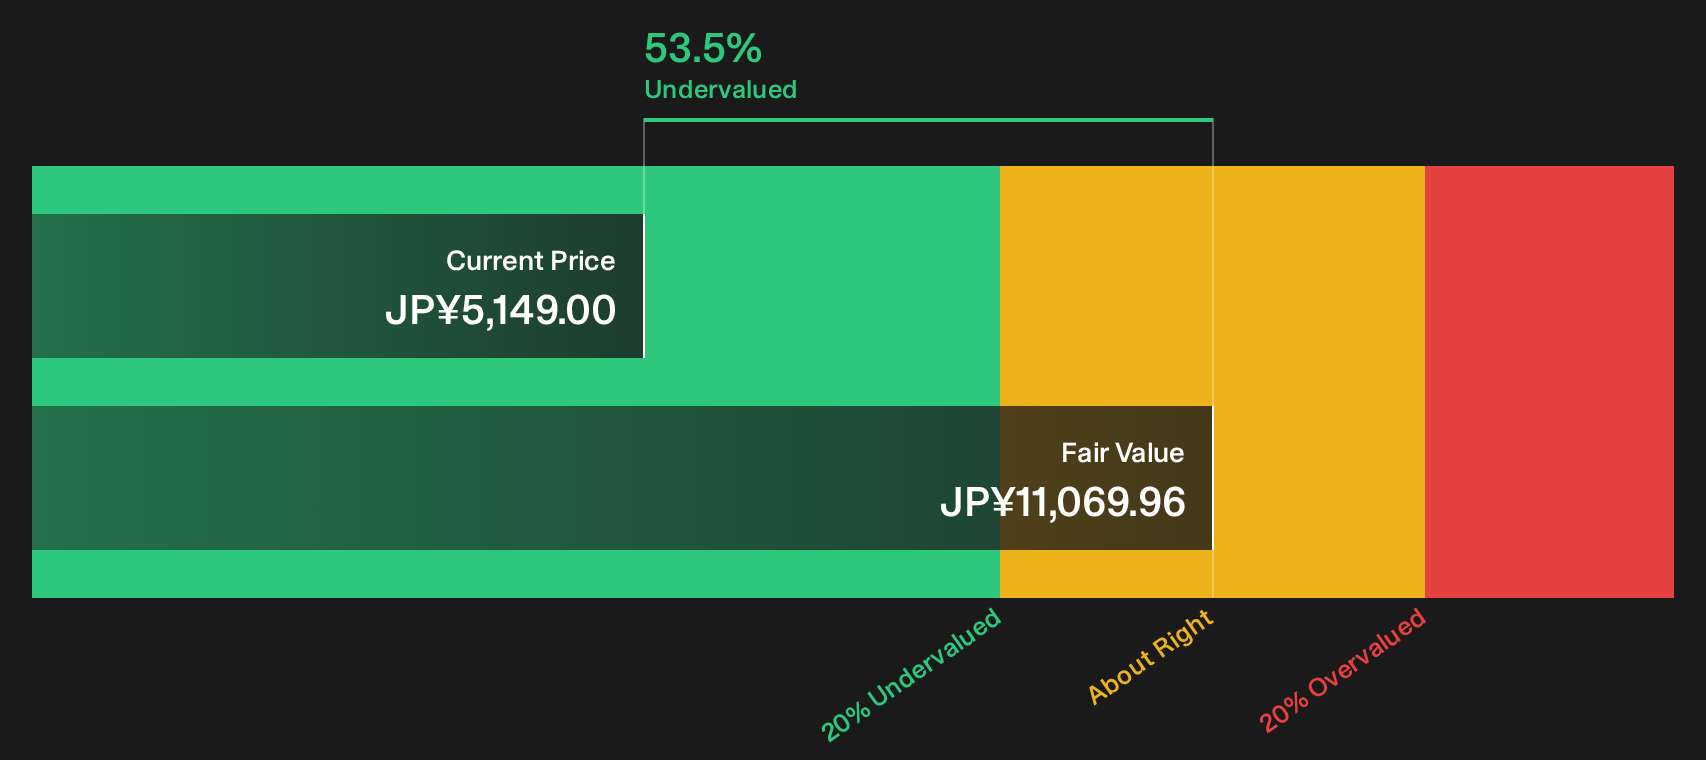
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Toyoda Gosei for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Toyoda Gosei can feel confusing. Use them as a prompt to move quickly, review the full data, and weigh the 4 key rewards and 1 important warning sign
Looking for more Toyoda Gosei style investment ideas?
If Toyoda Gosei has you thinking harder about price, quality, and risk, do not stop at a single opportunity when wider markets offer plenty of options.
- Target robust cash generators and use the 17 high quality undervalued stocks to spot companies where price and fundamentals may be out of sync.
- Prioritise resilience and protect your capital base with the 10 resilient stocks with low risk scores that filters for businesses with steadier risk profiles.
- Zero in on strong financial footing and disciplined funding by reviewing the list of solid balance sheet and fundamentals (19 results) before the crowd pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com