


Firefly Aerospace (FLY) Stock Looks Fully Priced Despite A 52% Fall
Firefly Aerospace has had a tough run over the past year, with a steep share price decline sitting awkwardly next to valuation checks that still flag the stock as expensive rather than a bargain.
- The share price has fallen 51.7% over the last 12 months, which puts Firefly Aerospace firmly in the penalty box for many investors.
- Fresh contracts such as the multi launch deal with SSC Space and radar work linked to the U.S. Space Force can support long term revenue hopes. However, execution risk on complex space projects may keep a heavy discount on the equity if setbacks occur.
- The broader valuation score is low, with 2 out of 6 checks suggesting Firefly Aerospace does not screen as a clear bargain on current metrics.
For investors, the debate is whether Firefly Aerospace is now cheap for a reason or whether the recent share price slide has already absorbed the main valuation risk.
Spot our screener containing 16 high quality undiscovered gems that have been hand picked for stronger fundamentals than Firefly Aerospace's low valuation score and steep 1 year share price decline.Has Firefly Aerospace Run Too Far on Sales?
P/S is usually a cleaner lens for Firefly Aerospace because the company is still working toward consistent profitability and earnings-based ratios are less useful in that phase.
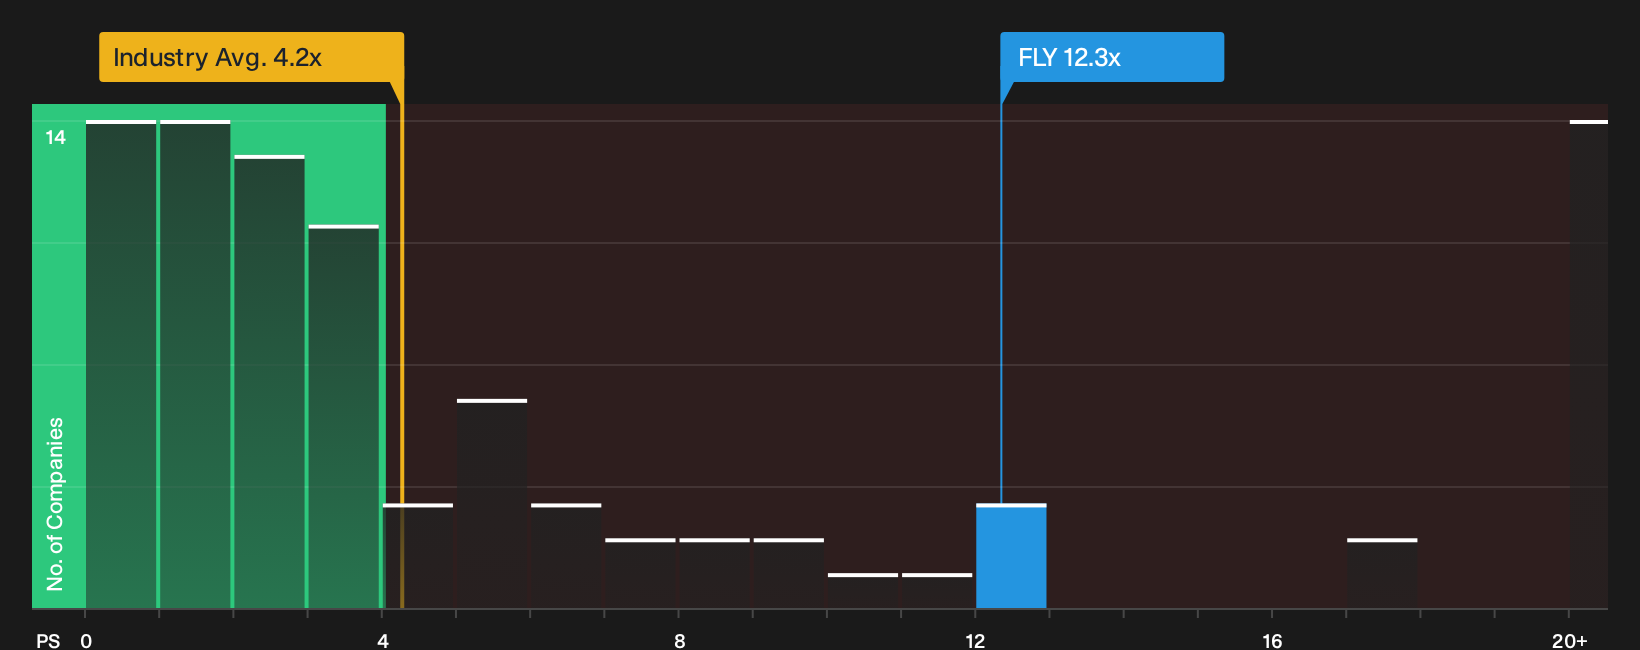
The stock trades on a P/S multiple of 12.3x, which is almost three times the Aerospace & Defense industry average of 4.2x and well above the peer group at roughly 4.4x. The tailored fair multiple for Firefly Aerospace is 6.0x, so the current valuation sits close to double what this framework suggests would be reasonable given its risk profile and sector context. Despite fresh contracts with SSC Space and radar work tied to the U.S. Space Force, the current pricing already asks investors to pay a steep premium for each dollar of revenue.
On this P/S lens, Firefly Aerospace stock appears significantly overvalued.
See what the numbers say about this price — find out in our valuation breakdown.
The Firefly Aerospace Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Firefly Aerospace pick up where this valuation puzzle leaves off and spell out which expectations for future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's market price on the Community page. Rather than relying on a single multiple or model output, each narrative lays out the assumptions behind its view of fair value so you can compare those inputs with actual results as they are reported over time.
One of the top community narratives on Firefly Aerospace: 95% undervalued
"The company’s been landing more contracts with NASA and the Department of Defense, and the demand for small-to-medium satellite launches is growing fast…"
Read one of the top narratives on Firefly Aerospace
Do you think there's more to the story for Firefly Aerospace? Head over to our Community to see what others are saying!
The Bottom Line
Firefly Aerospace still carries an overvalued label on simple market multiples, with the P/S gap to peers doing most of the heavy lifting in that verdict. The low broader valuation score reinforces the idea that this is not a clear-cut bargain on today’s fundamentals. For the thesis to work from here, the key swing factor is whether execution on contracts and future revenue delivery can eventually justify paying such a premium for every dollar of sales, rather than that premium proving to be a value trap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com