


Revenue Miss Might Change The Case For Investing In First Financial Bancorp Stock
- First Financial Bancorp recently reported a softer quarter, with revenue growing year on year but falling 2.9% short of analyst expectations and net interest income also below estimates, while earnings per share aligned with projections.
- The results highlight pressure on the bank’s core lending economics as fintech competition and rising regulatory costs weigh on profitability and operating flexibility.
- We will look at how First Financial Bancorp's revenue shortfall versus expectations interacts with its longer term, efficiency-focused investment narrative.
Compare how First Financial Bancorp stacks up against peers facing similar pressures by scanning our curated list of 11 resilient stocks with low risk scores that align with tighter regulation and margin pressure.
First Financial Bancorp Investment Narrative Recap
For you to stay interested in First Financial Bancorp, you need to believe its efficiency and digital investments can offset pressure on core lending economics. The latest quarter, with revenue 2.9% below expectations and net interest income under pressure, tests that belief but does not break it. The near term swing factor is whether margins stabilise as deposit costs, fintech competition, and loan pricing jostle for influence.
The biggest near term risk remains credit and margin pressure in a regionally concentrated book with commercial real estate exposure and an aging Midwest customer base. Any renewed squeeze on spreads or weaker loan demand could blunt the benefit of earlier cost work. For now, the earnings per share in line with projections suggests the impact is manageable rather than thesis breaking.
Recent discussion around First Financial Bancorp has centred on its efficiency program and digital transformation, which were already flagged as key operational levers. Those efforts include process redesign, technology spending, and a push to reduce reliance on branches. Against a softer revenue print, execution on those projects becomes more important as a way to protect profitability if lending spreads remain tight.
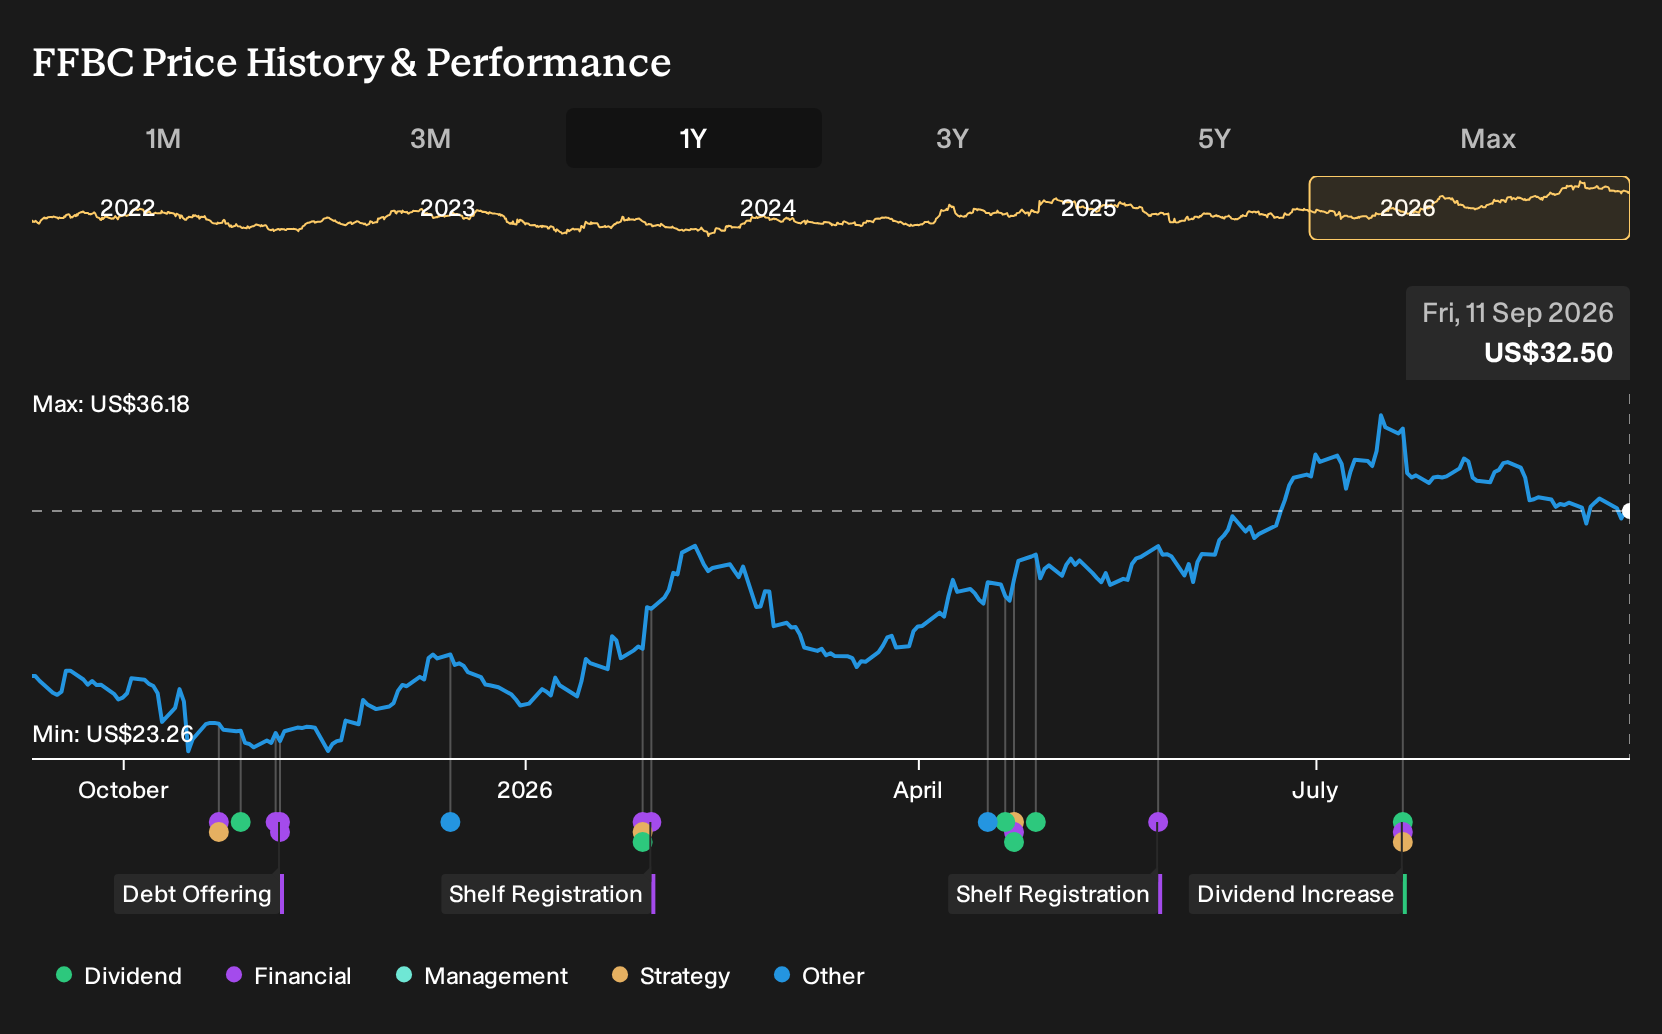
The acquisition of Westfield Bank also sits in the background as a practical test of the growth story. Management is aiming for extra scale, market share and cost leverage from that deal. With the stock down 8.8% since the Q2 report, investors are likely watching whether integration delivers the expected operating benefits and whether the combined platform supports more stable earnings despite margin and regulatory headwinds.
First Financial Bancorp's current earnings sit at $285.2 million, with analyst consensus pointing to $446.7 million by 2029. That implies an earnings increase of about $161.5 million and projected revenue of $1.3 billion in the same year, based on an assumed 11.9% yearly rise in revenue over the next few years.
Discover how First Financial Bancorp's fair value indicates a 13% potential upside to its current price that could close more quickly than many investors expect.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$36.86 and US$52.76, which shows how far retail views on First Financial Bancorp can stretch. Before reacting to that spread, weigh the unresolved risks around Midwest exposure and commercial real estate, and then explore more Community viewpoints for context.
Explore another First Financial Bancorp fair value estimate, including one that suggests it could be worth just $36.86.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your First Financial Bancorp research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First Financial Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Financial Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond First Financial Bancorp?
Once you have a view on First Financial Bancorp, it can help to widen the lens and compare it with other listed businesses that share some of the same themes around risk, quality, and balance sheet strength.
- For investors who care most about balance sheet resilience and clean fundamentals, start with this curated list of solid balance sheet and fundamentals (23 results) that can help you spot companies built to handle tougher conditions.
- If income is a priority and you want payouts that could better withstand rate moves and regulatory costs, scan through the 6 dividend fortresses to see which stocks combine yield with sturdier financial profiles.
- When you are searching for underappreciated quality and are willing to do extra homework, use the 16 high quality undiscovered gems to surface lesser known companies that still screen well on core fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com