


Iridium Communications (IRDM) Puts NTN Progress In Focus As Fair Value Debate Heats Up
Iridium Communications (IRDM) just put its non terrestrial network in the spotlight after a live demo with Deutsche Telekom IoT and Toyota that showed voice messaging over Iridium NTN Direct from a connected vehicle.
Against that backdrop, Iridium Communications has had a powerful run, with a year to date share price return of 166.33% and a 1 year total shareholder return of 172.81%. This is the case even though the 30 day share price return declined 4.73% and the recent 7 day move was marginal.
Capitalize on Iridium Communications putting non terrestrial connectivity on the map by scanning a curated group of IoT and infrastructure plays in our 89 AI infrastructure stocks.For Iridium Communications, a 166% year to date surge sits next to a flat 90 day line and a softer 30 day stretch. Is this still a business story, or now mostly a sentiment story that the valuation needs to sort out next?
Most Popular Narrative: 12.6% Overvalued
The most followed valuation narrative puts Iridium Communications' fair value at $42, compared with a last close of $47.30, which leaves the story framed by a higher market price than that model suggests.
The analysts have a consensus price target of $42.0 for Iridium Communications based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $1.0 billion, earnings will come to $170.7 million, and it would be trading on a PE ratio of 31.9x, assuming you use a discount rate of 7.1%.
Read the complete narrative. Read the complete narrative.
Want to see what has to go right for Iridium Communications to support that valuation gap? The narrative leans on faster top line expansion, fatter margins, and a future earnings multiple that sits well above the sector norm. The full breakdown spells out the growth path, the profitability lift, and the pricing power that all need to hold together for that fair value to make sense.
Result: Fair Value of $42 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the story can crack if IoT momentum keeps slowing or if capital needs for the next satellite cycle climb, which would pressure Iridium Communications' cash generation and sentiment.
Find out about the key risks to this Iridium Communications narrative.
Another View On Iridium Communications Valuation
The analyst narrative frames Iridium Communications as 12.6% overvalued at $47.30 compared with a $42 fair value. The SWS DCF model takes a very different angle and values the same shares at $82.91 based on future cash flows, which implies a wide upside gap. Which lens do you trust more?
Look into how the SWS DCF model arrives at its fair value.
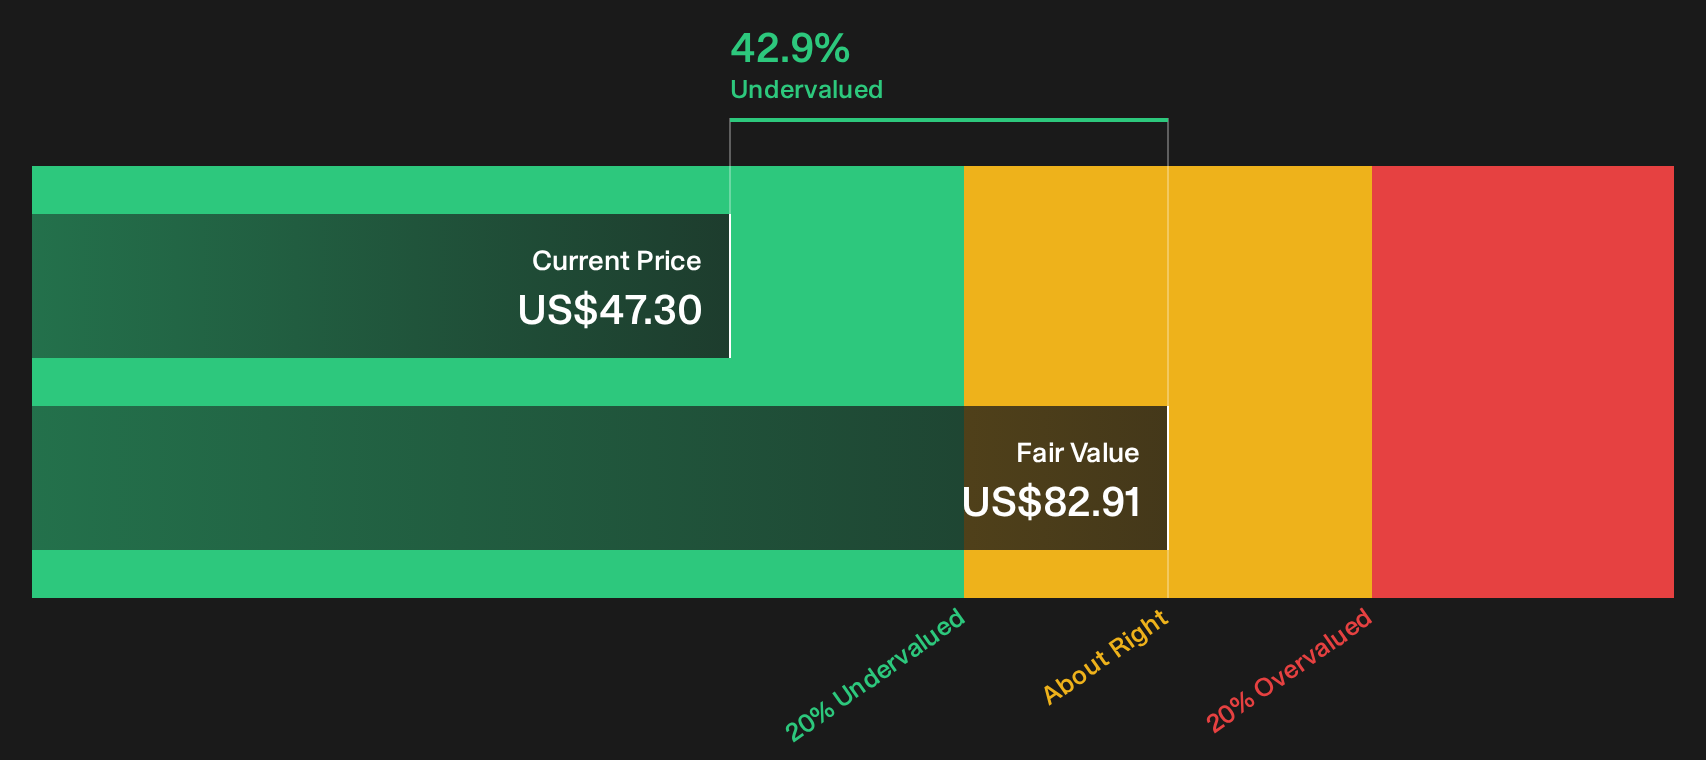
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Iridium Communications for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Iridium Communications story so far. Move quickly, review the full data set, then weigh both sides through the 2 key rewards and 2 important warning signs.
Looking for more Iridium Communications sized ideas?
If Iridium Communications has your attention, do not stop at one ticker. Use the Simply Wall Street Screener to surface fresh, data driven ideas before others move first.
- Target resilient cash generators with low expectations baked in by scanning our 31 high quality undervalued stocks.
- Lock in potential income streams by focusing on companies in the 6 dividend fortresses.
- Prioritize financial strength over hype by filtering for businesses using the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com