


Calumet (CLMT) Could Be 23% Undervalued After Crude Supply Fears Lifted Energy Stocks
Escalating attacks on Middle East shipping corridors and production shut ins have pushed crude benchmarks toward an 8% weekly gain, and Calumet (CLMT) has moved higher as investors reassess exposure to refining and renewable fuels.
For context, Calumet’s share price has climbed to US$56.80, with a 30-day share price return of 20.36% and a 90-day gain of 65.02%. The year-to-date share price return of 190.54% and a 1-year total shareholder return of 226.62% point to strong momentum that recent crude-driven optimism has only reinforced.
Scan other energy players that could be reacting to the same crude supply shock as Calumet by reviewing our curated list of 39 power grid technology and infrastructure stocks
After a near tripling in a year and a recent surge tied to crude anxiety, Calumet now sits at a US$56.80 price tag. Does the current balance of risk and reward still lean toward buyers or toward caution as valuation comes into focus?
Most Popular Narrative: 6% Overvalued
Analysts see Calumet’s fair value at $53.40, slightly below the recent $56.80 close. This frames the current rally as richer than that narrative implies.
The MaxSAF 150 project is on track to start up in the first half of 2026, enabling Calumet to produce 120-150 million annual gallons of sustainable aviation fuel (SAF) at relatively low capital costs. This positions the company to capture premiums of $1-$2 per gallon over renewable diesel and to participate in mandated and voluntary SAF demand globally. This is likely to drive a material increase in revenues and EBITDA margin expansion once operational.
Analysts are effectively betting that a mix of higher profitability, steadier cash generation, and a moderate valuation multiple can justify today’s price tag. Want to see which growth, margin, and earnings path that story relies on, and how those assumptions turn into a single fair value number for Calumet.
Result: Fair Value of $53.40 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, that story can unravel quickly if regulatory support for renewable fuels weakens or if Calumet’s high debt load limits flexibility when conditions shift.
Find out about the key risks to this Calumet narrative.
Another View: Calumet Through A Cash Flow Lens
Analysts see Calumet as 6% overvalued at a US$53.40 fair value, yet our DCF model points in the opposite direction. On that cash flow based view, the stock screens around 23% below an estimated value of US$74.03. Which story do you think better fits the risks you see?
Look into how the SWS DCF model arrives at its fair value.
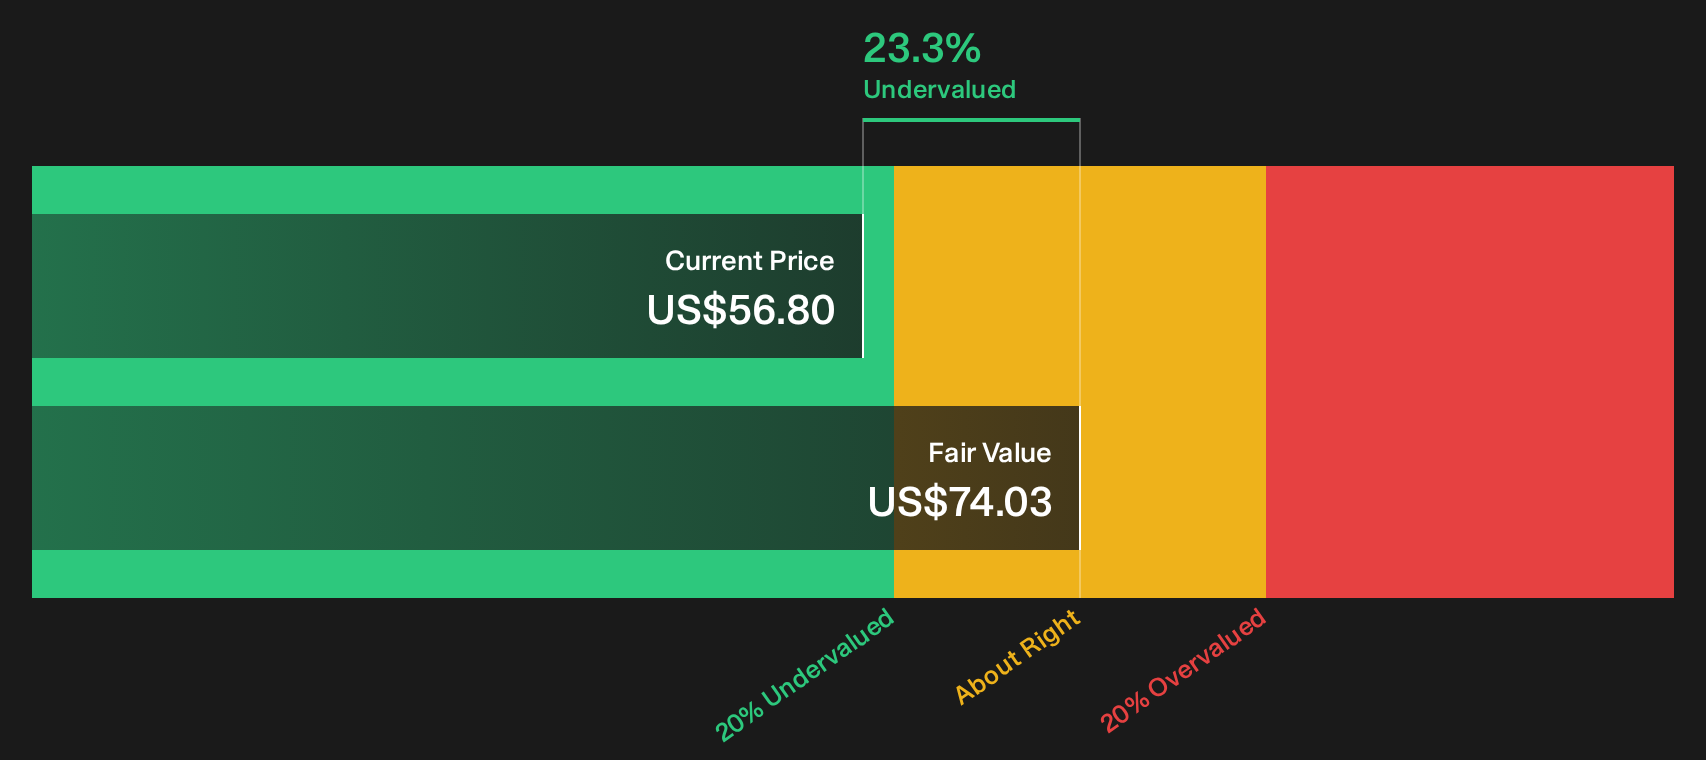
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Calumet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of enthusiasm and concern around Calumet feels familiar, consider acting promptly, review the full data set for yourself, then weigh the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Calumet?
If the Calumet story has sharpened your focus, do not stop here. Broaden your watchlist with fresh ideas that match your risk tolerance and return goals.
- Target potential mispricings by running through a focused set of 31 high quality undervalued stocks that pair quality fundamentals with compressed valuations.
- Strengthen the defensive side of your holdings by scanning a list of solid balance sheet and fundamentals (23 results) that can handle tougher conditions without constant refinancing worries.
- Get ahead of the crowd by shortlisting a 16 high quality undiscovered gems before they land on every investor's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com